


As an Australian property investor, understanding tax deductions for rental property is your most powerful tool for improving cash flow and maximising returns. To begin with, the golden rule—set out clearly under Australian tax legislation—is refreshingly simple: if you spend money to generate rental income, you can generally claim it as a deduction. In other words, any expense directly tied to earning rental income has the potential to reduce your taxable income. As a result, the more aware you are of what qualifies, the better positioned you’ll be to strengthen your investment’s financial performance.
Let’s unpack what that really means for your bottom line.
Your Guide to Rental Property Tax Deductions
Owning a rental property goes beyond simply collecting rent; in fact, it means running a small business. Just like any business, you aim to boost your income while legally trimming your expenses. This is precisely why mastering tax deductions for rental property becomes a game-changer—it transforms your investment from a basic asset into a powerful financial engine.
Moreover, the Australian Taxation Office (ATO) gives you the opportunity to claim a wide range of expenses against your rental income. Consequently, you shrink your taxable income and ultimately pay less tax. Put simply, every dollar you legitimately claim is a dollar that stays in your pocket—ready to reinvest, use for debt reduction, or strengthen your overall financial position.
The Core Principle of Deductibility
According to the ATO, you can claim a deduction for expenses as long as your property was rented or genuinely available for rent during the period the expense occurred. In particular, that “genuinely available for rent” condition matters, especially for holiday homes that also see private use. To qualify, you must actively advertise the property and, at the same time, set reasonable rental conditions that would attract tenants. Furthermore, under the Income Tax Assessment Act 1997, the connection between the expense and the income-producing activity must remain crystal clear. Ultimately, understanding this requirement is essential for investors who want to maximise their tax deductions for rental property while staying fully compliant with ATO rules.
Why Strategic Claiming Matters
When you strategically claim deductions, you don’t just save money at tax time—you also directly improve your investment’s performance. For instance, claiming immediate expenses provides a quick win by boosting your cash flow year-on-year. At the same time, leveraging long-term deductions such as depreciation delivers a significant “on-paper” loss while still leaving the actual cash in your hand untouched. As a result, you create a balanced approach that both strengthens your short-term finances and enhances your long-term wealth strategy.
The ATO consistently highlights that around nine out of ten investment property owners make errors in their tax returns. This statistic is a huge wake-up call, underscoring how important it is to get it right. Simple mistakes can lead to audits, penalties, and missed financial opportunities.
Understanding and using these deductions is one of the most vital strategies for maximizing passive income from your rental property. Getting this right from the start sets a strong, profitable foundation for your entire investment journey.
Mastering Interest and Depreciation Claims
When it comes to tax deductions for rental property, two claims consistently pack the biggest punch for Australian investors: loan interest and property depreciation. Getting these right not only keeps you compliant but also unlocks the full financial potential of your asset.
For most landlords, loan interest takes the top spot as the single largest deductible expense. Running a close second is depreciation—a powerful non-cash deduction that captures the natural wear and tear of your property and its fittings over time. Together, these two deductions can dramatically reduce your taxable income.
Navigating Loan Interest Deductions
You can almost always fully deduct the interest you pay on a loan used to buy a rental property. This includes not only the loan’s interest itself but also associated borrowing costs such as loan establishment fees, mortgage broker fees, and even Lenders Mortgage Insurance (LMI).
However, you must remember a crucial detail: you can only claim the interest portion of your repayments—not the principal amount that pays down the loan balance. The golden rule, under Section 25-25 of the Income Tax Assessment Act 1997, is clear: the expense must directly relate to generating rental income.
In fact, ATO data confirms that loan interest consistently ranks as the largest deduction claimed by Australian landlords. Yet, the ATO also reports that nine out of ten landlords make errors on their tax returns. Therefore, accuracy is everything, especially when your loan structure gets complicated.
The Rules of Apportionment
Things become tricky when you use a single loan for both investment and private purposes. In this case, the ATO requires you to apportion the interest. Put simply, you can only claim the part directly tied to your rental property.
Here’s a practical example:
You take out a $600,000 loan.
You use $500,000 of it to purchase a rental property.
You spend the remaining $100,000 on a new car for personal use.
In this scenario, only the interest on the $500,000 investment portion is deductible. You calculate your deductible share as $500,000 ÷ $600,000 = 83.33%. As a result, you can claim 83.33% of the total interest paid for that financial year.
Expert Tip: Never use an investment property loan or its redraw facility for private expenses like a holiday or a new car. The ATO heavily scrutinises mixed-purpose loans, and failing to correctly apportion interest is one of the most common mistakes that can trigger an audit.
Unlocking the Power of Depreciation
Depreciation stands out as one of the most valuable—yet often misunderstood—tax deductions for rental property. Unlike most expenses, it’s a non-cash deduction, meaning you don’t actually spend money during the year to claim it. Instead, it reflects the natural decline in value of your building and its assets as they age.
To make things clearer, the ATO splits depreciation into two main categories:
Capital Works (Division 43): This category covers the building’s structure and items permanently fixed to it. Think of the foundations, walls, roof, or built-in cupboards. For residential properties built after 15 September 1987, you can typically claim 2.5% of the construction cost each year for up to 40 years.
Plant and Equipment (Division 40): This category applies to assets within the property that are removable or mechanical. Because these items generally wear out faster than the building itself, their deduction periods are much shorter.
Examples of plant and equipment include:
Carpets and blinds
Ovens and cooktops
Dishwashers
Air conditioning units
Hot water systems
By claiming depreciation correctly, you not only reduce your taxable income but also make your property investment significantly more tax-efficient over the long term.
Each of these assets has an “effective life” set by the ATO, and you claim a deduction for its decline in value over that specific period. For instance, carpets might have an effective life of 8 years, while a hot water system could be 12. Even mandatory safety upgrades, like those required by the interconnected smoke alarm legislation in QLD, are significant costs that can often be depreciated.
To claim capital works correctly, you must know the property’s original construction cost—not the price you paid for it. This detail is vital because it establishes the foundation of your deduction claim. Without it, you risk under-claiming or misreporting.
Maximise Your Claims with Professional Guidance
Although you might try estimating some costs yourself, the smartest way to maximise your depreciation claims—and stay fully compliant with the ATO—is to engage a qualified quantity surveyor. A professionally prepared depreciation schedule breaks down every claimable asset, its value, and its effective life. As a result, you gain a clear roadmap for your tax return that continues to benefit you year after year.
When you get your loan interest and depreciation claims right, you dramatically reduce your taxable income and improve your property’s cash flow. If you’re unsure how these rules apply to your situation, expert guidance makes all the difference. Book a free consultation with an Endurego Tax specialist today and ensure you claim every dollar you’re entitled to.
Claiming Everyday Rental Property Expenses
Beyond the big-ticket deductions like loan interest and depreciation, you can also claim a wide range of immediate expenses in the same financial year you pay them. These deductions directly lower your taxable income and give your cash flow an instant boost—no waiting required.
Understanding this list is one of the most valuable steps you can take as a landlord. Why? Because every small claim adds up, and you don’t want to leave money on the table. From property management fees to fixing a leaky tap, these everyday expenses genuinely improve your investment’s bottom line.
Your Checklist of Immediate Deductions
Think of these as the day-to-day running costs of your property investment “business.” Many of these are fully deductible right away because they’re essential to keeping your property maintained, managed, and generating rental income.
Here’s a quick rundown of common immediate deductions:
Property Management Fees: Costs paid to real estate agents for finding tenants, collecting rent, and managing the property.
Council Rates and Land Tax: Standard holding costs claimable during any rental or genuinely available rental period.
Body Corporate Fees: Regular admin and maintenance charges for units, townhouses, or apartments.
Insurance Premiums: Deductible landlord, building, and contents insurance policies.
Advertising for Tenants: Online listings, newspaper ads, or even a “For Rent” sign.
General Maintenance: Pest control, gardening, cleaning, and lawn mowing services.
Water and Utilities: Any utility costs you cover on behalf of your tenant under the lease agreement.
By keeping track of these everyday expenses, you strengthen your cash flow while maximising your overall tax benefits.
A key principle from the Australian Taxation Office is that you can deduct expenses in the year you actually pay for them. This comes from Section 8-1 of the Income Tax Assessment Act 1997, which allows you to claim any costs you incur while earning your assessable income.
The Critical Difference Between Repairs and Improvements
This is one of the biggest tripwires for property investors, and an area the ATO watches like a hawk. Getting it wrong is a super common mistake that can easily trigger an audit. So, what’s the difference? It all comes down to whether you can claim the full cost now or have to spread it out over many years.
Let’s introduce a handy table to make this crystal clear.
Repair vs. Capital Improvement: What Can You Claim Now?
Understanding this distinction is crucial. Repairs are about maintaining what you have, while improvements are about making it better than it was. Here’s a breakdown:
| Expense Category | What is it? | ATO Treatment | Practical Example |
|---|---|---|---|
| Repair | Fixing something that’s broken, damaged, or worn out to restore it to its original working condition. It’s about restoration, not upgrading. | Immediately Deductible. You can claim 100% of the cost in the same financial year you paid for it. | A storm breaks a few roof tiles. You pay a roofer to replace just those specific tiles to stop a leak. |
| Capital Improvement | Upgrading, renovating, or replacing an entire structure with something new or superior. It enhances the property’s value or changes its character. | Depreciated Over Time. You can’t claim it all at once. The cost is claimed gradually over its “effective life” as a capital works deduction. | Your old, tiled roof is leaking in multiple places. You decide to replace the entire roof with new Colorbond steel. |
When it comes to tax deductions for rental property, the ATO cares about two things: your intention and the scale of the work. A minor fix usually counts as a repair, while a complete replacement typically qualifies as an improvement. Understanding this distinction is fundamental to lodging an accurate tax return.
Practical Example: The Broken Fence
Repair (Immediately Deductible): A strong wind knocks over three palings on your rental’s back fence. You call a handyman who replaces only those three palings, restoring the fence to its original condition. Because the work simply returns the asset to its prior state, the cost counts as a repair. You can claim it in full in the same financial year.
Improvement (Capital Expense): The entire back fence is old, rotting, and leaning over. You decide to remove it and install a brand-new Colorbond fence. Since you’ve replaced the entire structure with a better-quality material, the ATO classifies this as a major improvement. As a result, you must claim the expense as a capital works deduction over its effective life—typically 40 years.
This simple distinction matters. When you get it right, you not only stay compliant but also gain peace of mind knowing your tax return is accurate.
The infographic below highlights how long you can claim larger capital improvements over time, giving you a clear visual guide.
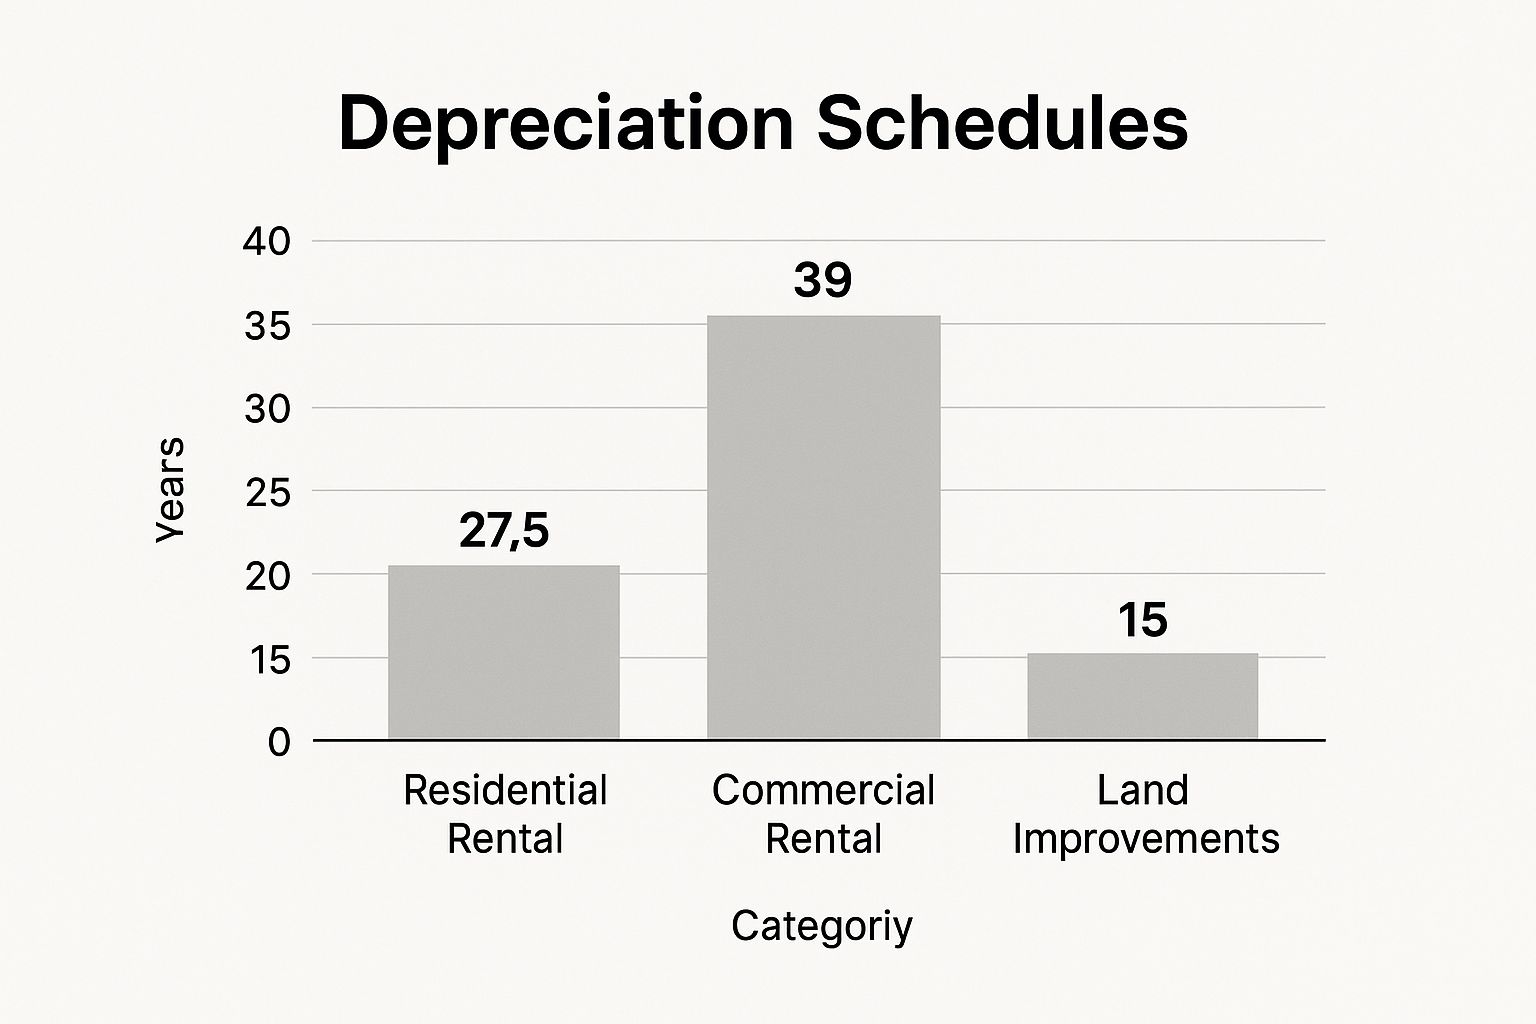
As the chart shows, these major capital works are a long-term claim, which is why it’s so important not to mix them up with immediate repairs.
Navigating the rules around everyday expenses, especially the repair versus improvement dilemma, can feel a bit tricky. To make sure you’re claiming every dollar you’re entitled to without straying outside the ATO’s guidelines, getting a bit of professional advice is a smart move.
Book a free consultation with an EndureGo Tax expert today to review your expenses and make sure you’re maximising your return.
Common Landlord Mistakes and How to Avoid Them
Navigating tax deductions for rental property can often feel like working through a maze—and taking a wrong turn can get expensive. The Australian Taxation Office (ATO) has sharpened its focus on landlord tax returns, and it’s now highly skilled at spotting the common errors that fuel Australia’s massive “tax gap.” Importantly, this isn’t just about catching people who deliberately cheat the system. More often than not, these mistakes come from investors simply misunderstanding the rules.
The best defence is knowledge. By understanding the red flags the ATO looks for, you can confidently lodge a tax return that maximises deductions while remaining solid and defensible. Let’s break down one of the most frequent mistakes property investors make—and how to avoid it.
Mixing Personal and Investment Loan Interest
Right at the top of the ATO’s watchlist is incorrectly claiming loan interest. This mistake usually happens when investors use a single loan or a redraw facility for both investment property expenses and private purchases. The ATO is crystal clear on this: you can only claim interest on the part of the loan that directly generates rental income.
A common trip-up occurs when you refinance an investment loan and withdraw cash for personal use—say, to buy a car or pay for a family holiday—yet continue to claim 100% of the interest on the full loan amount.
Here’s an example of what not to do:
You hold a $400,000 loan on your rental property.
You use the redraw facility to withdraw $50,000 to renovate your private residence.
You keep claiming interest on the entire $450,000 balance.
This raises an immediate red flag for the ATO. That extra $50,000 is a private expense, so the interest on it is not deductible. To stay compliant, you must apportion your interest claims so they reflect only the investment portion of the loan.
The cleanest way to stay compliant? Keep separate loans for your private and investment activities. If you must use a mixed-purpose loan, you need meticulous records that clearly split the investment portion from the private portion.
Misclassifying Initial Repairs as Immediate Deductions
Another major landmine—especially for first-time landlords—is how you treat initial repairs. When you buy a rental property, any work you do to fix defects, damage, or deterioration that existed at the time of purchase counts as a capital expense, not an immediate repair.
This means you cannot claim the cost of fixing pre-existing issues as an on-the-spot deduction, even if you complete the work after tenants have already moved in. The ATO views these expenses as part of the acquisition cost of your asset. As such, you must treat them as capital works deductions and claim them gradually over many years.
For example, suppose you purchase a property with a failing hot water system and decide to replace it. Because the problem existed at the time of purchase, the cost is treated as a capital improvement, not a repair. It improves the property beyond the condition it was in when you took ownership. The ATO’s guidance here is strict, as outlined in rulings such as Taxation Ruling TR 97/23.
Failing the “Genuinely Available for Rent” Test
To claim tax deductions for rental property, you must prove the property was genuinely available for rent during the time you incurred the expenses. This test often catches out owners of holiday homes, where personal use blurs the line between investment and lifestyle.
Simply listing your property on a rental website doesn’t cut it. The ATO digs deeper for evidence of genuine rental intent and will examine factors such as:
Reasonable Rent: Is the rent set at a realistic market rate? Pricing it too high to discourage tenants won’t pass.
Location and Condition: Is the property presented in a way that would genuinely attract renters?
Reasonable Restrictions: Are you imposing excessive conditions, like banning children in a family-friendly holiday hotspot?
If you fail this test, the ATO can deny your deductions for the period in question. That’s why aligning your rental practices with market expectations is essential to stay compliant.
The Australian Taxation Office (ATO) is ramping up its oversight on rental property claims, driven by an estimated $1 billion tax gap from incorrect landlord reporting. They’re cracking down on common issues like claiming mortgage interest for a family home or incorrectly splitting income between co-owners. Holiday homes are getting special attention, with the ATO cross-checking listings on popular platforms to ensure properties are truly for rent, not just for personal getaways. Discover more insights into the ATO’s crackdown and how to stay compliant.
Actionable Tip: Keep a calendar or detailed log that documents every period of personal use versus every period the property was genuinely being marketed for rent. This paperwork is your best evidence if the ATO ever comes knocking. By actively avoiding these common slip-ups, you can lodge your next tax return with total confidence.
If any of these issues sound uncomfortably familiar, or you just want to make sure your claims are completely audit-proof, getting expert guidance is invaluable. Book a consultation with an EndureGo Tax specialist today to protect your investment and maximise your returns the right way.
Getting the Most Out of Your Depreciation Schedule
Depreciation is hands-down one of the most powerful tax deductions for rental property, yet it’s also the one many investors overlook. Why? Because it’s a non-cash deduction. You don’t physically spend money during the year to claim it. Instead, depreciation accounts for the natural wear and tear on your building and the assets inside it. Think of it as a significant paper loss that reduces your taxable income while improving your investment’s cash flow.
To maximise this deduction, you must understand its two distinct parts. Getting this right is the first step toward lodging an accurate return and unlocking the full benefit.
Capital Works vs. Plant and Equipment
The Australian Taxation Office (ATO) divides depreciation into two main categories:
Capital Works (Division 43): This category covers the building’s fixed structure. We’re talking about the big-ticket items—foundations, walls, roofs, doors, and built-in cupboards. For most residential properties built after 15 September 1987, you can claim construction costs at a rate of 2.5% per year for up to 40 years. It’s a steady, long-term deduction that reflects the building’s gradual decline.
Plant and Equipment (Division 40): This category applies to the removable or mechanical assets inside your property. These items wear out much faster than the building itself. Examples include carpets, blinds, ovens, dishwashers, air conditioners, and hot water systems. The ATO assigns each asset an “effective life,” and you claim deductions over that specific period, which is often shorter than capital works.
ATO data highlights just how much landlords are leaving unclaimed. In the 2016/17 financial year, over two million investors claimed an average of $1,363 each for plant and equipment. Even bigger, capital works deductions averaged $2,385. If you’re not claiming depreciation, you could be missing out on thousands every year.
The Power of a Professional Depreciation Schedule
While you might feel tempted to estimate costs yourself, the smartest move is to hire a qualified quantity surveyor. The ATO officially recognises them as one of the few professionals able to estimate historical construction costs and assess asset values for tax purposes.
A surveyor will inspect your property and prepare a detailed tax depreciation schedule. This report becomes your roadmap for claiming depreciation correctly—and it can guide your deductions for up to 40 years.
Think of a depreciation schedule not as an expense, but as a strategic investment. It’s a fully compliant, audit-proof breakdown of every claimable asset, from the concrete slab to the ceiling fans, ensuring you get back every dollar you’re legally entitled to.
Why You Can’t Afford to Skip This Step
Trying to calculate depreciation yourself is a recipe for disaster. It almost guarantees you’ll miss out on valuable deductions. A quantity surveyor has the expertise to spot and value assets you’d never think of, like wiring, plumbing, and hidden structural elements.
Their report correctly separates capital works from plant and equipment, applying the right rates and effective life to every single item. For a deeper dive into the mechanics, check out our guide on how to calculate depreciation for your assets.
Better yet, the entire fee for the quantity surveyor’s report is 100% tax-deductible in the year you pay for it. This makes the decision a no-brainer. It’s a deductible investment that usually pays for itself many times over in the very first year through bigger tax savings.
Getting a professionally prepared depreciation schedule is the smartest move you can make to ensure your tax deductions for rental property are both maximised and ATO-compliant. It will dramatically boost your investment’s financial performance.
Ready to unlock the full potential of your property’s depreciation? Book a consultation with an EndureGo Tax expert today, and we can connect you with a trusted quantity surveyor.
Your Essential Guide to Keeping ATO-Proof Records
Claiming every possible tax deduction for your rental property is a great goal—but it means nothing if you can’t back it up. The Australian Taxation Office (ATO) is crystal clear: you must keep solid proof for every single expense you claim. Meticulous record-keeping isn’t just smart practice; it’s the foundation of a tax return that can withstand scrutiny.
Think of it this way: if you want to claim it, you need a receipt for it. And it’s not enough to toss faded slips into a shoebox. Instead, you need an organised system that clearly shows what the expense was, how much it cost, who you paid, and the exact date of payment.
What You Absolutely Must Keep
Under Australian tax law, you must hold onto your records for five years from the date you lodge your return. This isn’t optional—it’s a legal requirement designed to make sure you can prove your claims long after the financial year ends.
Here’s a checklist of essential records every landlord should keep:
Proof of Income: Lease agreements and bank statements that show rental payments.
Proof of Expenses: Receipts, invoices, and bank or credit card statements for all property-related costs.
Loan Documents: Bank statements that itemise the interest charged on your investment loan.
Asset Records: Contracts for the property itself and receipts for depreciable assets like ovens, air conditioners, or hot water systems.
How to Make Record-Keeping Painless
The best way to avoid the dreaded tax-time scramble is to track your income and expenses as they happen. A simple spreadsheet works perfectly well, but today’s dedicated apps can make the process almost effortless. By staying organised year-round, you’ll maximise your deductions and minimise stress when it’s time to lodge your return.
To really get your system humming and ensure everything is spot-on for tax purposes, you might want to explore some of the best property management apps on the market. These tools are built to categorise expenses and generate handy reports automatically, saving you a ton of time.
At the end of the day, your goal is to create a clear, simple financial story of your property’s performance. When the ATO can easily connect your claimed expenses to your supporting documents, your tax position becomes rock-solid.
The Final Step: Bringing in a Professional
While this guide gives you the foundational knowledge, applying it perfectly to your specific situation is where a professional can make all the difference. A tax agent who lives and breathes property investment is your best ally for staying compliant and maximising your returns. They’ll ensure every claim is legitimate and every record is in order.
You can learn more about how to stay on top of your rental property tax return obligation with the right professional guidance.
Ready to ensure your records are ATO-proof and your deductions are maximised? Book a consultation with an EndureGo Tax expert today and gain complete peace of mind.
Your Top Questions About Rental Deductions, Answered
When it comes to rental property tax deductions, some questions come up again and again. Getting the right answers is critical—not just for compliance with the ATO, but also to make sure you’re not missing out on legitimate claims.
Can I Claim Travel Expenses to Inspect My Rental Property?
This is one of the biggest questions landlords ask—and the short answer is no for most investors. Since 1 July 2017, the rules have changed. The ATO no longer allows deductions for travel expenses related to inspecting, maintaining, or collecting rent from a residential rental property.
That means you cannot claim:
Car mileage or fuel for driving to your property.
Flights or accommodation for visiting an interstate investment.
The government introduced this rule under the Treasury Laws Amendment (Housing Tax Integrity) Act 2017 to stop the misuse of travel deductions.
The good news? You can still claim 100% of the fees you pay to professionals who do the work for you. Hiring a property manager, real estate agent, or tradesperson to handle inspections or maintenance is a legitimate operational expense.
What Can I Claim If My Rental Property Is Empty?
Yes, you can still claim deductions for your property’s expenses while it’s vacant—but only if it’s genuinely available for rent. The ATO will look closely at whether you’re actively seeking tenants.
To pass the test, you need to:
List the property with a property manager or advertise it on major real estate platforms.
Ensure the rent you’re asking for is realistic and in line with current market rates.
Present the property in a way that would attract genuine tenants.
If you meet these conditions, you can continue claiming deductions for expenses such as interest on your investment loan, council rates, and maintenance costs—even while the property sits empty.
The moment you stop trying to rent it out—say, you decide to move in yourself or take it off the market for renovations—your ability to claim deductions stops. Always keep records of your advertisements as proof it was genuinely available.
Are Fees for Professional Advice Tax Deductible?
Yes, absolutely! This is one of the most valuable—and often overlooked—tax deductions for rental property. In fact, it’s a deduction that can easily pay for itself. Any fees you pay for professional advice that directly relates to managing your investment property or handling its tax affairs are fully deductible.
For example, this includes:
Fees you pay a registered tax agent to prepare and lodge your tax return.
The cost of hiring a quantity surveyor to create a tax depreciation schedule.
Importantly, both of these can be claimed in the same year you pay for them, giving you immediate tax relief.
Why Expert Guidance Matters
Furthermore, investing in expert advice doesn’t just keep you compliant—it’s also a smart financial strategy. With the ATO sharpening its focus on property investors, having professional support helps ensure your claims are accurate, maximised, and defensible.
In other words, specialist knowledge gives you two big advantages: peace of mind and stronger cash flow.
Partner with EndureGo Tax
Maximising your tax deductions for rental property while staying on the right side of the ATO requires more than guesswork—it takes expertise. That’s exactly what we provide at EndureGo Tax. Our team delivers tailored advice for your investment portfolio, making sure you claim every single dollar you’re entitled to.
So, don’t leave money on the table. Book a consultation with EndureGo Tax today and get the clarity, compliance, and confidence you deserve.
