


To maximise your retirement savings, you must master Australia’s annual superannuation contribution limits. Understanding this rulebook is fundamental to building your nest egg effectively and making astute financial decisions.
Currently, the general concessional (before-tax) contribution cap is $27,500 per year. For non-concessional (after-tax) contributions, the cap is $110,000 per year. Adhering to these expert-defined limits is critical for maximising tax benefits and, just as importantly, avoiding financial penalties from the ATO.
Decoding the Core Super Contribution Limits
Think of your super fund as a tax-optimised investment vehicle designed for long-term wealth creation. To ensure fairness, the Australian Taxation Office (ATO) establishes a ceiling on annual contributions.
These ceilings, or contribution caps, are the strategic guardrails that guide you in growing your super in the most tax-effective way possible. Mastering them is the first step in building a powerful retirement strategy. The two primary contribution types are treated distinctly for tax purposes, each with its own limit.
This image clearly illustrates the two main pathways for funding your superannuation.
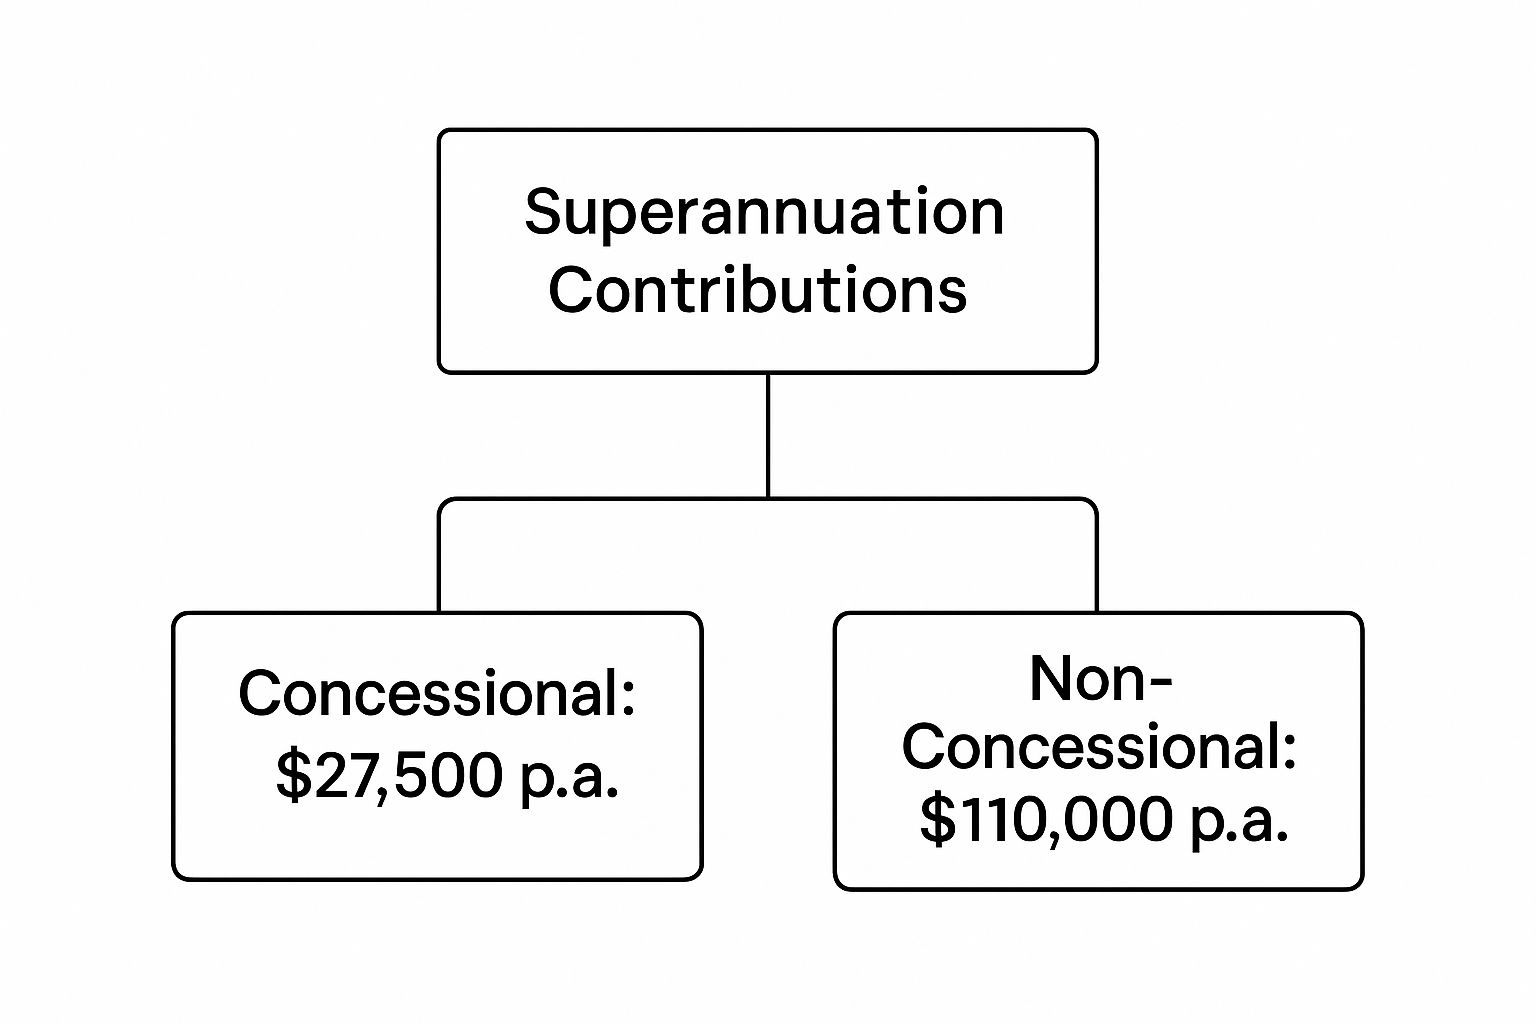
As you can see, it clearly separates the before-tax (concessional) and after-tax (non-concessional) limits, showing the standard annual cap for each, a key element of superannuation planning.
The Two Pillars of Super Contributions
The entire system is built upon two fundamental types of contributions. Each serves a distinct purpose and is governed by its own set of rules and expert-defined caps.
- Concessional Contributions: These are your ‘before-tax’ contributions. This category includes your employer’s compulsory Superannuation Guarantee (SG) payments, any salary sacrifice arrangements, and personal deductible contributions. The strategic advantage is that they are taxed at a flat 15% within your super fund, which is significantly lower than the marginal income tax rate for most professionals. The standard annual cap is $27,500.
- Non-Concessional Contributions: These are your ‘after-tax’ contributions, made from your post-tax income. Because you’ve already paid income tax on these funds, they are not taxed again upon entering your super. The standard annual cap is a substantial $110,000, though eligibility is contingent on your total super balance.
Expert Analysis: Concessional contributions provide an immediate tax arbitrage opportunity, while non-concessional contributions allow for significant capital injection into the tax-advantaged superannuation environment.
For quick reference, here’s a professional table summarising the key limits.
Annual Superannuation Contribution Caps At-a-Glance
| Contribution Type | Standard Annual Cap | Key Conditions |
|---|---|---|
| Concessional (Before-Tax) | $27,500 | Includes employer SG, salary sacrifice, and personal deductible contributions. Taxed at 15% in the fund. |
| Non-Concessional (After-Tax) | $110,000 | From post-tax income. Not taxed on entry. Eligibility depends on your total super balance. |
These caps form the foundation of superannuation planning. However, advanced strategies involving age-based rules and unused cap provisions can add further layers to your financial plan.
The regulations governing super contributions have evolved significantly since the Superannuation Guarantee’s inception in 1992. The system is continuously refined to balance savings incentives with fiscal sustainability. For those interested in broader general financial topics, a wealth of resources is available to deepen your expertise.
Navigating these rules is essential for any individual serious about building wealth for retirement, whether you’re an employee or a business owner in Ashfield or the Northern Beaches. Expert application can profoundly impact your final nest egg.
Understanding Your Concessional Contributions Cap
Consider concessional contributions as a government-endorsed method for tax-efficiently funding your future. Also known as ‘before-tax’ contributions, they are one of the most potent tools for building your retirement wealth. A comprehensive understanding of what constitutes these contributions is non-negotiable for anyone aiming to maximise their superannuation.
The annual concessional contributions cap represents the maximum total of these before-tax contributions you can make each financial year. Exceeding this limit triggers additional tax, making vigilant tracking of all inflows crucial. This is a core competency in managing your superannuation contribution limits effectively.
What Counts Towards the Concessional Cap?
A common misconception is that this cap only applies to voluntary contributions. In reality, several payment types are aggregated into this single bucket, including mandatory employer payments.
Here is a professional breakdown of the three primary sources that contribute to your annual $27,500 concessional cap:
- Employer Superannuation Guarantee (SG): These are the mandatory contributions your employer makes. This amount, a set percentage of your ordinary time earnings, forms the baseline of your annual concessional contributions.
- Salary Sacrifice Arrangements: This is a strategic agreement with your employer to direct a portion of your pre-tax salary into your super fund. It is a highly effective strategy as it simultaneously boosts your retirement savings and lowers your taxable income.
- Personal Deductible Contributions: These are contributions you make from post-tax funds (e.g., from a bank account) and subsequently claim as a tax deduction in your annual return. This achieves the same tax outcome as salary sacrificing but provides greater flexibility.
Ultimately, you are responsible for tracking these cumulative amounts. While your employer manages SG payments, combining a salary sacrifice arrangement with a last-minute personal contribution could inadvertently push you over the limit.
The 15% Tax Advantage Explained
What is the strategic value of this? The primary benefit of concessional contributions lies in their preferential tax treatment. Instead of being taxed at your personal marginal rate, which can be as high as 45% (plus the Medicare levy), these contributions are taxed at a flat 15% upon entering your super fund.
Key Takeaway: For most working Australians, this 15% contributions tax represents a substantial saving. This immediate tax efficiency ensures more of your capital is invested for your retirement, not paid to the tax office.
Let’s analyse a practical example.
Practical Example: Sarah’s Concessional Contributions
Sarah earns $110,000 annually, placing her in the 32.5% marginal tax bracket (plus Medicare levy).
- Employer SG: Her employer contributes $12,100 (11% of her salary) to her super as SG payments. This counts towards her $27,500 concessional cap.
- Salary Sacrifice: To accelerate her savings, Sarah strategically arranges to salary sacrifice an additional $10,000 per year.
- Total Concessional Contributions: Her total for the year is $22,100 ($12,100 + $10,000), which is well within the $27,500 cap.
The entire $22,100 entering her super is taxed at only 15%. Had she received that extra $10,000 as regular income, it would have been taxed at her marginal rate of 32.5%. This expert strategy saves her a significant amount in tax and accelerates the growth of her retirement savings.
This tax-advantaged framework is a cornerstone of Australia’s superannuation system. Staying informed about ongoing superannuation tax changes is vital to ensure you continuously optimise your strategy according to the latest regulations.
Managing your concessional cap is not about guesswork; it requires a deliberate, expert-led plan. It involves knowing your numbers, communicating with your employer, and timing your contributions to remain within the limits.
Actionable Call to Action: Ready to optimise your super contributions? Contact EndureGo for a consultation today and ensure you’re making the most of every dollar.
Maximising Your Non-Concessional Contributions
While concessional contributions offer an immediate tax benefit, non-concessional contributions are the primary vehicle for building substantial wealth within your superannuation. These are contributions made from your ‘after-tax’ income—capital on which you have already paid your marginal tax rate.
As tax has already been paid, these contributions are not taxed again upon entering your super fund. Furthermore, all investment earnings grow within super’s low-tax environment, and the entire balance can typically be withdrawn tax-free upon retirement and meeting a condition of release.
This makes them an exceptional tool for injecting large sums into your retirement savings, particularly following a liquidity event such as an inheritance, a significant bonus, or the sale of an asset. Mastering these contributions is a critical component of controlling your superannuation contribution limits.
The Power of the Bring-Forward Rule
The standard annual cap for non-concessional contributions is $110,000. However, the real strategic advantage lies in the bring-forward arrangement. This powerful provision allows eligible individuals to ‘bring forward’ the next two years’ of caps, enabling a contribution of up to $330,000 in a single financial year.
This is akin to receiving a three-year allowance at once. Instead of contributing $110,000 annually for three years, you can inject a significant lump sum into the tax-advantaged super environment immediately, allowing it to begin compounding much sooner. Eligibility, however, is contingent on your age and your Total Super Balance (TSB).
Who Is Eligible for the Bring-Forward Arrangement?
The Australian Taxation Office (ATO) has implemented strict criteria to ensure this strategy is used correctly.
To trigger the bring-forward rule, you must be under 75 years of age at any point during the financial year. The second, more complex condition is that your TSB on 30 June of the previous financial year must be below the general transfer balance cap.
Crucial Point: Your Total Super Balance on the last day of the preceding financial year is the definitive metric. If it is too high, your capacity to make non-concessional contributions—including using the bring-forward rule—will be restricted or entirely precluded for the current year.
Let’s examine a practical, real-world scenario.
Practical Example: Mark Uses the Bring-Forward Rule
Mark, aged 62, has just sold an investment property and has $300,000 he wishes to contribute to his super. On 30 June of the previous year, his Total Super Balance was $950,000.
- Check Eligibility: Mark is under 75, and his TSB of $950,000 is well below the relevant threshold. This confirms his eligibility to use the bring-forward rule.
- Trigger the Arrangement: By contributing more than the annual $110,000 cap, he automatically triggers the rule. He contributes the full $300,000.
- Future Contributions: This single strategic action utilises his non-concessional cap for the current year and the subsequent two years. He cannot make further non-concessional contributions until this three-year period concludes.
Mark’s astute move puts his $300,000 to work inside super immediately, rather than phasing it in over three years, maximising its compounding potential.
Strategic Planning and Common Pitfalls
Invoking the bring-forward rule requires meticulous planning, not impulsiveness. Once triggered, you are committed to the three-year period. It is vital to consider future cash flow and the possibility of receiving other lump sums you might wish to contribute during that time.
A common pitfall is miscalculating your Total Super Balance or failing to realise that a large contribution now prevents further contributions for the next two years. It’s also critical to note that if your TSB is close to the threshold, you may only be permitted to bring forward one or two years’ worth of caps, not the full three.
Actionable Call to Action: Need help determining if the bring-forward rule is the right strategy for you? Contact EndureGo today to book your consultation. Our expert accountants in Belrose and Ashfield can analyse your situation and build a strategy that aligns with your financial goals.
How to Use Catch-Up Contributions Strategically
Imagine if you could retroactively utilise last year’s unused concessional contribution cap, or even the one from the year before. This is not a hypothetical scenario but a real and powerful strategy available to savvy savers.
The ‘carry-forward’ or ‘catch-up’ contribution rule is one of the most effective yet underutilised provisions in Australia’s superannuation system. It permits you to use any unused portion of your concessional cap from previous years, presenting a golden opportunity to make a substantial, tax-effective contribution in the present. This is an expert-level tactic for maximising your retirement savings, but it is governed by very specific rules.
Are You Eligible for Catch-Up Contributions?
Before planning a significant super top-up, you must meet two critical eligibility criteria. The ATO has established these conditions to ensure the benefit is directed towards those who genuinely need it—individuals who have been unable to consistently maximise their superannuation contribution limits.
Here is the expert checklist to determine your eligibility:
- Your Total Super Balance (TSB): Your TSB must have been less than $500,000 on 30 June of the previous financial year. This is the primary eligibility gatekeeper.
- Unused Concessional Cap: You must have unused concessional cap amounts from one or more of the last five financial years. This rule commenced on 1 July 2018, so eligibility is based on unused caps from the 2018-19 financial year onwards.
If you meet both conditions, you are positioned to contribute more than the standard $27,500 annual concessional cap by utilising your accumulated allowance.
Expert Tip: The $500,000 Total Super Balance threshold is a strict, non-negotiable rule. It is imperative to verify your balance as of 30 June of the last financial year before taking any action. This figure is available on your latest superannuation statement or via myGov.
Calculating Your Available Catch-Up Amount
Calculating your available cap is a matter of simple arithmetic. It requires a review of the last five financial years to determine your remaining capacity.
Here is a simple process to calculate it:
- Identify your concessional contributions for each of the last five financial years (from 2018-19 onwards).
- Subtract this amount from the general concessional cap applicable in that specific year.
- Sum all the unused amounts. This total represents your available catch-up amount.
Let’s See it in Action: How Sarah Calculates Her Catch-Up Cap
Sarah is a freelance graphic designer with a fluctuating income. On 30 June last year, her Total Super Balance was $410,000, confirming her eligibility. After securing a major project, she wants to make a large contribution this year to reduce her tax liability.
Here’s her contribution history:
- FY 2022-23: The cap was $27,500. She contributed $10,000, leaving $17,500 unused.
- FY 2021-22: The cap was $27,500. She contributed $5,000, leaving $22,500 unused.
- FY 2020-21: The cap was $25,000. She contributed $15,000, leaving $10,000 unused.
Sarah’s total unused cap from these three years is $50,000. This financial year, she can contribute her standard $27,500 cap plus her $50,000 in catch-up contributions, for a total tax-deductible contribution of $77,500.
Who Benefits Most from Catch-Up Contributions?
This provision is a game-changer for individuals in specific financial situations. It is particularly advantageous for those who had limited capacity to contribute in the past but now have the cash flow to catch up.
Consider these expert scenarios:
- Individuals with variable incomes: Gig economy workers, contractors, or commission-based salespeople can make substantial contributions during high-income years.
- People returning to the workforce: Anyone who took a career break for family, travel, or study can compensate for years of minimal or no contributions.
- Small business owners: A highly profitable year offers the ideal opportunity to draw funds from the business and make a significant personal deductible contribution, reducing the tax burden for both the company and the individual.
The superannuation system has always aimed to incentivise retirement savings. The concept of a concessional tax rate, introduced on 1 July 1988, paved the way for such intelligent incentives. For those interested, you can explore a detailed history of the regulations shaping modern superannuation.
Actionable Call to Action: Ready to reclaim past opportunities and give your super a strategic boost? The rules can be complex, but the payoff is immense. Contact EndureGo for a consultation today to have our expert accountants calculate your available cap and design the perfect contribution strategy.
Navigating Penalties for Excess Contributions
Accidentally exceeding your superannuation contribution limits can be unsettling, but it is a relatively common administrative error. It is crucial not to panic. The Australian Taxation Office (ATO) has a clear, structured process for rectification, and understanding this process is key to a calm and correct resolution.
Rather than imposing an immediate, harsh penalty, the process begins with a formal notice. After reviewing data from your super fund, the ATO will issue an excess contributions determination if a breach is detected. This is not a fine; it is an official notification that you have exceeded a cap and it outlines your available options.
What Happens if You Breach the Concessional Cap?
When you exceed the concessional (before-tax) contributions cap, the consequences are tax-related. The ATO’s objective is to neutralise the tax advantage you inadvertently received on the excess amount.
Here is the standard process:
- The Determination is Issued: The ATO sends you a letter detailing the precise excess amount.
- Tax Adjustment: The excess amount is added to your assessable income for that financial year and taxed at your personal marginal tax rate.
- A 15% Tax Offset: To ensure fairness, you receive a 15% tax offset. This accounts for the 15% contributions tax your super fund has already paid on that amount.
In effect, you pay the difference between your marginal rate and the 15% super tax rate. An interest charge (the excess concessional contributions charge) may also apply to account for the delayed tax payment.
What Happens if You Breach the Non-Concessional Cap?
The procedure for exceeding the non-concessional (after-tax) cap is different, as this money has already been taxed. If you breach this limit, the ATO provides a critical choice.
Key Decision Point: Upon exceeding the non-concessional cap, you have the option to either release the excess amount from your super or leave it within the fund. This decision has significant tax consequences.
These are your two options:
- Option 1: Release the Excess Amount. You can elect to withdraw the excess non-concessional contributions, plus any associated earnings, from your super. These associated earnings will then be taxed at your marginal tax rate. This is the most common resolution path.
- Option 2: Leave the Excess Amount in Super. If you choose not to release the funds, the entire excess amount is taxed at the highest marginal rate of 47% (including the Medicare levy). This is a severe penalty designed to deter the parking of excess funds in the low-tax super environment.
What to Do When You Get That ATO Notice
Receiving an ATO determination can be stressful, but ignoring it is the worst possible action. A prompt response is critical.
Here are your expert next steps:
- Review the Determination Meticulously: First, verify the figures against your records. Errors can occur, so confirm the amounts and the relevant financial year.
- Make Your Election: You typically have 60 days to respond. You must decide whether to release the excess funds and formalise your choice via myGov or by completing the provided form.
- Pay Any Tax Due: The ATO will subsequently issue an amended notice of assessment, which will detail any additional tax payable.
Understanding these penalties is one part of the equation; preventing them is another. Late employer payments can sometimes be the cause. For a deeper analysis, see our guide on how to avoid superannuation guarantee payment penalties.
Actionable Call to Action: Worried you may have breached your superannuation contribution limits? Our expert accountants in Ashfield and Belrose can review your situation and guide you through the ATO process. Contact EndureGo for professional advice and peace of mind.
Advanced Strategies for SMSFs and Business Owners
For operators of a Self-Managed Super Fund (SMSF) or a small business, the annual superannuation contribution limits transcend mere compliance. They are powerful strategic tools. With this level of financial control, you can align your business, personal tax, and retirement objectives in a uniquely synergistic manner.
This is about advancing beyond simply meeting the caps to strategically leveraging them to manage cash flow, reduce tax liabilities, and accelerate wealth accumulation. Let’s explore the advanced tactics at your disposal.
Leveraging Contributions for Business Profitability
For a small business owner, concessional contributions are a potent tax planning instrument. During a high-profit year, making a large, tax-deductible personal contribution can significantly reduce both corporate and personal tax liabilities.
Practical Example: Imagine your business experiences a record year with high profits. By making a significant personal super contribution and claiming it as a tax deduction, you effectively transfer pre-tax profits from the high-tax corporate environment directly into your low-tax superannuation fund. This is an expert move to optimise your financial outcome.
Strategic Insight: A well-timed, large concessional contribution allows a business owner to smooth their income profile. You can reduce your taxable income in peak years, securing a substantial tax benefit when it is most needed.
This strategy becomes even more powerful when combined with carry-forward provisions. You can utilise several years of unused contribution cap space at once, creating a massive financial lever to pull during a high-profit year or before a major asset sale.
The SMSF Advantage: Contribution Reserving
SMSF trustees can employ a sophisticated strategy known as contribution reserving. This allows a contribution made in one financial year to be allocated to a member’s account in the following financial year.
Here’s the mechanism: A contribution received by the fund on 28 June would typically count towards that financial year’s cap. With contribution reserving, the SMSF can hold these funds in a reserve or ‘suspense account’ and only formally allocate them to the member’s balance in early July—the beginning of the new financial year.
The strategic implications are significant:
- Contribution Stacking: It enables the effective processing of two years’ worth of concessional contributions around the end of the financial year. This can result in a $55,000 tax deduction (2 x $27,500) within a very short period.
- Managing High-Income Events: It is an ideal strategy for mitigating the tax impact of a large capital gain, such as from the sale of a business or an investment property that settles late in the financial year.
This is an advanced manoeuvre with stringent rules. The amount must be allocated to the member’s account within 28 days of the end of the month in which it was received. Errors can lead to severe penalties, making professional advice essential.
Navigating In-Specie Contributions
An in-specie contribution involves transferring an asset—such as listed shares or commercial property—into your SMSF in lieu of cash. When executed correctly, it is a brilliant method for moving valuable assets into the tax-advantaged super environment without triggering a sale.
The regulations, however, are exceptionally strict. The market value of the asset on the transfer date counts towards your contribution caps (either concessional or non-concessional). The ATO scrutinises these transactions to ensure correct asset valuation and compliance with SMSF investment rules. For example, transferring a residential family home into an SMSF is prohibited.
A popular expert strategy for business owners is transferring their business’s commercial property into their SMSF. This allows the business to pay rent directly to the SMSF, creating a tax-deductible expense for the business and tax-efficient income for the super fund—a clear win-win.
Actionable Call to Action: Ready to explore these advanced strategies for your business or SMSF? The rules are complex, but the rewards are significant. Contact EndureGo’s expert accountants in Ashfield and Belrose to build a robust plan that aligns with your goals.
Common Questions About Super Contributions
The rules governing super contributions can be complex. However, mastering the details is the key to making intelligent, confident decisions for your retirement. Here are expert answers to some of the most critical questions we encounter.
What Happens if My Employer Pays My Super Late?
This is a critical issue with a surprising answer. If your employer’s Superannuation Guarantee (SG) contributions for a financial year are deposited into your fund after 30 June, they count towards the contribution cap for the year they were received, not the year they were earned.
Practical Example: An SG payment for the June 2024 quarter that only arrives in your fund in July 2024 will be counted against your 2024-25 concessional cap. This timing issue can easily result in an excess contribution, particularly if you are also making personal contributions. This is a classic pitfall, highlighting the need for vigilant monitoring of your super statements.
To proactively manage this risk, read our guide on how to ensure timely Super Guarantee payments and avoid unexpected issues.
Can I Contribute to Super After Age 67?
Yes, you can. The regulations have become significantly more flexible, removing the ‘work test’ for most voluntary contributions for individuals aged between 67 and 74.
This change allows you to continue making non-concessional (after-tax) and salary-sacrificed contributions until you turn 75, without the need to be employed.
One Important Caveat: The work test remains relevant if you are aged 67 to 74 and wish to claim a personal tax deduction for your contributions. To do so, you must have been gainfully employed for at least 40 hours within a consecutive 30-day period during that financial year.
How Does My Total Super Balance Affect My Contributions?
Your Total Super Balance (TSB) acts as the primary gatekeeper for your contribution strategies. Calculated on 30 June of the previous financial year, this single figure determines your eligibility for various contribution types.
Your TSB is the deciding factor for:
- Non-concessional contributions: If your TSB is at or above the general transfer balance cap, you are precluded from making any further non-concessional contributions for that year.
- The bring-forward rule: Your capacity to use this powerful strategy is directly linked to how far your TSB is below the cap. Greater capacity allows for larger contributions.
- Catch-up concessional contributions: You are only eligible to make these specialised catch-up contributions if your TSB was below $500,000 on the preceding 30 June.
The system is strategically designed to provide greater opportunities for individuals with lower balances to build their retirement wealth.
Are you trying to make sense of your super contribution limits? The team at EndureGo provides expert, tailored advice to help individuals and business owners in Ashfield and the Northern Beaches optimise their retirement strategy. Book your consultation today and get the expert clarity you need.
