


When you’re running the show as a sole trader in Australia, one of the biggest lightbulb moments is realising how tax works. It’s a common point of confusion we see all the time. Unlike a company with its flat tax rate, your business profit isn't separate—it's your personal income.
Getting this right is the foundation of a stress-free tax time and crucial for lodging an accurate sole trader income tax return.
Getting Your Head Around Sole Trader Tax
For tax purposes, the Australian Taxation Office (ATO) sees you and your business as one and the same. This simple fact changes everything about how you prepare and lodge your annual sole trader income tax return.
Essentially, your business profit (that’s your total income minus all your legitimate deductions) gets added to any other income you’ve earned, like from a part-time job or investments. This final figure is your taxable income, and it’s what the ATO uses to calculate your bill.
How Progressive Tax Rates Work for You
Here’s the good news. As a sole trader, you get to take advantage of the personal tax-free threshold, which is $18,200 for the 2025-26 financial year. Companies, on the other hand, pay tax from the very first dollar they earn.
Your income is then taxed in brackets. This is what's known as a progressive system—the more you earn, the higher the rate on the next portion of your income.
Here's a look at the personal income tax brackets for the upcoming financial year.
2025-2026 Sole Trader Taxable Income Brackets
| Taxable Income | Tax on this Income |
|---|---|
| $0 – $18,200 | 0% |
| $18,201 – $45,000 | 16c for each $1 over $18,200 |
| $45,001 – $135,000 | $4,288 plus 30c for each $1 over $45,000 |
| $135,001 – $190,000 | $31,288 plus 37c for each $1 over $135,000 |
| $190,001 and over | $51,638 plus 45c for each $1 over $190,000 |
These rates don't include the Medicare levy, which is usually an additional 2%. It’s crucial to factor this in when you’re planning. You can see the full breakdown on the ATO website under determination TR 2024/D1.
Expert Tip: The biggest mistake we see sole traders make is not putting money aside for tax. Because you're taxed at your personal marginal rate, you need a separate stash of cash ready for when the ATO bill arrives. A good rule of thumb is to set aside 20-30% of every invoice into a separate bank account.
A Practical, Real-World Example
Let's make this real. Say you're a marketing consultant in Sydney, working as a sole trader.
- You billed $110,000 in gross income for the year.
- You racked up $20,000 in legitimate business expenses (think software, insurance, and your home office).
- Your net business profit is $90,000 ($110,000 – $20,000).
That $90,000 is what you’ll be taxed on using the individual rates above. Using the 2025-26 brackets, your tax would be calculated as: $4,288 + ($90,000 – $45,000) * 0.30 = $17,788, plus the Medicare levy. For a more detailed walkthrough, have a look at our guide on how sole traders pay tax.
Understanding this core concept is step one. If you’re unsure how these rules apply to your business, contact us today to ensure your tax planning is spot on.
Building an Audit-Proof Record-Keeping System
A stress-free sole trader income tax return doesn't just happen in June. It’s the result of having an organised, audit-proof record-keeping system all year round. Let’s be honest, we’ve all been tempted by the shoebox method, but a good system is about more than just avoiding a headache—it’s about making sure you can claim every single dollar you’re entitled to.
Here's the most important rule: the Australian Taxation Office (ATO) legally requires you to keep most business records for five years from the date you lodge your tax return. This isn’t a suggestion. Getting this wrong can lead to penalties and make it impossible to prove your claims if the ATO ever comes knocking.
The Essentials for Your Tax Records
A solid system needs to track both sides of your business: the money coming in and the money going out. At a bare minimum, you need to be able to pull up these records on demand.
- Income Records: This means all your sales invoices, payment summaries from clients, and bank statements showing every deposit.
- Expense Records: Keep all supplier invoices and receipts for business purchases. And here's a crucial tip: a line on your bank statement isn't enough. You need the original tax invoice to claim any GST credits.
- End-of-Year Summaries: If you hold inventory, you'll need records of your stocktake. You also need a list of your business debtors (who owes you money) and creditors (who you owe money to).
For many sole traders, using tools like automated invoice processing software can be a game-changer. It helps keep things accurate and can save you countless hours of admin.
The ATO is clear: your records must be in English (or easily translated) and properly explain all your transactions. If you go digital, you must ensure your records are secure and backed up, as outlined in taxation rulings like TR 96/7. This is a legal requirement, not just good practice.
Digital vs Paper Systems
For a busy tradie or consultant who’s always on the move, a digital system just makes sense. Snapping a photo of a receipt with a bookkeeping app means it's instantly captured, so you won’t find it faded and crumpled under your car seat six months later.
Practical Example: A plumber uses an app to photograph a receipt for a new wrench right at the hardware store. The app automatically extracts the date, amount, and GST, and files it. Come tax time, there's no frantic search for faded paper receipts.
Even a simple spreadsheet paired with a cloud storage folder for digital copies is a fantastic start. The most important thing is to be consistent.
Actionable Tip: Don't let your records pile up. Schedule 15 minutes every Friday to scan receipts and update your income and expense tracker. This small habit makes lodging your BAS and final tax return a much smoother process.
Struggling to get your records in order? Let our expert team set up a simple, effective system that gives you complete peace of mind.
Unlocking Every Possible Business Deduction
Deductions are your secret weapon for legally lowering your taxable income. Think of it this way: every dollar you correctly claim as a business expense on your sole trader income tax return is a dollar the tax office can’t touch.
But to claim with confidence, you need to know exactly what the Australian Taxation Office (ATO) allows.
The golden rule is pretty simple: the expense must be directly related to earning your income. If something is for both business and personal use—like your phone or ute—you can only claim the business portion. This is the guiding principle for everything you claim.
Claiming Vehicle Expenses Correctly
For many sole traders, especially tradies, vehicle expenses are one of the biggest deductions available. The ATO gives you two ways to calculate this, and picking the right one can save you thousands.
Cents per Kilometre Method: This is the straightforward option. You can claim 85 cents per kilometre for business-related travel, up to a maximum of 5,000 business kilometres per car. It's easy, but it's an all-inclusive rate—you can't separately claim fuel, insurance, or rego.
Logbook Method: This takes more work upfront but almost always results in a bigger claim if you use your car a lot. You’ll need to keep a detailed logbook for 12 continuous weeks to work out your business-use percentage. You can then claim that percentage of all your car’s running costs, including fuel, insurance, registration, servicing, and even depreciation.
Practical Example: A landscape gardener's logbook shows 70% business use for their ute. Their total car costs for the year (fuel, insurance, rego, repairs, depreciation) were $12,000. They can claim a hefty $8,400 deduction ($12,000 x 70%). If they used the cents per km method, their claim would be capped at $4,250 (5,000km x 85c). The logbook method puts an extra $4,150 in their pocket.
Maximising Your Home Office Deductions
Working from home? You can claim a portion of your household running expenses. Just like with your car, the ATO offers two methods.
Fixed Rate Method: This is a simple, set rate of 67 cents for every hour you work from home. This rate is designed to cover your electricity, gas, internet, and stationery. You can still make separate claims for the business portion of big-ticket items like your laptop or office desk.
Actual Cost Method: This is more involved, as it requires you to calculate the work-related percentage of each specific household bill. You usually do this based on the floor area of your dedicated office space. While it's more complex, it can be a winner if you have a large, dedicated workspace.
Key Takeaway: Be careful here. You generally can't claim rent or mortgage interest as a home office expense. Doing so can trigger Capital Gains Tax (CGT) issues when you eventually sell your home.
Tools, Equipment and Instant Asset Write-Off
The instant asset write-off is a fantastic tax break for sole traders. It lets you immediately claim the full cost of assets like tools, computers, or office furniture. For the 2023–24 financial year, you could write off the full business portion of eligible assets costing less than $20,000.
Our deep-dive on sole trader tax deductions covers this and more if you need extra detail.
To get the most out of these rules, you have to be organised. Learning how to manage business expenses with Excel and AI can make tracking everything much easier and ensures you don’t leave money on the table.
Actionable Tip: Feeling lost in the rules? Book a chat with the team at EndureGo Tax, and we'll make sure you claim every single dollar you're entitled to on your sole trader income tax return.
Using Superannuation to Reduce Your Tax Bill
As a sole trader, your super isn't just some far-off retirement fund—it's one of the sharpest tools you have for legally slicing your tax bill right now. Unlike employees who get super paid for them, you're in the driver's seat. That’s a big responsibility, but it's also a golden opportunity to get strategic with your finances when preparing your sole trader income tax return.
Making personal super contributions is a savvy way to lower your taxable income while you build that nest egg. These contributions are only taxed at a flat rate of 15% inside your super fund, which is almost always a much better deal than your personal income tax rate.
How Personal Super Contributions Work
It's simpler than you might think. You transfer money from your bank account directly into your chosen super fund. These are called personal concessional contributions, and every dollar you put in (up to the cap) comes straight off your taxable income for the year.
For the 2025-2026 financial year, the concessional contributions cap is $30,000. Just remember, this cap includes all concessional contributions, so if you've had a side job where an employer paid super for you, you'll need to account for that.
A Practical Example of Tax Savings
Let's imagine you're a freelance graphic designer pulling in a taxable income of $90,000 for the year. At that income level, you’re paying a marginal tax rate of 30% (plus the Medicare levy) on a large chunk of your earnings.
Now, say you decide to put $20,000 into your super fund before the end of the financial year. That $20,000 is no longer counted as part of your taxable income. Your new taxable income for your sole trader income tax return drops to $70,000.
Here’s the breakdown:
- Tax saved on your personal income: $20,000 x 30% = $6,000
- Tax paid on the contribution inside super: $20,000 x 15% = $3,000
- Your net tax saving for the year: $3,000
You’ve just put an extra $3,000 back in your pocket and added a solid $17,000 to your retirement savings. It's a win-win. To dive deeper into the rules, check out our guide on how much you can contribute to super.
CRITICAL STEP: To make your super contribution tax-deductible, you must lodge a ‘Notice of intent to claim or vary a deduction for personal super contributions’ form with your super fund. You also have to receive an acknowledgement back from them before you lodge your tax return. This process is legislated under Section 290-170 of the Income Tax Assessment Act 1997. So many sole traders miss this, and it’s a costly mistake.
This whole process turns a future planning task into a powerful, immediate tax-saving strategy. If you’re not sure where to start, get in touch with our expert accountants to ensure you nail this crucial step.
Lodging Your Sole Trader Income Tax Return: DIY vs. Tax Agent
You’ve done the hard work—your records are straight, and you’ve figured out your deductions. Now for the final hurdle: lodging your sole trader income tax return.
So, what’s the best way to get it done? You’ve got two main choices: go it alone with the ATO’s myTax portal or bring in an expert like EndureGo Tax to handle it for you. Your decision here can make a big difference to your stress levels and your deadline.
Let’s break down your options.
Going DIY with myTax
The myTax portal is the ATO’s free online tool, and you can get to it through your myGov account. For sole traders with really simple setups—maybe you’re just starting out or have only a handful of expenses—it can be a decent, cost-free choice.
It’s designed to be user-friendly and even pre-fills some information for you, like bank interest or any salary you might have earned from a part-time job.
But here’s the catch: the deadline is strict. If you lodge yourself, your return is due by 31 October. No extensions. Miss it, and you could be looking at late lodgement penalties from the ATO.
The other thing to remember is that you’re flying solo. While the system guides you, the responsibility for getting every detail right—every dollar of income and every deduction—is entirely on you. You need to be confident you haven’t missed anything. Forgetting a step, like correctly notifying your super fund before claiming a deduction, can cause major headaches.
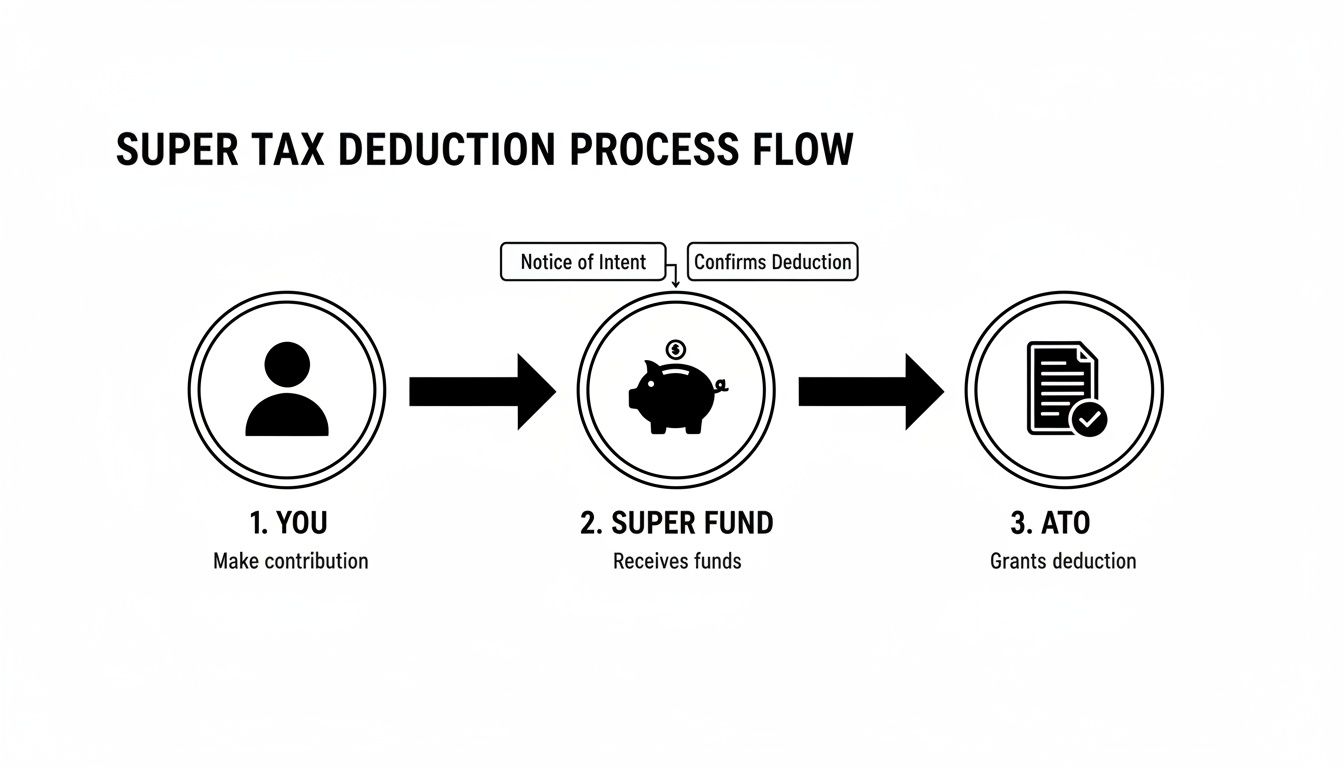
As you can see, claiming your personal super contributions isn’t just a box you tick on your tax return. You need to send a ‘notice of intent’ to your super fund and get confirmation back before you can claim that deduction with the ATO. It's a classic example of where a simple mistake can trip you up.
Partnering with a Registered Tax Agent
Bringing a registered tax agent on board gives you two huge benefits: more time and a lot less stress. A good agent does more than just fill out forms. We look at your whole financial picture to make sure you’re claiming every single deduction you're legally entitled to for your sole trader income tax return.
This is especially crucial for tradies with big tool and vehicle claims, complex businesses, or frankly, anyone who’d rather not have the ATO breathing down their neck.
The biggest perk? A much later deadline. If you’re on a tax agent's books before 31 October, your lodgement deadline can be pushed out—often as late as 15 May the following year. That extra time is a game-changer for busy sole traders.
The proof is in the numbers. ATO data regularly shows that millions of Australians prefer having an expert in their corner. For example, during the 2023 tax time, over 7 million individuals used a tax agent. You can see the latest figures in these ATO tax time lodgement statistics.
So, which path is right for you? Let's put it side-by-side.
Lodgement Options for Sole Traders: myTax vs. Tax Agent
| Feature | myTax (Self-Lodgement) | Registered Tax Agent (e.g., EndureGo Tax) |
|---|---|---|
| Deadline | 31 October (firm) | Up to 15 May of the following year |
| Cost | Free to use the platform | A fee, which is 100% tax-deductible |
| Support | General ATO guidance and online resources | Personalised, expert advice and strategic support |
| Responsibility | 100% on you to ensure accuracy and compliance | Shared responsibility; the agent ensures compliance |
| Time Commitment | You do all the data entry and calculations | Minimal time needed from you; the agent does the work |
| Best For | Very simple businesses, high confidence in tax | Complex businesses, time-poor owners, maximising returns |
Ultimately, while myTax is a solid tool for simple returns, the peace of mind and strategic value an agent provides is often worth the investment. It’s not just about lodging your return; it’s about getting it right and making sure you’re not paying a dollar more in tax than you have to.
Ready to ditch the stress and get an extended deadline for your sole trader income tax return? Book a consultation with EndureGo Tax today and let our experts handle the complexity for you.
Your Top Sole Trader Tax Questions, Answered
Running a business on your own terms is freeing, but let's be real—the tax side of things can be a headache. At EndureGo Tax, we hear the same questions from sole traders every single day. So, let’s clear the air and tackle some of the biggest queries head-on.
Do I Need to Register for GST?
This is the big one. The short answer is: you only have to register for GST if your annual business turnover hits $75,000 or more. If you’re earning less than that, registering is your call.
The main exception? If you're in the taxi or rideshare game (e.g., Uber), you must register for GST from the first dollar you earn.
Practical Tip: Voluntarily registering for GST before you hit the threshold can be a smart move if you have high business setup costs. It means you can claim back the GST on those big purchases, which can provide a significant cash flow boost.
What Happens if I Muck Up My Tax Return?
Mistakes happen. The ATO gets that. If you lodge your return and then realise you've made an error, the best thing you can do is fix it straight away. You can request an amendment through your myGov account or ask your tax agent to sort it out for you.
Getting on the front foot usually means penalties are reduced or even waived. The real trouble starts if the ATO finds the mistake before you do. That’s when penalties are almost a certainty. This is exactly where having an expert in your corner provides a critical safety net—we spot the red flags before your return ever goes to the ATO.
The ATO's own guidelines, such as Practice Statement PS LA 2011/19, make it clear that voluntarily disclosing an error before an audit can massively reduce penalties. It literally pays to be upfront.
How Do I Claim My Car Expenses?
For most sole traders, especially tradies, the ute or van is one of their biggest expenses. You’ve got two methods to choose from, and picking the right one can make a huge difference to your refund.
Cents per Kilometre Method: This is the no-fuss option. You can claim a set rate for every business-related kilometre you drive, but you’re capped at a maximum of 5,000 kilometres per year. It's simple, but because the rate is all-inclusive, you can't claim fuel, insurance, or rego on top.
Logbook Method: This takes a bit more work but almost always results in a bigger claim. You need to keep a detailed logbook for 12 weeks straight to work out your business-use percentage. Once you have that magic number, you can claim that percentage of all your car running costs—fuel, insurance, rego, repairs, and even the depreciation of the vehicle itself.
Actionable Tip: Don't just guess. For one month, track both your kilometres and your total car running costs. An accountant can then quickly crunch the numbers and show you which method will leave more cash in your pocket for the entire year.
When Should I Get an Accountant?
Sure, you can lodge your own sole trader income tax return using myTax. But hiring a professional often pays for itself, not just in tax saved but in time and stress. It’s probably time to call in an expert when:
- You're just getting started: We’ll help you set up your books and record-keeping systems properly from day one, saving you massive headaches later.
- Your income is growing: The more you earn, the more complex your tax situation becomes, and the more valuable strategic tax planning is.
- You're thinking of hiring staff: Taking on employees opens up a whole new world of PAYG withholding and superannuation obligations.
- You just want peace of mind: An accountant ensures you’ve claimed every single dollar you're legally entitled to and gives you a buffer against audits. It lets you get back to what you do best—running your business.
Trying to navigate your sole trader tax obligations can feel like you’re doing it all alone, but you don't have to. The team at EndureGo Tax is here to give you expert guidance, ensuring you stay compliant, organised, and get the best possible tax outcome. Book a consultation with us today and feel the relief that comes with having a trusted local accountant on your side.
