


Look, nobody plans to lodge their tax return late, but life happens. The key is not to panic. Instead, as tax experts, we advise understanding precisely what you're facing with the Australian Taxation Office (ATO) and developing a clear strategy to handle it. The primary penalty you'll encounter is the Failure to Lodge (FTL) penalty, a statutory fee the ATO imposes for every 28-day period your return is overdue.
Understanding how these late tax return penalties work is the first critical step to regaining control and minimising the financial impact.
What Are Late Tax Return Penalties, Really?
Facing an overdue tax return can feel overwhelming, but the ATO's penalty framework is more systematic than it seems. At its core, it’s a legislative mechanism designed to ensure timely compliance from all taxpayers—individuals, sole traders, and companies alike.
The cornerstone is the Failure to Lodge (FTL) penalty. This is not a percentage of tax owed; it is a fixed fine for missing a statutory deadline. This penalty is calculated using "penalty units," the government's standard measure for civil penalties, as outlined in the Taxation Administration Act 1953.
For a practical example, an individual lodging their own return who misses the standard 31st of October tax deadline triggers an FTL penalty. This is calculated at $330 for every 28 days (or part thereof) that the return is late, accumulating to a maximum of five penalty units, which totals $1,650.
Crucially, this applies even if you are expecting a tax refund. The penalty is for the act of lodging late, not for owing tax.
Who Gets Hit With These Penalties?
These penalties are not limited to individuals. The legislation applies broadly to any entity with a statutory obligation to lodge a return or statement with the ATO. This includes:
- Individuals and Sole Traders who miss their personal income tax return deadline.
- Companies and Trusts that do not lodge their annual returns on time.
- Businesses registered for GST that are late with their Business Activity Statements (BAS).
Don't Forget the General Interest Charge (GIC)
In addition to the FTL penalty, if you have a tax liability, the ATO will apply a General Interest Charge (GIC). This is an interest charge, calculated daily and compounded on any unpaid tax amount. It is designed to compensate the government for the delayed receipt of revenue.
Here's the key distinction: the FTL penalty is for lodging late, while the GIC is for paying late. They can be applied concurrently, significantly increasing the financial consequences of non-compliance.
What Are the Main Types of ATO Penalties?
When you lodge a tax return late, the initial fine is often just the beginning. The Australian Taxation Office (ATO) employs several penalty types to enforce compliance. Understanding these is crucial, as they can compound rapidly, transforming a minor oversight into a significant financial liability.
Think of it as an overdue debt accumulating different types of fees. Each serves a distinct legislative purpose, and differentiating between them is the first step toward resolution.
Failure to Lodge (FTL) Penalty
This is the most common penalty. The Failure to Lodge (FTL) penalty is a straightforward fine the ATO issues when you fail to submit a tax return, Business Activity Statement (BAS), or another required form by its due date.
It functions as an administrative sanction for tardiness. It is entirely independent of your tax liability—in fact, you can receive an FTL penalty even if the ATO owes you a refund. The sole trigger is missing the lodgement deadline.
For small businesses and individuals, this penalty is calculated in "penalty units" for every 28-day period the document is overdue, capped at five units. It is the ATO's primary tool for enforcing statutory deadlines.
General Interest Charge (GIC)
While the FTL penalty targets late lodgement, the General Interest Charge (GIC) addresses late payment. If you have an outstanding tax debt, the ATO will apply GIC to the amount owed.
Functionally, it is daily compounding interest, similar to that on a credit card but at a rate set by law. It commences the day after your payment was due and continues to accrue until the debt is settled in full. The GIC rate is typically well above commercial lending rates, making it an expensive form of credit.
Expert Takeaway: An FTL penalty can be imposed without a tax debt, but GIC only applies to unpaid tax liabilities. The most challenging scenario is when you are liable for both—a consequence of lodging late and paying late.
Administrative Penalties
This third category operates differently. Administrative penalties are not for lateness but for inaccuracy. The ATO applies these when you make a false or misleading statement in your tax return that results in a tax shortfall.
These penalties arise from:
- Failure to take reasonable care in preparing your return.
- Recklessness regarding the accuracy of claims or reported income.
- Intentional disregard of tax law.
The penalty is calculated as a percentage of the tax shortfall, and the rate increases based on the severity of the behaviour. A simple error may attract a 25% penalty on the shortfall, whereas intentional disregard can escalate this to 75%. As specified in the Taxation Administration Act 1953, the burden of proof for taking reasonable care rests with the taxpayer.
These three penalties—FTL for lodging late, GIC for paying late, and administrative penalties for inaccuracies—form the foundation of the ATO’s compliance framework. If you've missed a deadline, do not just focus on the initial fine. You require a clear strategy to address any tax debt before GIC escalates.
Feeling overwhelmed? The rules can be complex. Take action now: Contact EndureGo Tax in Ashfield or Belrose Northern Beaches. Our expert accountants will clarify your position and help you develop a strategic plan to achieve compliance.
How ATO Penalties Are Calculated in the Real World
Knowing that late tax return penalties exist is one thing; witnessing their rapid accumulation in a practical scenario is another. The Australian Taxation Office (ATO) uses a prescribed formula, not arbitrary figures. Understanding this calculation provides a clear view of the financial consequences of lodging late.
The calculation depends on two key factors: the number of days a return or statement is overdue and the size of the entity. For individuals and small businesses, the base penalty is one penalty unit (currently $330) for each 28-day period (or part thereof) a document is late. This is capped at five penalty units, or $1,650.
However, for larger businesses, this base penalty is multiplied, making the financial impact far more severe. Let’s examine some practical examples.
Example 1: The Sole Trader Tradesperson
Consider Chris, a self-employed electrician. A demanding year caused his income tax return, due on 31 October, to be overlooked. He eventually lodges it on 15 January.
Here is the professional calculation of Chris’s Failure to Lodge (FTL) penalty:
- Determine the overdue period: Chris is 76 days late (16 days in Nov + 31 in Dec + 15 in Jan).
- Calculate 28-day blocks: 76 days ÷ 28 = 2.71 blocks.
- Round up to the next full block: The penalty applies to any part of a 28-day block, so 2.71 is rounded up to 3.
- Apply the penalty unit value: 3 penalty units × $330 per unit = a $990 penalty.
As a sole trader, Chris is classified by the ATO as a small entity, so no multipliers apply. His penalty is a direct calculation of the overdue period.
Example 2: The Small Company and a Late BAS
Now, examine "Bright Spark Electrical Pty Ltd," a small company. They missed their quarterly Business Activity Statement (BAS) deadline of 28 April and lodged it 60 days late.
The FTL penalty calculation is similar:
- The overdue period: The BAS is 60 days late.
- Calculate 28-day blocks: 60 days ÷ 28 days = 2.14 blocks.
- Round up to the next full block: We round 2.14 up to 3 penalty units.
- Apply the penalty unit value: 3 penalty units × $330 = $990.
This is straightforward. But what if Bright Spark Electrical were a larger enterprise? This is where penalty multipliers, detailed in legislation like the Taxation Administration Act 1953, become a critical factor.
How Entity Size Magnifies Penalties
The ATO escalates FTL penalties for medium and large businesses to reflect their greater tax obligations, creating a powerful incentive for timely compliance.
The size of your business directly impacts the severity of late lodgement penalties. A manageable fine for a small entity can become a substantial financial burden for a medium or large company due to these multipliers.
To understand this, it is essential to know how the ATO defines entity sizes and applies these multipliers.
FTL Penalty Multipliers by Entity Size
This table illustrates how the base penalty rate increases based on entity size—a critical factor for businesses.
| Entity Size Category | Definition | Penalty Multiplier |
|---|---|---|
| Small Entity | Individuals or entities with assessable income or turnover under $1 million. | x 1 (Base Rate) |
| Medium Entity | Turnover between $1 million and $20 million. | x 2 |
| Large Entity | Turnover of $20 million or more. | x 5 |
As shown, penalties scale significantly, making on-time lodgement a high priority for growing companies.
Example 3: The Investor with a Capital Gain and Unpaid Tax
Finally, consider Sarah, an investor who realised a significant capital gain from selling shares. She lodged her tax return 120 days late, resulting in a tax liability of $25,000.
Sarah now faces two distinct penalties:
The FTL Penalty:
- 120 days ÷ 28 = 4.28 blocks, which is rounded up to the maximum of 5 penalty units.
- 5 units × $330 = $1,650.
The General Interest Charge (GIC):
- This is the more costly penalty. GIC is applied to her $25,000 unpaid tax liability, calculated daily and compounded.
- Assuming an annual GIC rate of 11.5%, the daily rate is approximately 0.0315%.
- For 120 days, the GIC would be approximately $945 ($25,000 × 0.0315% × 120 days). Note this is a simplified calculation; the ATO's formula is more precise.
Sarah's total cost for being late is the FTL penalty plus the GIC, amounting to approximately $2,595. You can learn more about how the General Interest Charge works in our detailed article.
These real-world calculations demonstrate how rapidly late tax return penalties can accumulate. If you've missed a deadline, inaction is the most costly response. The most effective course of action is to contact the team at EndureGo Tax in Ashfield or Belrose Northern Beaches immediately. We can help you lodge outstanding returns and devise the best strategy to minimise these penalties.
What Makes the ATO Take Notice? Common Penalty Triggers
The Australian Taxation Office (ATO) does not issue penalties arbitrarily. They are typically triggered by a pattern of behaviour or a history of non-compliance. Think of it like demerit points on a driver's licence – a single minor infringement might result in a warning, but repeated offences will trigger enforcement action.
Many assume penalties are reserved for major, deliberate errors. However, a series of consistent delays can be viewed just as seriously by the ATO. Understanding what raises a red flag is the first step to maintaining a clean compliance record and avoiding the stress of late tax return penalties.
A History of Late Lodgements
This is the most significant trigger. If you consistently miss deadlines for tax returns, Business Activity Statements (BAS), or other reports, you are establishing a negative compliance history. The ATO's systems are designed to detect these patterns.
For example, a cafe owner who is persistently one or two weeks late with their quarterly BAS may consider it a minor issue. To the ATO, however, it represents a clear pattern of non-compliance. A first-time offence for a taxpayer with an otherwise impeccable record may be overlooked. But once a history of lateness is established, the ATO is far less likely to exercise discretion and will begin applying Failure to Lodge (FTL) penalties automatically.
The logic is simple: chronic lateness demonstrates a disregard for tax obligations, and a penalty is the prescribed measure to encourage future compliance.
Ignoring ATO Communication
Another action guaranteed to escalate matters is failing to respond to ATO communications. When the ATO sends a reminder notice, letter, or email about an overdue lodgement, they expect a response. Ignoring these communications is a significant red flag.
Consider a freelance graphic designer who is behind on their income tax return. They see reminder emails accumulate but continue to procrastinate. By neither lodging nor contacting the ATO to explain their circumstances, they have escalated a simple delay into a serious compliance issue.
This lack of engagement signals to the ATO that you are not taking your obligations seriously, prompting firmer action. This could include issuing a default assessment based on available information and applying maximum FTL penalties. A single phone call can often lead to a far more favourable outcome.
The flowchart below illustrates how the ATO scales penalties for businesses. It is not a uniform approach; the larger your business, the greater the penalty.
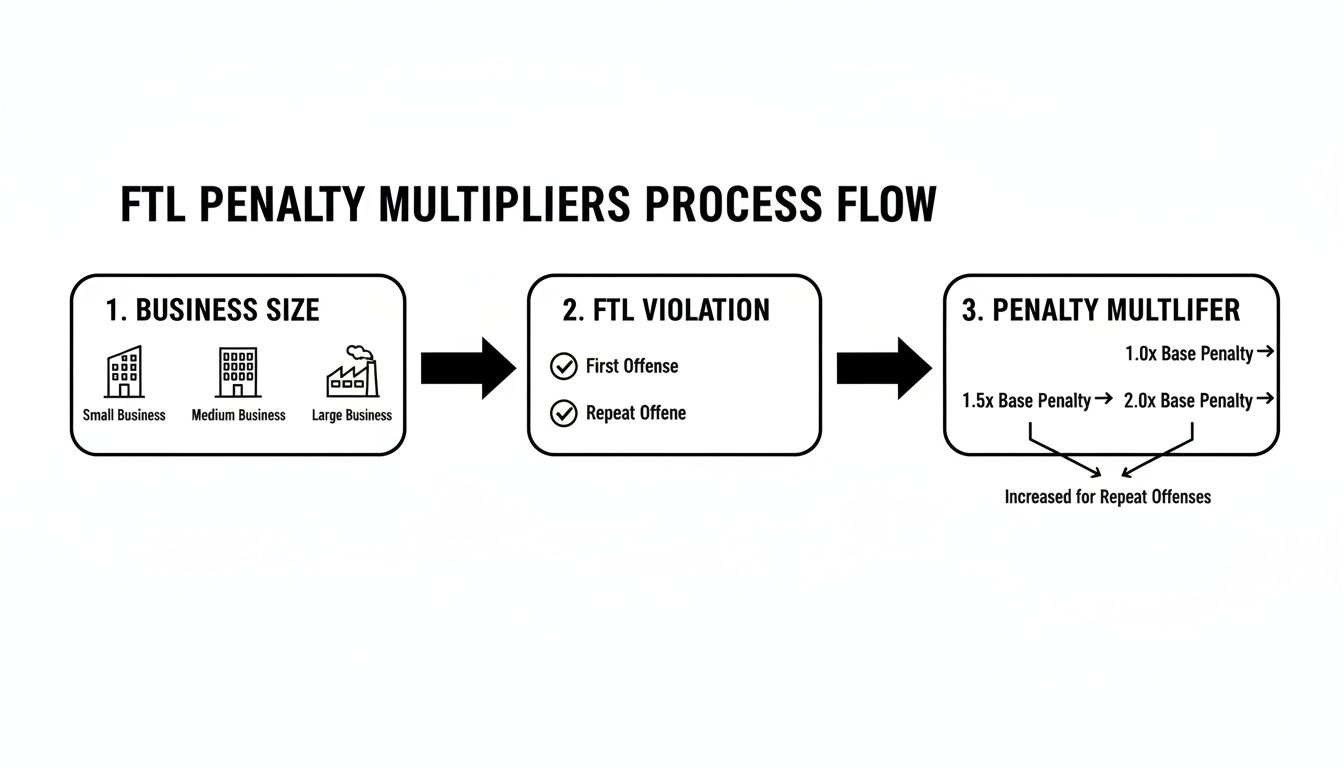
As shown, the base penalty unit applies to small entities, but this is multiplied for medium and large businesses, significantly increasing the financial impact of late lodgement.
High-Risk Behaviours and Industries
Certain industries and taxpayer behaviours are subject to closer scrutiny by the ATO. If you fall into one of these categories, maintaining exemplary lodgement discipline is even more critical.
High-risk indicators include:
- Operating in Cash-Intensive Industries: Businesses such as cafes, construction, or personal services (e.g., hairdressing) are monitored more closely due to the perceived risk of under-reported cash income.
- Making Repeated Errors: If you frequently need to amend returns due to significant errors, this can trigger an audit and place your entire lodgement history under review.
- Large or Unusual Claims: Claiming deductions that appear disproportionately high for your industry or income level is a classic audit trigger. When the ATO investigates your claims, they will also review your lodgement history.
Under the Taxation Administration Act 1953, the ATO possesses extensive powers to enforce tax laws. Your best defence is a proactive offence: lodge accurately and on time, every time.
If your lodgement history is suboptimal or you are struggling with compliance, do not wait for a penalty notice. Take immediate action: Book a consultation with EndureGo Tax at our Ashfield or Belrose Northern Beaches offices. We will help you restore your compliance status and build a positive history with the ATO.
How to Get ATO Penalties Reduced or Waived
Receiving a penalty notice from the Australian Taxation Office (ATO) can be disheartening, but it is not necessarily the final word.
A crucial point many taxpayers overlook is that the ATO has a formal process for considering a penalty remission. This means they have the legislative power to reduce or cancel your penalty entirely. This is not about exploiting a loophole; it is a mechanism that acknowledges that extenuating circumstances can genuinely prevent compliance.
Understanding your rights and how to professionally present your case is paramount. The objective is to demonstrate to the ATO that you had a legitimate reason for the delay and, equally importantly, that you are now taking corrective action.
Grounds for a Penalty Remission
The ATO will not waive a penalty for simple oversight or being busy. The reasons must be serious and genuinely outside your control. Official guidance, such as the ATO’s Practice Statement Law Administration PS LA 2011/19, states remission is considered where it is "fair and reasonable". This aligns with the principle of "reasonable cause" found in other tax jurisdictions, where taxpayers can request penalty abatement based on reasonable cause.
So, what constitutes a legitimate reason? Commonly accepted grounds include:
- Natural Disasters: Events like floods, bushfires, or major storms that physically prevented access to records or lodgement.
- Serious Illness or Accident: A significant personal illness, injury, or a severe mental health condition that incapacitated you or a close family member from managing tax affairs.
- Death of a Key Person: The loss of a close family member or an essential person in your business (like your bookkeeper) responsible for lodgements.
- Unforeseen Events: Other serious, unexpected situations, such as being a victim of crime or a verifiable postal service delay not attributable to your actions.
It is absolutely vital to have credible evidence to substantiate your claim. This may include medical certificates, insurance claims, death certificates, or official disaster relief statements. An unsubstantiated claim will not succeed.
The Two Most Important Steps Before You Ask
Before submitting a remission request, the ATO will verify two critical preconditions. Fulfilling these demonstrates good faith and significantly increases your chances of a successful outcome.
Your compliance history is one of the most powerful tools you have. The ATO is far more likely to show leniency to someone who has a strong track record of lodging and paying on time but has been affected by a one-off event.
First, lodge all outstanding returns. You cannot request a waiver for a penalty on a tax return that remains unfiled. This is a non-negotiable prerequisite. If this task seems daunting, our guide on what to do when you haven't lodged a tax return for years provides a structured starting point.
Second, pay the underlying tax debt if possible. You are requesting remission of the penalty, not the tax itself. Paying the principal tax debt demonstrates your commitment to your obligations. If you cannot pay the full amount, contact the ATO immediately to establish a payment plan.
How to Prepare and Submit Your Remission Request
Once all outstanding documents are lodged, you can formally request the remission. This is typically done through your tax agent, via ATO Online services, or by writing directly to the ATO.
A strong, compelling request should include:
- A Clear Statement: Specify which penalties you are requesting remission for, including the dollar amounts and relevant financial years.
- A Detailed Timeline: Clearly explain the extenuating circumstances, providing specific dates. For instance, "I was hospitalised from 15 September to 20 October, which prevented me from finalising my BAS due on 28 October."
- Supporting Evidence: This is the most critical element. Attach copies of all relevant documents that prove your case.
- Acknowledgement of Obligations: Conclude by briefly stating that you understand your tax duties and have taken all necessary steps to become compliant.
Presenting a well-supported, respectful, and honest case is your best strategy for getting late tax return penalties reduced or cancelled.
If you are facing a penalty notice, do not navigate this process alone. Your next step is to contact the expert team at EndureGo Tax in Ashfield or Belrose Northern Beaches. We can assess your situation, construct a compelling remission request, and manage all communications with the ATO on your behalf.
Your Step-by-Step Action Plan for a Late Return
The realisation that your tax return is overdue is stressful, but allowing it to remain outstanding is the most financially damaging mistake you can make. The key is to shift from anxiety to action with a clear, methodical plan.
Follow these expert-approved steps to resolve your late lodgement and minimise the financial impact of any penalties.
First, do not panic. Begin by systematically collating all necessary documents. This includes gathering your income statements, details of bank interest, dividend statements, and receipts for all work-related expenses you intend to claim. Organisation is the first victory on the path to a swift resolution.
Lodge Immediately to Stop the Clock
The single most critical action you can take right now is to lodge the outstanding return. The Failure to Lodge (FTL) penalty accrues in 28-day blocks, so every day of delay increases the risk of tipping into a new penalty period.
Lodging immediately halts the accrual of further penalties.
Once lodged, you will have a clear understanding of your tax position: whether you have a tax liability, are due a refund, or have a nil balance. This clarity is essential, as it determines your next steps and whether the General Interest Charge (GIC) will begin to accrue on a tax debt.
Communicate and Ask for a Remission
With the return officially lodged, your next move is to communicate with the ATO. If you had a valid reason for the delay—such as a serious illness, family crisis, or natural disaster—you can request a penalty remission.
As detailed in ATO guidelines like Practice Statement Law Administration PS LA 2011/19, they have the authority to waive penalties if circumstances beyond your control prevented timely lodgement. For a deeper dive into managing late filings, this complete guide for unfiled tax returns to avoid penalties offers valuable insights.
From a professional standpoint, the most effective strategy is to engage a registered tax agent. An expert can manage the entire process for you—from preparing and lodging the return to liaising with the ATO and constructing a robust case for penalty remission.
This process can be a significant burden, but you do not have to handle it alone. Take action: contact EndureGo Tax today. Our experienced accountants in Ashfield and Belrose Northern Beaches will take charge, ensuring everything is handled correctly to secure the best possible outcome and restore your peace of mind.
A Few Common Questions We Get About Late Tax Penalties
We understand that dealing with the Australian Taxation Office (ATO) can be complex, especially concerning penalties. To provide clarity, here are expert answers to the most frequent questions we receive.
Will I Get Fined if the ATO Actually Owes Me a Refund?
Yes, you can be fined. This is a common and costly misunderstanding. It is incorrect to assume you are exempt from penalties simply because you are due a refund.
The Failure to Lodge (FTL) penalty is imposed for missing the statutory deadline, not for owing tax. Your obligation to file on time is entirely separate from your final tax position. Therefore, even if a significant refund is awaiting you, the ATO can still impose an FTL penalty of $330 for every 28-day period your return is overdue, up to the $1,650 maximum.
What Exactly Is a “Penalty Unit”?
A "penalty unit" is a standard measure for fines used across Australian government legislation. Instead of specifying fixed dollar amounts in laws (which would quickly become outdated), the legislation refers to a number of penalty units.
The government periodically reviews and adjusts the value of a penalty unit to account for inflation. Currently, one penalty unit is valued at $330. The Failure to Lodge penalty calculation is based on this figure, as prescribed in the Taxation Administration Act 1953.
Can I Pay My Penalties Off in Instalments?
Absolutely. If you receive a penalty notice and cannot pay the full amount immediately, the worst course of action is to ignore it. You or your tax agent should contact the ATO promptly to discuss establishing a payment plan.
Allowing the debt to remain unpaid will cause the General Interest Charge (GIC) to continue accruing, compounding the financial problem.
Proactively arranging a payment plan demonstrates to the ATO that you are taking your obligations seriously. This act of good faith can be highly beneficial if you later request a remission or waiver of the penalty.
Navigating late lodgements and ATO penalties is a stressful experience, but professional assistance can make all the difference. The expert team at EndureGo Tax is here to help you resolve outstanding returns, manage all communications with the ATO, and work towards the most favourable outcome for your situation.
For professional support and peace of mind in Ashfield or Belrose Northern Beaches, contact us today.
Take the first step to resolving your tax issues. Book your consultation with EndureGo Tax now.
