


Ever wondered how to lower your taxable income in Australia? It’s a question our expert accountants field constantly, from tradespeople in Ashfield to business owners on the Northern Beaches.
Let’s be clear: this isn’t about exploiting dodgy loopholes. It’s about strategically and legally utilising the Australian tax system as it was designed. The key is proactive planning—not a last-minute scramble in June. By maximising deductions, making astute superannuation contributions, and implementing the correct investment and business structures, you can legally retain more of your hard-earned money.
Your Expert Guide to Legally Lowering Taxable Income
Understanding how to lower your taxable income is one of the most powerful financial moves you can make. It’s a universal goal, whether you’re a PAYG employee, a sole trader, or a director of a company.
Effective tax planning is a year-round discipline, not an end-of-financial-year panic. It requires a holistic view of your financial landscape: your income streams, legitimate expenses, investment portfolio, and long-term goals. By aligning these elements with Australian tax law, you can achieve significant reductions in your tax liability. Some professionals even leverage sophisticated tools for AI-powered financial analysis to uncover hidden opportunities within their financial data.
Key Strategies for Reducing Your Taxable Income
Here is a professional snapshot of the core methods we'll dissect, identifying who they are best suited for and their potential impact on your tax position.
| Strategy | Best Suited For | Primary Benefit |
|---|---|---|
| Maximising Deductions | All taxpayers, especially employees and sole traders. | Reduces your total assessable income by claiming legitimate work-related and business costs. |
| Superannuation Contributions | Anyone looking to boost retirement savings while securing an immediate tax break. | Pre-tax contributions are taxed at a lower concessional rate (15%) instead of your marginal rate. |
| Salary Sacrificing | Employees with accommodating employers. | Structures your remuneration to include benefits that are taxed concessionally or are exempt from tax. |
| Investment Strategies | Property and share market investors. | Uses mechanisms like negative gearing to offset investment losses against other taxable income. |
| Business/Trust Structuring | Small business owners and those with complex investments. | Allows for tax-effective income distribution, asset protection, and access to lower tax rates. |
These strategies are not secrets; they are established, ATO-compliant methods designed for astute taxpayers. This decision tree provides a clear visual of how different strategies apply based on your specific circumstances as an employee, investor, or business owner.
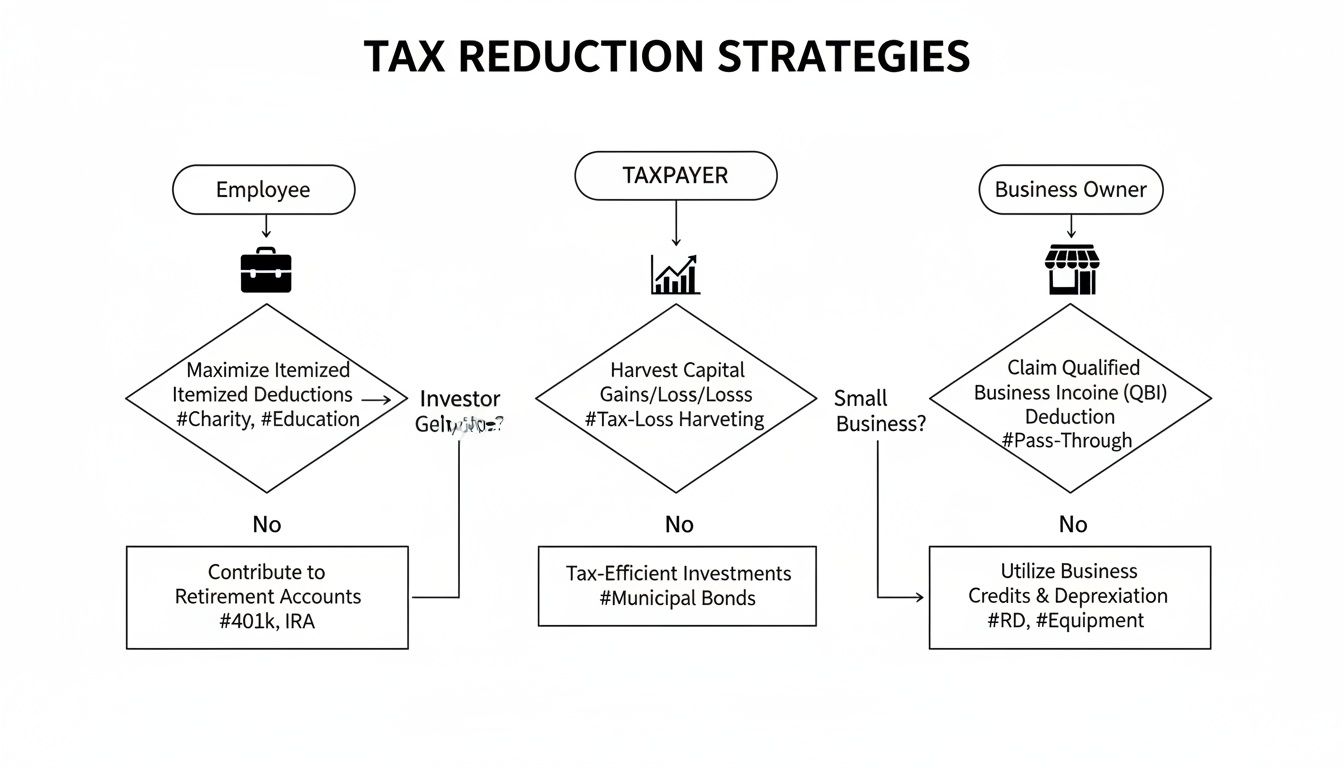
As illustrated, the optimal path forward depends directly on your income sources and financial activities.
Recent Changes That Could Affect Your Tax
Staying abreast of legislative changes is crucial for effective tax planning. A significant recent development was the Stage 3 tax cuts. Commencing 1 July 2024, these reforms fundamentally restructured personal income tax thresholds.
The government lowered the lowest marginal tax rate from 19% to 16% for income between $18,201 and $45,000. This adjustment provides tangible benefits, particularly for the low and middle-income earners who are the backbone of our local economies.
Expert Takeaway: Proactive tax planning is not a one-off task but an ongoing financial discipline. The objective is to make intelligent, compliant decisions that align with your financial goals and the latest tax legislation.
Navigating these strategies requires a firm grasp of the rules set by the Australian Taxation Office (ATO). In this guide, our role is to demystify these options, providing actionable steps to optimise your tax position.
Ready to take control? The foundational first step is identifying your largest opportunities. Let’s begin with the most fundamental strategy of all: maximising your deductions.
Uncovering Every Possible Tax Deduction
Maximising deductions is the cornerstone of any effective strategy for how to lower taxable income. This process goes beyond claiming obvious expenses; it involves a meticulous examination of all potential claims. A surprising number of taxpayers leave significant money on the table by overlooking less common—but perfectly legitimate—deductions permitted by the Australian Taxation Office (ATO).
Consider this practical example: for a plumber in Ashfield, the choice between the cents-per-kilometre method and the logbook method for their work ute can result in a vast difference in their tax outcome. While the former is simpler, a detailed logbook meticulously recording 100% of work-related travel, fuel, insurance, and maintenance almost invariably yields a substantially larger deduction. The additional effort directly translates to a greater tax saving.
The same principle applies to a professional working from their home office. Claiming a portion of internet and electricity bills is merely the starting point. A proper understanding of the criteria for a genuine home office can unlock more substantial claims on occupancy expenses, significantly reducing your taxable income.
Work-From-Home Deductions Beyond the Basics
With remote work now standard practice, many taxpayers are not claiming their full entitlements. The ATO provides clear guidelines; the expertise lies in applying them correctly to your unique situation.
Work-from-home costs are generally categorised into two types:
- Running Expenses: These are costs incurred from the use of your home for work, such as electricity for heating and cooling, phone and internet bills, and the depreciation of office furniture like your desk and chair.
- Occupancy Expenses: While less common for employees, these can be significant for some sole traders. This category allows you to claim a portion of your rent, mortgage interest, or council rates. It is critical to be aware, however, that claiming these can have Capital Gains Tax (CGT) implications when you eventually sell your home.
The golden rule for all deductions is meticulous record-keeping. A simple diary of hours worked from home or segregated receipts for office supplies ensures every claim is substantiated and audit-proof.
Here is a snapshot of the ATO's general guidance on work-related expenses.
This image from the ATO website reinforces the core principle: every deduction must be directly linked to earning your assessable income.
Commonly Overlooked Deduction Categories
Beyond the home office, numerous other areas present opportunities for deductions that are frequently missed. A critical review of your day-to-day work activities can reveal these valuable claims.
A classic example is self-education expenses. If you undertook a course or training directly related to your current employment, the costs are generally deductible. For instance, if an IT consultant completes a certification in a new cloud computing platform, the course fees, textbooks, and related travel are deductible. The crucial test, as outlined in Taxation Ruling TR 98/9, is that the study must maintain or improve the specific skills required for your current role.
Another often-forgotten deduction is income protection insurance. If you hold a policy outside of your superannuation fund, the premiums are typically tax-deductible. This offers a dual benefit: protecting your income stream while simultaneously lowering your annual tax bill.
Expert Tip: Do not dismiss minor expenses. A $50 subscription to an industry journal or a $100 professional membership fee may seem insignificant. However, when aggregated over a full year, these small, legitimate costs can amount to a substantial deduction.
The Critical Role of Record-Keeping
To be unequivocally clear: no deduction is valid without proof. The ATO requires you to substantiate all claims, making diligent record-keeping a non-negotiable component of tax planning.
Fortunately, modern technology has rendered the proverbial shoebox of faded receipts obsolete. Tools like receipt scanning AI streamline this process, enabling you to capture every expense and even identify potential deductions automatically. Digital records are easier to store, organise, and retrieve should the ATO request verification.
For a comprehensive checklist and further real-world examples, our detailed guide on what tax deductions you can claim in Australia is an invaluable resource.
Ultimately, maximising your tax deductions is a matter of diligence. By understanding the rules, maintaining immaculate records, and critically evaluating all work-related expenditure, you can legally and significantly reduce your taxable income.
To ensure you aren't missing a single deduction, engage the tax experts at EndureGo Tax for a thorough review of your expenses. Book a consultation today to discover how much you could save.
Using Superannuation and Salary Sacrificing
Your superannuation is far more than a retirement nest egg; it is one of the most powerful instruments available for anyone seeking to understand how to lower taxable income in the present. By strategically managing your super contributions, you can reduce your immediate tax liability while accumulating wealth in a highly tax-effective environment.
The strategic advantage lies in the taxation of contributions. Money directed into your superannuation fund before tax is applied—known as a concessional contribution—is taxed at a flat rate of only 15% within the fund. For most Australians, this represents a substantial saving compared to their marginal tax rate, which can be as high as 45% (plus the Medicare levy).
Understanding Concessional Contributions
Concessional contributions include the compulsory super guarantee paid by your employer, any additional amounts you contribute from your pre-tax salary (salary sacrificing), and any personal contributions for which you claim a tax deduction. This method is a direct and highly effective way to lower your taxable income because the contributed funds are diverted to super before being assessed at your higher personal income tax rate.
Let's illustrate with a practical example. An individual earning $90,000 per annum falls into the 32.5% tax bracket (plus Medicare levy). If they make a personal concessional contribution of $5,000, that sum is taxed at 15% within their super fund, not at their marginal rate of 32.5%.
The immediate tax saving on that $5,000 contribution is $875. This is the difference between paying $1,625 in tax at your personal rate versus just $750 inside super. This is an astute financial decision.
The Power of Salary Sacrificing
Salary sacrificing (also known as salary packaging) is a formal arrangement with your employer where you agree to forgo a portion of your future salary, which is then paid directly into your superannuation fund. It is one of the most common and effective methods for making additional concessional contributions.
Here is a practical comparison illustrating the benefits:
Without Salary Sacrificing:
- Gross Annual Salary: $100,000
- Tax Payable (approx.): $22,967
- Net Income: $77,033
With Salary Sacrificing $10,000 to Super:
- Taxable Gross Salary: $90,000
- Tax Payable (approx.): $19,467
- Net Income: $70,533
- Additional Super Balance: $8,500 (after the 15% contributions tax)
By sacrificing $10,000, your take-home pay is reduced by only $6,500, while your superannuation balance increases by a substantial $8,500. You have effectively converted a $3,500 tax liability into retirement savings. This is expert-level money management.
Comparing Contribution Types
It is vital to understand the distinction between the two primary contribution types. The table below provides a clear breakdown.
Comparing Concessional and Non-Concessional Super Contributions
This side-by-side comparison highlights the different tax treatments and strategic applications of the two main types of super contributions.
| Feature | Concessional (Before-Tax) | Non-Concessional (After-Tax) |
|---|---|---|
| Tax Treatment | Contributions are taxed at 15% within the super fund. | Contributions are made from after-tax income, so no further tax is paid upon entry into the fund. |
| How It's Made | Employer contributions, salary sacrifice, personal deductible contributions. | Personal contributions from your bank account for which you do not claim a tax deduction. |
| Primary Benefit | Reduces your taxable income for the current financial year. | Allows the transfer of savings into a tax-advantaged environment where earnings are taxed at only 15%. |
| Best For | Individuals on middle to high incomes seeking an immediate tax reduction. | Those who have maximised their concessional cap or wish to transfer a lump sum (e.g., from an inheritance) into super. |
Grasping this distinction is fundamental to building an effective wealth creation and tax minimisation strategy. One lowers your tax liability now, while the other facilitates wealth growth in a low-tax environment for the future.
ATO Guideline: The Australian Taxation Office imposes strict annual caps on contributions. Exceeding these caps can attract significant penalties. Detailed information on these limits is available directly from the ATO and in legislative instruments like the Treasury Laws Amendment (Your Future, Your Super) Regulations 2021.
Staying Within the Limits
While boosting your super is a superb strategy, you must adhere to the annual contribution caps. For the 2024-25 financial year, the general concessional contributions cap is $27,500. Remember, this cap includes your employer's compulsory superannuation guarantee contributions.
For a more detailed analysis of the specific rules, we have compiled a clear breakdown of the current superannuation contribution limits.
Exceeding the cap can trigger excess contributions tax, which negates the benefits of the strategy. It is imperative to monitor your total contributions before 30 June each year.
Are you ready to leverage your superannuation to its full potential? A well-structured salary sacrifice arrangement can significantly impact your taxable income. Contact EndureGo Tax today to devise a strategy that aligns with your financial objectives and ensures full compliance with all ATO regulations.
Playing the Long Game: Investments and Business Structures
For astute investors and business owners, strategic structuring is paramount for tax optimisation. Once you have mastered deductions and superannuation, the manner in which you own assets and operate your business can unlock sophisticated tax-saving opportunities.
Let’s explore these advanced strategies.
Negative Gearing: Turning a Loss Into a Win
Sophisticated property investors frequently employ a strategy known as negative gearing. This situation arises when the deductible expenses of owning a rental property—such as loan interest, council rates, and maintenance—exceed the rental income generated.
Under Australian tax law, this net rental loss can be offset against your other assessable income, such as your salary. While seemingly counterintuitive, it is a powerful wealth-building strategy.
Here is a real-world application:
- Annual Rental Income: $26,000
- Total Deductible Expenses (Interest, Rates, etc.): $35,000
- Net Rental Loss: $9,000
If your salary is $110,000, this $9,000 loss reduces your taxable income to $101,000. For an individual on the 32.5% marginal tax rate, this strategy alone saves $2,925 in tax for that year. It renders an otherwise cash-flow negative investment manageable in the short term, allowing you to benefit from long-term capital appreciation.
You can find further details on the ATO's official guidance for rental property expenses.
Choosing the Right Business Structure
For entrepreneurs, your choice of business structure is one of the most critical financial decisions you will ever make. While operating as a sole trader offers simplicity, transitioning to a company or trust structure can be a game-changer for tax efficiency.
A company structure, for example, is taxed at a flat rate of 25% for eligible small businesses. This is significantly lower than personal marginal tax rates, which can be as high as 45%. This differential allows you to retain more profit within the business for reinvestment and growth.
A discretionary trust (or family trust) offers even greater flexibility. A trust itself is not taxed; instead, its income is distributed to beneficiaries annually. This facilitates legitimate income splitting. Profits can be distributed to family members in lower tax brackets, such as a spouse working part-time, thereby minimising the family's overall tax burden.
A Word of Warning: Income splitting must be executed carefully. To be effective, distributions must be genuine and made to adult beneficiaries. The ATO applies penalty tax rates to distributions made to minors to discourage improper arrangements.
Establishing these structures is a formal process involving registration and ongoing compliance obligations. For a comprehensive breakdown of your options, please refer to our guide on exploring business structures in Australia.
Capital Depreciation and the Instant Asset Write-Off
Another powerful tool for business owners is the ability to claim the declining value of business assets, a process known as depreciation. For a carpenter, this could be a new ute; for a graphic designer, a high-performance computer.
The instant asset write-off scheme is even more advantageous. This provision allows eligible businesses to claim an immediate, full deduction for the cost of an asset in the year it is first used.
For instance, if a landscaping business in Belrose purchases a new vehicle for $55,000, instead of depreciating that cost over several years, the instant asset write-off may allow them to deduct the entire $55,000 from their taxable income in a single year. This results in a substantial and immediate reduction in their tax liability, improving vital cash flow.
Operating a company or trust necessitates compliance with ASIC regulations, a critical aspect of corporate governance.
This image underscores the formal steps involved in company registration, from choosing a structure to appointing officeholders and understanding your legal duties from the outset.
Selecting and managing these advanced structures is not a DIY task. It requires expert advice to ensure compliance with both ATO and ASIC obligations.
Are you ready to get strategic with your investments and business structure? Book a consultation with EndureGo Tax. As your local ASIC agent, we ensure your setup is optimised for maximum tax efficiency and full compliance.
Smart Timing and Diligent Record-Keeping
While macro strategies like business structuring and superannuation are powerful, some of the most effective tax planning techniques hinge on two fundamental principles: timing and evidence. Knowing when to incur an expense or recognise income can have a profound impact on your tax liability.
However, without impeccable records, even the most sophisticated strategies are rendered indefensible in the event of an ATO audit.
Thinking about how to lower taxable income is not just about finding deductions; it's about managing the flow of money across the financial year, especially as the 30 June deadline approaches.
Strategic Timing of Income and Expenses
Timing is paramount because your tax liability is calculated within a specific 12-month period. By legally shifting income or expenses across this deadline, you can directly influence your tax outcome.
A classic expert strategy is the prepayment of deductible expenses. For example, if you know your professional indemnity insurance is due for renewal in July, paying it in June allows you to claim the deduction in the current financial year. This immediately lowers your tax bill. This prepayment strategy is a legitimate method for managing your tax liability.
Conversely, for contractors and small business owners with control over their invoicing, deferring income can be advantageous. If a major project is completed in the last week of June, issuing the invoice in the first week of July means that income falls into the next financial year. This can be a game-changer if you anticipate being in a lower tax bracket in the following year.
ATO Legislation Link: The rules governing the deductibility of prepaid expenses are detailed in the Income Tax Assessment Act 1997. While the specifics can be complex, the general principles permit these timing strategies, provided they are not part of a tax avoidance scheme. Expert advice is recommended.
The Non-Negotiable Role of Record-Keeping
Let's be direct. None of these timing strategies are effective without meticulous records. Your ability to substantiate deductions and justify financial decisions rests entirely on the quality of your evidence. Consider your records your ultimate defence.
You are effectively constructing a fortress of proof around your tax return. The ATO does not operate on trust; it demands substantiation.
Here is a practical checklist of essential records to maintain:
- Receipts and Invoices: For every single business or work-related expense.
- Bank Statements: To verify transactions.
- Logbooks: Crucial for motor vehicle expenses to prove the business-use percentage.
- Diaries or Digital Notes: To record details of cash expenses or home office hours.
- Contracts and Agreements: For all income-producing activities or significant asset purchases.
Recent government finance statistics from the ABS website demonstrate the macroeconomic impact of timing. Following the Stage 3 tax cuts, personal income tax revenue growth slowed to 1.3% in the 2024–25 financial year, a sharp decline from 11.4% the previous year. For small business owners, this reinforces the importance of smart timing and flawless records to ensure you fully benefit from these legislative changes.
Maintaining organised records is no longer a burdensome task. Digital tools and apps can automate much of the process by scanning and storing receipts in the cloud. This simple habit is key to claiming every dollar you are entitled to and ensuring full compliance.
Is your record-keeping system truly audit-proof? Speak with the experts at EndureGo Tax for a professional review of your processes and to ensure you have the evidence required to substantiate every single claim.
Got Questions About Lowering Your Tax Bill? We Have Answers.
When navigating the complexities of tax law, many questions arise. As expert accountants dedicated to helping clients legally determine how to lower taxable income, we consistently address the same concerns from individuals and business owners across Sydney. Let's tackle the most common queries with clear, authoritative answers.
Is It Actually Legal to Try and Lower My Taxable Income?
Absolutely. It is vital to understand the distinction between legal tax planning and illegal evasion.
The strategies discussed in this guide fall under the umbrella of tax minimisation or tax planning. This is the perfectly legal practice of arranging your financial affairs to pay the minimum amount of tax required by law. It involves utilising legitimate deductions, offsets, and structures provided for within Australian tax legislation.
The Australian Taxation Office (ATO) establishes these mechanisms with the full expectation that taxpayers will use them to manage their tax obligations effectively.
This is fundamentally different from tax evasion, which is the illegal act of deliberately concealing income or providing false information to the ATO. Our focus is exclusively on legal and ethical tax minimisation to enhance your financial position while ensuring full compliance. The ATO provides extensive guidance on this topic, including in public rulings related to Part IVA of the Income Tax Assessment Act 1936, which contains the general anti-avoidance provisions.
What Are the Most Overlooked Tax Deductions?
It is unfortunate how many Australians forgo valuable deductions due to a lack of awareness or inadequate record-keeping. Beyond the standard claims, here are some of the most commonly overlooked deductions we identify for our clients:
- Income Protection Insurance Premiums: If your policy is held outside of your superannuation, the premiums are almost always fully tax-deductible.
- Union and Professional Association Fees: Annual membership fees for professional bodies or trade unions are a direct deduction against your income.
- Work-Related Subscriptions: This includes subscriptions to industry journals, professional publications, and paid online resources directly related to earning your income.
- Small Tool and Equipment Purchases: A tradesperson may forget to claim a new power tool, or a consultant may overlook a software subscription. These minor costs aggregate into a significant deduction over a full year.
- Costs of Managing Tax Affairs: The fee you pay your registered tax agent for preparing and lodging your tax return is deductible in the following year's return.
Our Best Tip: The key to capturing every deduction is establishing a routine. Develop the habit of immediately photographing every receipt for work-related purchases with your smartphone and storing it in a dedicated cloud folder. This simple discipline can translate into thousands of dollars in tax savings.
Maintaining detailed, contemporaneous records is the only way to ensure you can claim every entitlement at tax time.
When Is It Time to Hire a Tax Accountant?
While lodging a simple individual tax return yourself is possible, engaging a professional tax accountant becomes essential as your financial situation grows in complexity. The investment in professional advice almost always yields a significant return.
It is definitely time to seek professional guidance if you:
- Start a small business or operate as a sole trader.
- Purchase an investment property.
- Incur capital gains or losses from shares, property, or cryptocurrency.
- Establish or become a beneficiary of a trust.
- Are required to lodge Business Activity Statements (BAS).
An expert accountant does more than ensure compliance; they proactively identify opportunities to legally lower your taxable income that you would likely miss. The tax saved often far exceeds their fee, making it one of the most intelligent investments you can make in your financial well-being.
Navigating these questions is our expertise. At EndureGo Tax, we provide the clarity and strategic guidance you need to manage your tax affairs with confidence. Whether you are a sole trader in the Inner West or operate a company on the Northern Beaches, we are here to help you build an intelligent, compliant tax strategy. Book a consultation today and allow us to manage the complexities for you.
