


When a property in Australia is sold by someone who isn't an Australian resident for tax purposes, the purchaser has a critical obligation. They must hold back a portion of the sale price and remit it directly to the Australian Taxation Office (ATO). This process is known as foreign resident capital gains withholding (FRCGW). It acts as a mandatory prepayment of the seller's potential capital gains tax, ensuring tax obligations are met before sale proceeds leave the country. As a professional in this field, I cannot stress enough the importance of getting this right.
What Is Foreign Resident Capital Gains Withholding?
Think of Foreign Resident Capital Gains Withholding (FRCGW) as a 'tax deposit' mechanism. It is a legislative tool the Australian government employs to safeguard its tax revenue. The core purpose is to prevent foreign residents from liquidating Australian assets, such as real estate, and then exiting the country without settling their Capital Gains Tax (CGT) liability.
The legal onus for withholding falls squarely on the purchaser's shoulders. At settlement, the purchaser is legally required to withhold a legislated percentage of the purchase price and forward it to the ATO. It is not an additional tax; it is an upfront payment of the seller's estimated tax. The foreign resident vendor can then claim this amount as a credit when they lodge their Australian income tax return.
Key Changes to the FRCGW Rules
The legislative framework for this withholding tax is undergoing a significant overhaul. Whether you are an Australian expat selling an investment property in Sydney's Northern Beaches or a foreign investor offloading a unit in Ashfield, the rules are changing. For any contract signed before 1 January 2025, FRCGW only applies to properties with a market value of $750,000 or more, and the withholding rate is 12.5%.
However, from 1 January 2025, the landscape shifts dramatically. Due to Act No. 135, 2024 (Treasury Laws Amendment), the $750,000 threshold will be removed entirely. This means every sale of taxable Australian real property by a foreign resident will trigger the withholding obligation, regardless of the price. Furthermore, the withholding rate will increase to 15%.
This is a profound change. For property investors, it is more critical than ever to understand the evolving tax laws affecting buy-to-let investments.
A Snapshot of FRCGW Rule Changes
This table provides a concise summary of the critical changes to the FRCGW regime, highlighting the differences in thresholds and rates for property contracts.
| Rule Component | Contracts Before 1 Jan 2025 | Contracts On or After 1 Jan 2025 |
|---|---|---|
| Property Value Threshold | $750,000 | $0 (No threshold) |
| Withholding Rate | 12.5% | 15% |
In short, a $1 million sale that previously required a $125,000 withholding will now require $150,000 to be remitted to the ATO. The new rules cast a much wider net and significantly increase the upfront tax payment.
Who Is Affected by This System?
The FRCGW rules create distinct, legally enforceable responsibilities for both parties in a property transaction. Understanding your role is the first step to ensuring a seamless settlement.
- Sellers (Vendors): If you are a foreign resident for tax purposes, this withholding applies to you. The primary exemption is for Australian residents who can provide the purchaser with a valid ATO Clearance Certificate before settlement.
- Buyers (Purchasers): You are legally obligated to determine if withholding is necessary. If the vendor does not provide a valid clearance certificate, you must withhold the required amount from the purchase price and pay it to the ATO.
Failure to comply can lead to severe financial penalties for the purchaser. This is not a matter to be left to chance. You can explore the intricacies in our comprehensive guide to foreign resident capital gains tax in Australia.
Navigating these regulations, especially with the impending 2025 changes, can be a minefield. If you are buying or selling property in Ashfield or Belrose, ensuring compliance is paramount. Contact EndureGo Tax today for expert guidance on your FRCGW obligations and ensure your settlement proceeds without costly surprises.
Who Does What? Buyer vs. Seller Roles in a Nutshell
When a property transaction falls under the foreign resident capital gains withholding regime, both the purchaser and the vendor have distinct, legally binding obligations. Fulfilling these roles correctly is not just best practice; it is essential for a compliant and smooth settlement. The entire system is predicated on each party understanding and executing their duties.
For purchasers, it is a non-negotiable duty to withhold the tax. For vendors, it is about providing definitive proof of their Australian tax residency.
Let’s dissect what this means in practical terms.
The Buyer’s Responsibility: You're in the Driver's Seat
As the purchaser, the law places the responsibility to withhold tax squarely on your shoulders. You effectively act as a collection agent for the Australian Taxation Office (ATO). This is not a delegable or optional task—non-compliance can result in significant financial penalties.
This duty applies universally, whether you are an individual buying your first home, a company acquiring a commercial property, or a trustee acting for a trust. The rule is unambiguous: if the vendor does not provide a valid ATO Clearance Certificate before settlement, you must withhold the required portion of the purchase price.
Failure to do so could result in you being liable for the entire withholding amount, plus substantial interest and penalties. The ATO enforces this rigorously, as the integrity of the FRCGW framework relies on purchaser compliance.
The legal principle here is "strict liability," as outlined in the Taxation Administration Act 1953. This means defences like "I didn't know" or "it was an oversight" are not acceptable. The legislation, specifically Schedule 1, section 14-200 of the Act, makes it clear that the obligation is absolute.
The Seller's Job: Prove Your Residency
If you are the vendor, your primary objective is to prove your Australian tax residency. The FRCGW rules are designed to apply to foreign residents, so if you are a local resident for tax purposes, you can avoid the withholding entirely. However, the burden of proof rests with you.
A verbal assurance or a statutory declaration is insufficient. You must provide official proof in the form of an ATO Clearance Certificate. This document is your definitive exemption, formally notifying the purchaser that you are an Australian resident for tax purposes and that no withholding is required at settlement.
Let's consider a practical example:
Imagine you are an Australian citizen residing in Belrose and selling your investment unit in Ashfield. To ensure you receive the full sale proceeds at settlement, you must apply to the ATO for a Clearance Certificate well in advance. Once issued, you provide it to your conveyancer, who then furnishes it to the purchaser's legal representative. With this document, their obligation to withhold 15% of the purchase price is nullified.
So, How Does the ATO Define Tax Residency?
The ATO’s definition of a "resident" extends beyond your passport or citizenship status. It is a practical assessment based on your circumstances, and the tests differ for individuals, companies, and trusts.
- For Individuals: The ATO applies tests such as the 'resides test' (where you physically live and your intentions) and the 'domicile test' (your permanent home).
- For Companies: A company is generally a resident if it is incorporated in Australia or if its central management and control are located here.
- For Trusts: A trust's residency often depends on the residency of the trustee(s) and the location where key decisions are made.
Understanding your obligations and acting preemptively is crucial for a stress-free settlement. If you are uncertain about your residency status or need assistance navigating your role as a purchaser or vendor in Ashfield or the Northern Beaches, the team at EndureGo Tax is ready to assist. Book a consultation today and let's ensure compliance from the outset.
How to Get Your ATO Clearance Certificate
If you are an Australian resident selling property, the ATO Clearance Certificate is arguably the most critical document you will handle. It is your official proof of tax residency status, instructing the purchaser not to withhold any of your sale proceeds for the tax office.
Without this certificate, the purchaser is legally compelled to assume you are a foreign resident and remit a substantial portion of your money directly to the ATO. Securing this certificate is a proactive measure that ensures you receive the full sale price at settlement, preventing frustrating delays and significant cash flow disruption. The process is not complex, but timing is paramount.
Who Is Eligible to Apply?
Eligibility for an ATO Clearance Certificate is straightforward: you must be an Australian resident for tax purposes at the time of the transaction.
This includes:
- Individuals who satisfy the ATO's residency tests.
- Companies that are incorporated in Australia or have their central management and control here.
- Trustees of a trust that is considered an Australian resident trust.
A common misconception is that citizenship or visa status automatically determines tax residency. The ATO's assessment is more nuanced, examining your specific circumstances, including your physical presence and long-term intentions.
The Application Process Explained
The application for a clearance certificate is completed online via the ATO portal. While the process is designed to be efficient, the cardinal rule is to apply well ahead of your property settlement date.
Here’s a breakdown of the steps:
- Prepare Your Details: You will need your Tax File Number (TFN), key details from the sale contract, and personal identification information.
- Complete the Online Form: The application is entirely digital. You can complete it yourself, or a registered tax agent, such as EndureGo Tax, can manage it on your behalf.
- Submit and Await Processing: Once lodged, the application is processed by the ATO.
Most applications are processed automatically within days. However, if any details do not perfectly match the ATO's records, a manual review may be triggered, which can take up to 28 days. This potential delay is precisely why we advise our clients to apply as soon as they decide to sell.
For a deeper dive, check out our guide on understanding the ATO Clearance Certificate process in Inner West Sydney.
How Long Is the Certificate Valid For?
Once issued, your ATO Clearance Certificate is valid for a full 12 months. This is highly beneficial for active property investors, as the same certificate can be used for multiple sales within that period.
You simply need to provide a copy of the valid certificate to the purchaser on or before the day of settlement. This single action formally relieves them of their duty to withhold any funds under the foreign resident capital gains withholding rules.
What’s the Deal With a Vendor Declaration?
You may encounter the term 'Vendor Declaration', but its application is extremely limited. It only applies to sales of assets that are not taxable Australian real property, such as certain types of company shares.
For the sale of land or buildings, let's be unequivocal: the ATO Clearance Certificate is the only document that provides a valid exemption from FRCGW. Do not be misled.
Securing this essential piece of paperwork is non-negotiable for a smooth property sale. If you're selling a property in Ashfield or Belrose, let the experts at EndureGo Tax handle your ATO Clearance Certificate application. Contact us today so you can focus on the sale, not the administrative burden.
What if the 15% Withholding Rate Is Too High? Using a Variation
The standard 15% FRCGW rate is a blunt instrument. It is a one-size-fits-all approach that does not account for your actual tax liability.
Consider this: what happens if you are a foreign resident selling a property with a minimal capital gain, or worse, at a capital loss? Compelling the purchaser to withhold a substantial sum that far exceeds your actual tax obligation can create a severe cash flow problem at settlement.
This is precisely where a Variation Application becomes an indispensable tool.
It is a formal request to the Australian Taxation Office (ATO) to reduce the withholding rate for your specific transaction. If approved, the amount withheld will be a much more accurate reflection of your final tax liability.
Instead of waiting months to receive a large refund after lodging your tax return, a variation allows you to retain more of your funds from day one.
When Should You Apply for a Variation?
A variation is not a loophole; it is a mechanism provided by the ATO for situations where the standard 15% rate would be inequitable. The ATO will consider reducing the rate if you can provide clear evidence demonstrating that a lower amount is more appropriate.
Common scenarios where a variation is a prudent strategy include:
- You've made a capital loss. If the property is being sold for less than its cost base, you will have no capital gains tax to pay. A successful variation application could reduce the withholding rate to 0%.
- Your capital gain is small. If property values have only increased marginally, 15% of the sale price could be significantly higher than your actual tax liability.
- You have carried-forward capital losses. Losses from previous investments can be used to offset the gain on the current property sale, reducing your overall tax bill.
The objective is to demonstrate to the ATO that your final tax liability will be substantially less than the standard withholding amount.
How to Apply for a Variation
Applying for a variation is not a last-minute task—it requires careful preparation. You must submit the application online to the ATO before the settlement date and provide robust evidence to substantiate your claim.
This involves more than completing a simple form. You will need to compile financial details and supporting documents, such as:
- Proof of the property's original purchase price (your "cost base").
- A detailed calculation of your estimated capital gain or loss.
- Evidence of other factors reducing your tax liability, like carried-forward losses.
The ATO views the variation application as a crucial element in ensuring the FRCGW system's fairness. The legal basis is found in section 14-235 in Schedule 1 of the Taxation Administration Act 1953, which permits a vendor to apply for a variation if they believe the standard withholding is inappropriate.
This process must be completed before settlement day, as the purchaser is legally bound by the notice issued by the ATO. If you need assistance with the calculations, our guide can help you understand how to maximise your tax refund for foreign capital gain withholding tax.
Don't Forget the Main Residence Exemption
For some foreign residents, another powerful exemption may be relevant—the main residence exemption.
Historically, this was available to most homeowners. However, the rules were significantly reformed in 2020. Now, you can generally only claim this exemption if you are an Australian resident for tax purposes at the time you dispose of the property.
There are very limited exceptions, such as the 'life events test'. If you have been a foreign resident for a continuous period of six years or less and experienced a major life event (like a terminal medical condition or the death of a spouse), you might still qualify. This is a complex area of tax law, and errors can be costly.
If you are a foreign resident vendor in Ashfield or Belrose and the standard withholding rate seems excessive for your circumstances, do not simply accept it. Contact EndureGo Tax today to discuss applying for a variation and securing a more favourable financial outcome at settlement.
Putting FRCGW into Practice: Real-World Examples
Theoretical knowledge is one thing, but observing how the rules apply in practice is where true understanding is forged. Let’s examine a few common scenarios we manage daily for clients in Ashfield and Belrose to illustrate how Foreign Resident Capital Gains Withholding (FRCGW) operates in real-world transactions.
By applying actual figures, you will gain a clear perspective on the financial impact of obtaining a clearance certificate, applying for a variation, or having the standard rate applied.
Scenario 1: The Australian Resident Seller in Belrose
Meet Sarah. She is a long-term Australian resident living on the Northern Beaches and is selling her investment townhouse in Belrose. After ten years of ownership, she secures a buyer at a sale price of $1,200,000.
Because the property's value exceeds the $0 threshold (effective from 1 January 2025), the FRCGW rules are triggered by default. The purchaser's conveyancer must obtain proof of Sarah's residency status to avoid withholding a significant portion of the sale price.
Here’s how Sarah expertly navigates this:
- She's Proactive: The moment the property is listed, Sarah engages her accountant at EndureGo Tax. We immediately lodge an online application for an ATO Clearance Certificate on her behalf.
- Quick Turnaround: As Sarah’s tax affairs are in order, the ATO’s system processes the application seamlessly. The certificate is issued within three business days.
- Smooth Settlement: With ample time, Sarah provides the valid certificate to the purchaser's legal team.
The Financial Result: The purchaser is now formally exempt from any withholding obligation. At settlement, Sarah receives the full $1,200,000, less standard costs like agent commissions and legal fees. No funds are remitted to the ATO.
This scenario demonstrates the immense value of the ATO Clearance Certificate. For Australian residents, it is an essential step to ensure your sale proceeds are received in full and without complication.
Scenario 2: The Foreign Investor in Ashfield
Now, consider David, a foreign investor residing overseas who owns an apartment in Ashfield. He sells his unit for $850,000, with the contract signed in February 2025.
As David is not an Australian resident for tax purposes, a clearance certificate is not an option. Consequently, the new 15% withholding rate applies.
For David, the settlement process is markedly different:
- The Withholding Calculation: The purchaser is legally required to withhold 15% of the $850,000 purchase price, which amounts to $127,500.
- Payment to the ATO: The purchaser’s representative lodges the Purchaser payment notification form and remits the $127,500 directly to the ATO on or before the day of settlement.
- David’s Net Proceeds: At settlement, David receives the sale price less the withheld amount: $850,000 – $127,500 = $722,500 (before his own costs are deducted).
What happens to the withheld funds? The $127,500 is not lost. It is held by the ATO as a tax credit in David's name. To finalise his position, David must lodge an Australian tax return declaring his capital gain. If his actual tax liability is, for example, $50,000, the ATO will refund him the $77,500 difference.
Scenario 3: The Foreign Resident with a Small Capital Gain
Finally, let’s analyse the case of Emily. She is a foreign resident selling a small commercial studio for $600,000. She purchased it for $550,000 a few years ago and has $10,000 in associated costs, resulting in a total capital gain of only $40,000.
If the standard 15% FRCGW rule were applied, the withholding would be $90,000 (15% of $600,000). This is more than double her entire profit, creating an inequitable cash flow outcome.
Emily wisely applies for a Variation:
- Lodging the Application: Emily and her tax agent prepare and lodge a variation application with the ATO, providing clear evidence of the property’s cost base and her calculated $40,000 gain.
- ATO Assessment: The ATO reviews the evidence and agrees that withholding $90,000 would be excessive. Based on her likely tax liability, they issue a variation notice reducing the withholding rate to just 3%.
- A Fairer Withholding: The purchaser is provided with the official variation notice. At settlement, they are now only required to withhold 3% of $600,000, which is $18,000.
The Financial Result: Instead of receiving only $510,000, Emily receives $582,000 at settlement. The much smaller withheld amount is a far more reasonable reflection of her actual tax liability.
To provide a clearer side-by-side comparison, here’s how the numbers stack up.
FRCGW Calculation Examples
This table breaks down the financial outcomes for each vendor, highlighting how their residency status and proactive planning directly impact their cash flow at settlement.
| Scenario | Property Sale Price | Applicable FRCGW Rate | Amount Withheld by Purchaser | Proceeds to Vendor at Settlement |
|---|---|---|---|---|
| Sarah (AU Resident) | $1,200,000 | 0% (Clearance Cert.) | $0 | $1,200,000 |
| David (Foreign Investor) | $850,000 | 15% (Standard Rate) | $127,500 | $722,500 |
| Emily (Foreign Resident) | $600,000 | 3% (Variation Notice) | $18,000 | $582,000 |
As demonstrated, taking the correct strategic steps before settlement can impact immediate cash flow by hundreds of thousands of dollars.
These examples make it abundantly clear: your residency status and financial circumstances dictate the strategy. Adhering to these rules is not merely about compliance—it's about optimising your financial outcome. If you are buying or selling in Ashfield or Belrose and require expert clarification, the team at EndureGo Tax is here to help. Book a consultation today to ensure your property transaction is executed flawlessly.
Your FRCGW Game Plan: Checklists for Buyers & Sellers
When engaging with Foreign Resident Capital Gains Withholding, proactive planning is paramount. Whether you are the vendor or the purchaser, both parties have clear responsibilities. A failure to execute these duties can lead to significant complications at settlement.
To simplify this, we have developed two concise checklists—one for the seller and one for the buyer. Consider these your roadmaps to a smooth, compliant, and stress-free transaction under Australian tax law.
The Seller's Checklist
As the vendor, your primary responsibility is to manage your position regarding the withholding rules proactively. This typically involves either proving your Australian residency to secure an exemption or, if you are a foreign resident, ensuring the amount withheld is appropriate to your circumstances.
Here’s your action plan:
Determine Your Residency Status: This is the foundational step. Are you an Australian resident for tax purposes? This is determined by specific legal tests, not citizenship. Your residency status dictates your obligations.
Obtain the Correct ATO Document:
- If you’re an Australian resident: Your top priority is to apply for an ATO Clearance Certificate. This is the definitive document that exempts the transaction from withholding.
- If you’re a foreign resident: The default withholding rate applies. However, if your actual capital gains tax liability will be significantly lower, you should apply for a Variation Notice to reduce the rate to a more appropriate level.
Provide Documents Before Settlement: Timing is critical. Whether it is a Clearance Certificate or a Variation Notice, you must provide a valid copy to the purchaser before the settlement date. Do not delay.
Lodge Your Tax Return: After the sale, a foreign resident must lodge an Australian income tax return. This is where you declare the capital gain, claim a credit for the amount withheld, and receive a refund if you have overpaid.
This diagram illustrates the pathways available to a vendor.
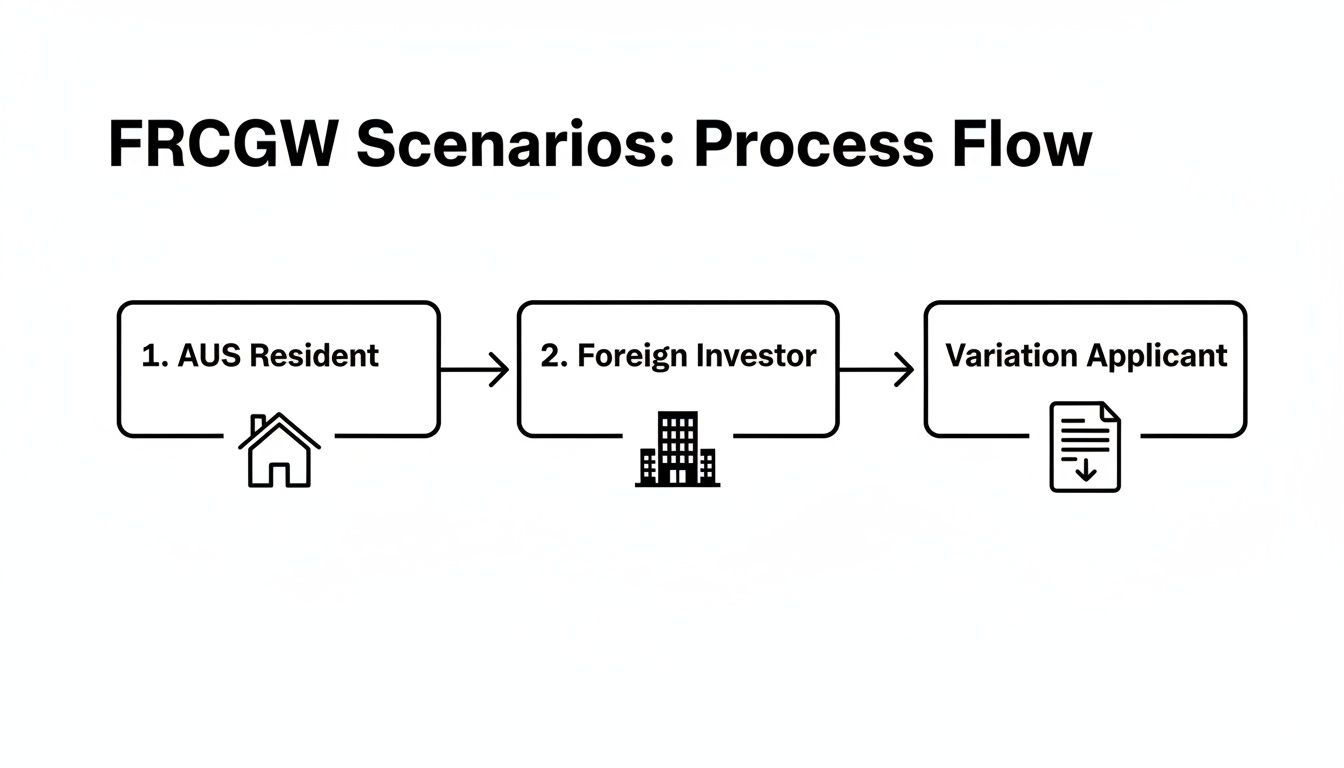
As shown, Australian residents can avoid withholding entirely, while foreign residents can either manage the standard rate or apply to have it reduced.
The Buyer's Checklist
As the purchaser, the law places the withholding obligation squarely on you. It is your duty to withhold funds if required. The penalties for non-compliance are severe, so due diligence is essential.
Request the Clearance Certificate: From the outset, your conveyancer must request a valid ATO Clearance Certificate from the vendor. Never assume residency—you must obtain official proof.
Verify the Document: Upon receipt, verify the certificate. Ensure the names and details match the property title and that it remains valid for the settlement date. The Taxation Administration Act 1953 is explicit—the liability rests with the purchaser.
Withhold the Correct Amount (If Required): If you do not receive a valid Clearance Certificate or a Variation Notice before settlement, you are legally obligated to withhold 15% of the purchase price (for contracts from 1 Jan 2025).
Lodge and Pay the ATO Promptly: You cannot retain the withheld funds. You must complete the Purchaser payment notification form and remit the funds to the ATO on or before the day of settlement.
Whether you are selling a home in Belrose or purchasing an apartment in Ashfield, seeking professional advice is the most effective way to safeguard your interests. Contact EndureGo Tax today to ensure you are compliant and prepared.
Frequently Asked Questions About FRCGW
When it comes to foreign resident capital gains withholding, the nuances matter. Here are some of the most frequent questions we receive from property owners and investors in Ashfield and Belrose, with expert answers.
What Happens If My Clearance Certificate Expires Before Settlement?
This is a scenario that can pose a significant risk. If settlement is delayed and your ATO Clearance Certificate expires, it becomes invalid. At that point, the purchaser's legal obligation to withhold 15% of the purchase price is reinstated.
To mitigate this, you must apply for a new certificate as soon as a settlement delay is known. While the ATO's processing is often efficient, it can take up to 28 days during peak periods. Acting swiftly is non-negotiable to prevent a large portion of your sale proceeds from being withheld.
Can I Get Withheld Money Back If I Made a Capital Loss?
Absolutely. The withheld amount is a prepayment of potential tax, not a final tax itself. It is held by the ATO on your behalf. If you sell your property at a capital loss, you will not have a capital gains tax liability.
To recover the funds, you must lodge an Australian income tax return for the relevant financial year. In the return, you declare the capital loss and claim the FRCGW credit. The ATO will then process a full refund of the amount that was withheld at settlement.
It’s a critical point: FRCGW is about securing potential tax revenue. Your actual tax liability is only determined upon the lodgement of your tax return.
What Are the Penalties for Buyers Who Fail to Withhold?
The consequences are severe and fall entirely on the purchaser. If a purchaser fails to meet their withholding obligation, the ATO is empowered to impose a penalty equal to the full amount that should have been withheld, as stipulated in the Taxation Administration Act 1953.
For a $900,000 property sale, a failure to withhold could make the purchaser personally liable for the full $135,000 (15%), plus interest. This is a strict liability offence, underscoring the importance of purchaser diligence. For a deeper understanding, refer to the ATO's official guidance on purchaser obligations.
Does FRCGW Apply to Commercial Property?
Yes, it does. The rules apply to the sale of all 'taxable Australian real property,' a category that extends well beyond residential homes. It includes assets such as:
- Commercial buildings and offices
- Vacant land
- Farming and rural properties
- Certain mining, quarrying or prospecting rights
- Certain leasehold interests
This means business owners and commercial investors must be as diligent with the FRCGW regime as individuals selling residential property.
Navigating the complexities of foreign resident capital gains withholding demands meticulous planning and expert guidance. Whether you are in Ashfield or on the Northern Beaches, EndureGo Tax is committed to providing peace of mind and ensuring your property transaction is executed flawlessly. Book a consultation with your trusted local accountant today at https://www.endurego.com.au.
