


So, you’ve decided to sell your property. It’s an exciting time, but that amazing sale price you’re picturing isn't what lands in your bank account. The real number is what’s left after all the costs are paid.
The total fees for selling a house can take a surprisingly big bite out of your final profit. Getting your head around these costs upfront is the only way to know what you’ll actually walk away with.
Your Guide to the Real Cost of Selling a House
Think of selling your house like a mini-business project. The sale price is your revenue, but there's a list of expenses you need to cover before you can pocket the profit. Without a clear financial map, you could end up with a lot less than you bargained for.
This is your no-nonsense breakdown of every potential cost you’ll come across, from agent commissions and legal fees to marketing and tax.
To give you a quick snapshot, here’s a table summarising the main costs you can expect, usually calculated as a percentage of your property's sale price.
Estimated Costs at a Glance When Selling a House in Australia
| Expense Category | Typical Cost Range (% of Sale Price) | Notes |
|---|---|---|
| Agent Commission | 1.8% – 2.5% | This is your biggest single cost and is almost always negotiable. Rates can be higher in regional areas. |
| Legal/Conveyancing | $900 – $2,800+ | Often a fixed fee, but this can climb depending on how complex the sale is. Disbursements (extra search fees) are on top. |
| Marketing & Advertising | 0.5% – 1.0% | An upfront investment to get eyeballs on your property. A bigger budget might be needed for high-end homes or in competitive markets. |
| Pre-Sale Preparation | 0.25% – 0.75% | This bucket includes things like repairs, home staging, and getting pest/building reports done. |
| Mortgage Discharge | $150 – $1,000 | A simple admin fee your bank charges to officially close out your home loan. |
As you can see, the numbers add up. The costs fall into a few key categories that every seller needs to budget for.
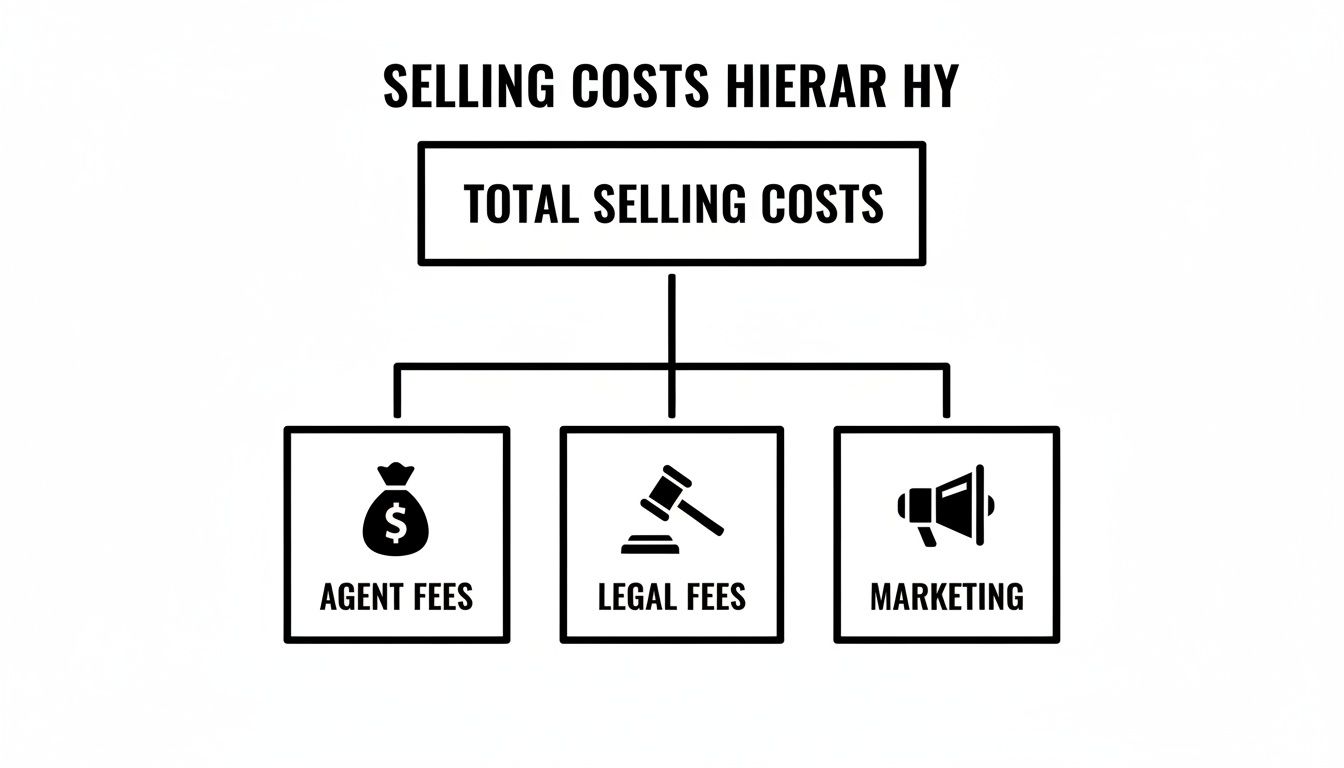
The diagram above really drives it home: your main costs are the agent, the lawyer, and the marketing campaign. While some of these fees are fixed, others are tied directly to your final sale price, so they’ll move up or down with the market.
Expert Tip: Don’t just think of these as costs—they’re investments. A sharp agent and a well-funded marketing plan can easily boost your sale price well beyond what you paid for them, putting more money in your pocket.
Finally, let’s talk about the elephant in the room: Capital Gains Tax (CGT). This is a huge one, especially if you’re selling an investment property. The Australian Taxation Office (ATO) defines a capital gain as the difference between what it cost you to get an asset and what you get when you sell it.
The rules are notoriously complex, particularly around the main residence exemption. Getting it wrong can be costly, so getting professional tax advice is non-negotiable if you want to legally minimise what you owe.
Planning for these costs isn't just good practice—it's essential for a smooth, stress-free sale. To make sure your tax obligations are handled by an expert from day one, see how EndureGo Tax can be your trusted partner for property tax matters.
Understanding Real Estate Agent Commissions and Fees
When you tally up the costs of selling a house, one figure almost always stands out: the real estate agent's commission. It's usually the largest single expense you'll face.
But it’s a mistake to view this as just another fee. Think of it as an investment in professional expertise—you’re paying for a skilled negotiator and market expert whose job is to get you the absolute best sale price. The catch? These fees aren't standardised and can vary wildly across Australia.
Getting your head around how commissions are structured is the first step to negotiating a deal that works for you. The percentage an agent charges will come down to their track record, the property's location, and the type of agreement you sign.
Commission Structures: Flat Fee vs Tiered Commissions
When you bring an agent on board, you’ll likely come across one of two main commission models. Each has its pros and cons, and the right one depends on your sales strategy.
Fixed or Flat Percentage Commission: This is the most common approach in Australia. You agree on a single percentage of the final sale price, which is paid to the agent once the sale successfully settles. Simple. For example, if you agree to a 2.1% commission and your home sells for $1,300,000, the agent's fee comes to $27,300.
Tiered or Incentive-Based Commission: This structure is all about motivating your agent to smash a specific price goal. It involves a lower base commission up to an agreed-upon price, with a much higher percentage kicking in for any amount achieved above that mark. It directly ties your agent’s financial reward to your goal of maximising the sale price.
A tiered structure might look something like this: 2.0% on the first $1.25 million of the sale price, and a juicy 5% on any amount fetched above that. If your property sells for $1,300,000, the agent earns $27,500 ($25,000 on the first $1.25M + $2,500 on the extra $50,000).
This incentive model can be a game-changer in a hot market, giving agents a powerful reason to squeeze every last dollar out of negotiations.
Why Small Percentage Differences Matter A Lot
It’s easy to shrug off a fraction of a percentage point, but when you’re dealing with an asset as valuable as property, it adds up—fast.
Let's go back to that $1.3 million home sale.
- At a 2.1% commission, the fee is $27,300.
- At a 2.5% commission, the fee jumps to $32,500.
That’s a $5,200 difference. Straight into your pocket, or the agent's. It shows why taking the time to negotiate your agent's commission is one of the most powerful moves you can make to control your selling costs.
Local Market Reality: Ashfield and the Northern Beaches
In Sydney’s hyper-competitive pockets like the Inner West (think Ashfield) and the Northern Beaches (like Belrose), you'll often find sharper commission rates. Why? There are more agents fighting for fewer listings.
While the NSW average might hover around 2.0% – 2.5%, you’ll find agents in these popular suburbs are often open to negotiating rates between 1.8% and 2.2%.
But a word of warning: the lowest rate isn't always the best deal. An agent who commands a slightly higher fee but has a proven track record of selling homes for a premium in your area could deliver a far better result for you financially. Always ask for proof of their recent sales and compare their strategy to others.
What Is (and Isn't) Included in the Commission
So, what are you actually paying for? The agent's commission should cover their time, professional advice, buyer management, open for inspections and private viewings, auctioneering services (if applicable), and of course, their negotiation skills. It’s the fee for their service in getting your property sold.
Crucially, marketing costs are almost always a separate expense. These are paid by you, the vendor, to cover things like online listings, photography, and signboards.
Also, be on the lookout for sneaky extras.
Actionable Tip: Before you sign anything, ask for a complete breakdown of all costs. Specifically, ask: "Are there any other 'administration fees' or 'compliance fees' on top of the commission?" Some agencies tack these on—often a few hundred dollars—so it’s vital to get clarity upfront. Asking the right questions ensures there are no nasty surprises when the final invoice lands.
Navigating Conveyancing and Legal Costs
Once you’ve accepted an offer on your home, the legal wheels start turning. This whole process is called conveyancing – it’s the official, formal transfer of the property title from you to the buyer. It’s a non-negotiable part of selling your house and a key cost you absolutely need to budget for.
To get it done, you’ll need to bring in either a licensed conveyancer or a solicitor. Think of them as the project manager for all the legal and financial paperwork. Their job is to make sure every document is spot on, from drafting the initial Contract of Sale to managing the money on the final settlement day.
Conveyancer vs Solicitor: Which One is Right for You?
So, who should you choose? You’ve got two main options, and the right one really comes down to how complex your property sale is.
Licensed Conveyancers: These professionals live and breathe property law. Because they specialise, they're often super-efficient and can offer very competitive fixed-fee pricing. For a straightforward residential sale with no obvious legal dramas, a good conveyancer is an excellent, budget-friendly choice.
Solicitors: A solicitor is a fully qualified lawyer who handles conveyancing but also has a much broader legal toolkit. Their fees might be a bit higher, but they are worth their weight in gold if your sale is complex. Think sales involving a deceased estate, a messy divorce, or tricky zoning issues. Their ability to step in on a wider range of legal disputes is your safety net.
Key Insight: For a standard home sale in an area like Ashfield or the Northern Beaches, a reputable licensed conveyancer is usually the perfect fit and will save you money. But if you have even a slight gut feeling that legal hurdles could pop up, paying a bit more for a solicitor from day one can save you a mountain of stress and cash later on.
Breaking Down the Costs of Conveyancing
The legal fees for selling your house really come in two parts: the professional fee for their service, and the disbursements.
Professional Service Fee: This is what you pay the conveyancer or solicitor for their time, expertise, and guidance. You can expect this to range anywhere from $900 to over $2,800, depending on who you hire and how complex your sale is. A lot of firms offer a fixed fee, which is great because you know exactly what you’re in for.
Disbursements: These are the out-of-pocket expenses your legal rep pays to other organisations on your behalf. They're then passed on to you in the final bill. These are unavoidable costs required to get the sale across the line.
Common disbursements include:
- Title Search: To prove you are the legal owner.
- Council and Water Rate Certificates (Section 10.7): To show what rates are owed on the property.
- Land Tax Search: To check for any outstanding land tax debts.
- Property Information Certificates: Pulled from various government bodies.
These little extras can easily add several hundred dollars to your total invoice. Always ask for a full quote that estimates both the professional fee and the likely disbursements before you sign anything.
A related cost to be aware of, especially for non-residents, is the Foreign Resident Capital Gains Withholding (FRCGW). If this might apply to you, having an expert who gets the clearance certificate process is critical. For a deeper look, check out our guide on mastering Foreign Resident Capital Gains Withholding.
Marketing & Advertising: The Investment That Pays You Back
After your agent and conveyancer, your next big cost is marketing. And let’s be direct: you can't sell a secret. If you want to attract the largest pool of serious buyers and create the kind of competition that drives up your sale price, you have to invest in a smart marketing campaign.
This is absolutely not the place to cut corners. A modern campaign is about getting your home in front of buyers wherever they are—on their phones, on property websites, and in the local area. In a hot market, a well-funded campaign is what separates a decent result from an incredible one.
What Your Marketing Budget Actually Pays For
When your agent hands you a marketing schedule, it's usually an upfront cost paid by you, the seller. The total number might look a bit daunting at first, but it’s broken down into several crucial elements, each with a specific job to do.
A typical marketing package in competitive Sydney suburbs like Ashfield or Belrose can range from $5,000 to over $12,000, depending on your home's value and how wide a net you want to cast.
Here’s a common breakdown of where that money really goes:
- Professional Photography & Videography: This is non-negotiable. Amazing photos are the first thing a buyer sees, and they're what make someone stop scrolling and click on your property.
- Floor Plans: Buyers expect a floor plan. It helps them visualise the space, picture their furniture in it, and understand the flow before they even step foot inside.
- Online Portal Listings: This is the big-ticket item. A premium or feature listing on major sites like realestate.com.au and Domain keeps your property at the top of search results, massively boosting its visibility.
- Signboard: Don’t underestimate the old-school "For Sale" sign. It's still a powerhouse for grabbing the attention of locals and those "passive buyers" who weren't even looking until they drove past your home.
- Social Media Advertising: Targeted ads on Facebook and Instagram can reach thousands of potential buyers in your area who fit the exact demographic for your home. It’s incredibly powerful.
Why Skimping on Marketing Can Cost You a Fortune
It’s tempting to pick the cheapest marketing option to save a few dollars. I get it. But honestly, it's often a false economy that can cost you dearly in the long run.
Let’s use a real-world example. Imagine two sellers in Ashfield with similar homes, both valued around $1.5 million.
- Seller A goes with a basic $5,000 marketing package. They get standard photos and a basic online ad that quickly gets buried by newer, shinier listings. They attract a few buyers and manage to sell for $1.52 million. Not bad.
- Seller B invests in a premium $8,000 package. This gets them stunning twilight photos, a walkthrough video, and a top-tier feature spot on Domain. Their home stays visible, they get double the number of groups through their open homes, and the buzz creates a fierce auction, pushing the final price to $1.6 million.
So, what happened? Seller B’s extra $3,000 investment generated an extra $80,000 at sale time. That’s a huge return. This shows that smart marketing isn't a cost—it's a tool for maximising your profit.
Key Insight: Think of your marketing budget like fuel for your sales campaign. A budget package might get you started, but a premium package gives you the horsepower to overtake the competition and land a much, much better price.
What About Home Staging?
Home staging is the art of professionally furnishing your home to make it irresistible to buyers. While it's a separate cost from your agent's marketing package, it’s one of the most powerful advertising tools you can use.
A professionally staged home helps buyers form an emotional connection and see the property's true potential. Costs can range from $2,000 to $8,000+ for a full house, but the impact is undeniable, often leading to faster sales and higher offers. In style-conscious areas like Sydney's Inner West, staging can be the difference-maker.
Actionable Tip: Always ask your agent for a detailed, itemised marketing quote. Don't be afraid to ask what each item costs and why it’s necessary. A great agent will confidently explain how every dollar is being put to work to get you the best possible price.
The Upfront Costs: Budgeting for Your Pre-Sale Prep
Before your agent even books the photographer, there are a few upfront costs you need to get your head around. These aren't the big-ticket items like agent commission, but they are absolutely essential investments to make your property shine and give buyers the confidence to make a great offer.
Think of it as setting the stage. Getting these details right can make a world of difference in a competitive market, attracting more interest and helping you sell faster.
Essential Reports and Inspections
Smart sellers, especially in hot markets like Sydney’s Inner West or the Northern Beaches, often get their own reports done before the first open for inspection. Why? Because it removes roadblocks for buyers.
When you hand a potential buyer a pre-sale building report or a strata report, you’re giving them certainty. They don’t have to scramble to organise their own, making it easier for them to bid with confidence come auction day.
- Building & Pest Inspection Reports: Costing between $400 and $800, these reports give buyers a transparent look at the property’s condition. It’s a proactive move that builds trust and streamlines the whole process.
- Strata Report (for apartments/townhouses): If you're selling a unit or townhouse, this is non-negotiable. For around $300 – $450, it lays out the financial health of the owners' corporation, highlights any special levies on the horizon, and gives buyers the full story of the building.
Repairs and Cosmetic Touch-Ups
First impressions are everything in real estate. You don’t need a full-blown renovation, but small, strategic fixes can offer a massive return on investment. The goal is to make your home feel cared for and move-in ready.
Focus on high-impact, low-cost jobs. A fresh coat of neutral paint can make a room feel bigger and brighter, fixing that annoying leaky tap eliminates a red flag for buyers, and a tidied-up garden instantly boosts street appeal. For more ideas on how to improve your home’s presentation without breaking the bank, check out these budget landscaping ideas and low-cost upgrades.
Expert Insight: The aim here is to remove any excuse for a buyer to chip away at your price. Buyers often overestimate how much repairs will cost. Spending $500 to fix a few minor issues could easily save you from a buyer trying to negotiate $5,000 off the sale price.
The Often-Forgotten Mortgage Discharge Fee
Here’s one that catches so many sellers by surprise: the mortgage discharge fee. When you sell, your home loan doesn’t just disappear. You have to formally close it out, and your bank will charge an admin fee for the paperwork involved.
This fee, which might be called a 'settlement fee' or 'closure fee' on your statement, usually lands somewhere between $150 and $1,000. It’s a final step to clear the title of the property. Your conveyancer will coordinate it all, but the cost itself comes directly out of your settlement funds.
To help you keep track of these initial expenses, here’s a simple checklist breaking down what you can expect to pay.
Your Pre-Sale Preparation Costs Checklist
This table provides a breakdown of common upfront expenses to prepare your property for the market, with typical cost estimates for the Sydney region.
| Preparation Item | Typical Cost Estimate (AUD) | Purpose and Importance |
|---|---|---|
| Pre-Sale Building & Pest Report | $400 – $800 | Increases buyer confidence and can accelerate the sale process. |
| Strata Report (Units/Townhouses) | $300 – $450 | A mandatory-read for apartment buyers; shows financial health of the building. |
| Minor Repairs & Cosmetic Fixes | $500 – $3,000+ | Addresses buyer concerns, improves first impressions, and protects your sale price. |
| Mortgage Discharge Fee | $150 – $1,000 | The administrative cost charged by your bank to formally close your home loan. |
Actionable Tip: Don't leave this to the last minute. Get ahead by calling your bank to confirm their exact mortgage discharge fee. At the same time, start getting quotes for any reports or small repairs you might need. A well-prepared property isn’t just more desirable—it’s more valuable.
Understanding Capital Gains Tax on Property
For anyone selling a property, especially an investment, Capital Gains Tax (CGT) can be the elephant in the room. It’s often the single biggest cost you’ll face, and it’s not just another line item on a settlement statement. It’s a tax on the profit you’ve made, and if you’re not prepared, it can take a serious bite out of your final proceeds.
Think of it like this: the Australian Taxation Office (ATO) wants to know how much profit you made on your property journey. To figure that out, they look at what you sold it for versus what it cost you to buy and own. This is where it gets a little more detailed than just a simple subtraction.
Calculating Your Capital Gain
Your capital gain isn't just the sale price minus the purchase price. The real calculation is a bit more involved, and understanding both sides of the equation is the key to getting it right.
Capital Proceeds: This is the gross sale price you achieved, but you get to subtract the direct costs of selling. Think of things like your agent's commission, the legal fees for the sale, and what you spent on that marketing campaign.
Cost Base: This starts with the original price you paid for the property. But it also includes other costs you incurred along the way that you haven't already claimed a tax deduction for. This is crucial. It can include the stamp duty you paid at purchase, your legal fees back then, borrowing expenses, and even major improvements like that new kitchen or deck you added.
Let's put it into practice:
Imagine you bought an investment property in Ashfield ten years ago for $700,000. You spent $50,000 on a big bathroom renovation and originally paid $20,000 in stamp duty and legal fees. All up, your cost base is $770,000.You just sold it for $1,200,000. Your selling costs (agent, legal, marketing) came to $50,000. That means your capital proceeds are $1,150,000.
Your total capital gain is $380,000 ($1,150,000 – $770,000).
The Main Residence Exemption and CGT Discounts
Now for the good news. Not every sale automatically comes with a tax bill. Australian tax law offers some powerful ways to reduce or even completely wipe out your CGT.
The most important one by far is the main residence exemption. Put simply, if the property you’re selling has been your family home for the entire period you've owned it, you generally won’t pay a cent of CGT on your profit. It’s that simple. But—and this is a big but—the rules get very complex if you’ve ever rented it out, used part of it to run a business, or if it hasn't always been your primary home.
The ATO has very specific rules about what qualifies for a full or partial exemption.
As you can see, the details matter. For a full breakdown of how these rules might apply to your own history with the property, it's worth reviewing the official guidance on the ATO website.
For investment properties that don’t qualify, there’s another huge benefit: the 50% CGT discount. If you've owned the property for more than 12 months, you only have to pay tax on half of your capital gain.
Let’s go back to our example. The $380,000 gain would be instantly halved to $190,000. This discounted figure is then added to your taxable income for that financial year and taxed at your personal marginal rate. It makes a massive difference.
The Power of Professional Tax Advice
As you can tell, CGT isn't exactly straightforward. The difference between a well-planned sale and a rushed one can easily mean tens or even hundreds of thousands of dollars in your pocket versus the ATO's.
This is exactly why getting professional advice before you even think about listing is one of the smartest moves you can make.
A specialist property tax accountant can:
- Accurately calculate your cost base: They know every single expense you can legally add to your cost base to shrink your taxable gain.
- Navigate the main residence exemption: They can work through complex scenarios, like if you moved out for a few years, to see if you still qualify for a partial or full exemption.
- Help structure the sale for the best outcome: They can advise on timing and ownership to legally minimise your tax hit.
Trying to DIY your CGT calculations is a huge financial risk. A chat with an expert like EndureGo Tax turns a potential headache into a clear, predictable part of your selling plan. It ensures you keep as much of your hard-earned profit as you possibly can.
For a deeper dive into these strategies, check out our specialist article on how to approach the selling of your home and Capital Gains Tax.
Your Top Questions About Selling Costs, Answered
When it comes to selling your home, the numbers can feel a bit overwhelming. We get it. Here are some straightforward answers to the questions we hear most often, designed to give you clarity and confidence.
Can I Negotiate the Agent's Commission?
You bet. The agent's commission is one of the biggest fees for selling a house, and it's almost always negotiable. It’s smart to chat with at least three different agents. This isn’t just about comparing their rates; it’s your chance to weigh up their marketing plans, how well they know your area, and their track record of recent sales.
Don't get fixated on finding the lowest percentage. A top-notch agent who lands you a higher sale price, even with a slightly higher commission, usually puts far more money in your pocket.
Think about it this way: an agent on 2.2% who sells your home for $1.4M gets you a better result than an agent on 1.8% who only manages a $1.35M sale. The better agent's real value is in the final number they achieve for you.
Do I Have to Pay for Marketing Upfront?
In most cases, yes. The majority of real estate agencies will ask for marketing costs to be paid upfront. This makes sense, as it covers the immediate outlay for things like professional photography, getting your listing onto the major online portals, and printing that all-important signboard.
That said, some agents are more flexible and might offer an arrangement where these costs are simply taken out at settlement. Always ask about the timing and make sure whatever you agree on is clearly stated in your agency agreement before you sign anything.
How Can I Keep My Selling Costs Down?
The best way to trim the fees for selling a house is to be proactive and do your homework. A little effort here goes a long way.
- Negotiate the Commission: Look for the best value, not just the lowest rate. Compare what each agent brings to the table.
- Choose Your Legal Rep Wisely: For a straightforward sale, a conveyancer with a competitive fixed fee is often the most cost-effective choice.
- DIY Where It Counts: You can save a lot on pre-sale prep by handling small, high-impact cosmetic touch-ups yourself. A fresh coat of paint or some garden TLC can work wonders.
- Get Smart with Tax: To properly get your head around the tax side of things, particularly the profit you might make, it's worth checking out resources for understanding Capital Gains Tax on property. Speaking with a tax pro early on is the key to legally minimising any potential CGT hit.
At EndureGo Tax, we live and breathe property tax. Our job is to make sure your financial setup lets you keep as much of your hard-earned profit as possible. Let our expert team in Ashfield and Belrose Northern Beaches give you the clarity you need. Book your consultation at https://www.endurego.com.au.
