


You’ve registered a company. The ABN is sorted. The logo is live. Your invoices are going out. Then someone refers to you as a company director, and that title sounds more formal than the way most small businesses run day to day.
That’s where many tradies, consultants, and local business owners get caught. They’re excellent at the work. They know quoting, staff, suppliers, and customers. What they haven’t had explained properly is that becoming a director creates legal duties that sit on top of the business itself. Those duties don’t disappear because your accountant lodges returns or your bookkeeper reconciles the bank.
A lot of confusion around director responsibilities Australia comes from the gap between legal theory and real business admin. The law talks about good faith, care, diligence, and solvency. Meanwhile, your actual risk often starts with late BAS, stale ASIC details, missing records, or signing things you haven’t reviewed.
If you’ve only recently become a director, it’s worth understanding the importance of registering for your Director ID. It’s one of the first practical signs that the role is personal, ongoing, and traceable.
So You’re a Director What Does That Actually Mean
A common example is the electrician who sets up a company because the business is growing. The company signs the lease, hires an apprentice, buys a ute, and opens a trade account with suppliers. On paper, that structure looks neat and professional. In practice, the owner is still making fast decisions between site visits, payroll, and chasing payments.
That owner usually thinks, “The company owes the money, not me.” Sometimes that’s partly true. But a director’s role isn’t passive. Under Australia’s company law framework, directors carry legal obligations about how the company is run, what risks are supervised, and whether the business keeps trading when it shouldn’t.
The title carries personal responsibility
In Australia, the key legal framework is the Corporations Act 2001, and ASIC says directors must act in the best interests of the company and shareholders while ensuring the company operates legally and ethically, as set out in ASIC’s guidance on obligations of company officeholders.
That sounds broad, but the practical meaning is simple. If you’re a director, you’re expected to supervise the business properly. You can delegate tasks. You can’t delegate responsibility.
Practical rule: If a regulator, liquidator, or court asks who was meant to make sure the company was meeting its obligations, “my accountant handles that” won’t be enough.
What new directors usually get wrong
Most new directors don’t fail because they’re dishonest. They fail because they treat directorship like a title instead of a job.
Typical mistakes include:
- Assuming compliance is automatic: ASIC forms, annual review tasks, and company register updates still need active oversight.
- Signing without reviewing: Financial statements, loan documents, and contracts need more than a quick glance.
- Ignoring early warning signs: Late tax lodgements, overdue super, and supplier pressure often show up before a bigger problem does.
- Confusing ownership with governance: Just because you own the business doesn’t mean you can treat company money and personal money as interchangeable.
If you understand that early, you’re already ahead of many small business directors.
The Four Core Statutory Duties You Must Uphold
The legal language can sound heavier than it needs to. For most SME owners, these duties boil down to one idea. Run the company with the same discipline you expect from a competent operator in your own trade.
The structure starts with the Corporations Act. In practice, four duties matter most in everyday decision-making.
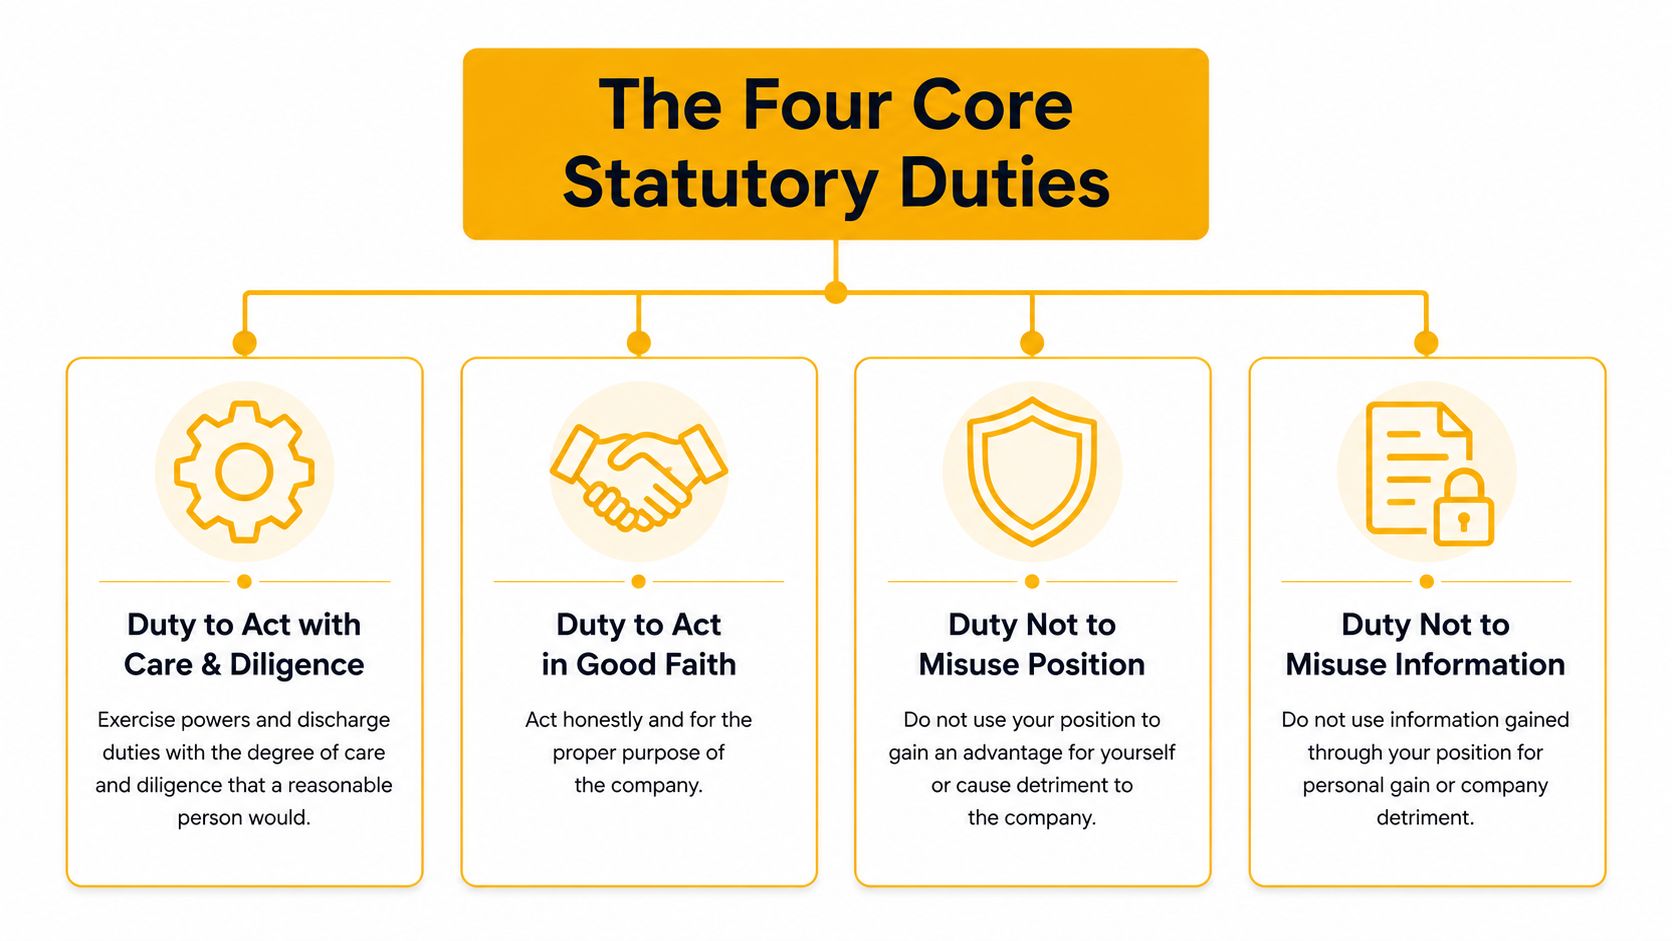
Duty to act with care and diligence
This is the “reasonable person” standard applied to directors. You’re expected to exercise the level of care and diligence that a reasonable person would use in your position.
For a small business owner, that means staying across the basics:
- Reviewing current numbers: Not just checking the bank balance, but looking at cash flow, debtors, creditors, wages, and tax liabilities.
- Understanding key commitments: Finance agreements, leases, guarantees, and major supplier terms can’t sit in a drawer unread.
- Asking questions early: If payroll looks tight or margins are slipping, you need to push for answers while there’s still time to act.
A builder wouldn’t sign off on a slab without checking the prep. Directors need the same mindset with company decisions.
Duty to act in good faith and for a proper purpose
A director must act in good faith and for the company’s benefit, not for a personal side agenda. That’s one of the central pillars of Australian corporate governance.
A practical example helps. Say the company has limited cash, and you decide to pay back a mate before paying a critical supplier because you’d rather preserve that personal relationship. That decision may feel harmless. It may still be the wrong decision if it isn’t made in the company’s interests.
What works is straightforward:
| Situation | Risky approach | Better approach |
|---|---|---|
| Tight cash flow | Pay whoever you personally want to keep happy | Prioritise based on the company’s actual obligations and solvency |
| Major purchase | Buy an asset because you like it | Assess whether the company can afford it and whether it serves the business |
| Business opportunity | Divert it to yourself personally | Consider whether the opportunity belongs to the company |
Duty to avoid conflicts and disclose them
Conflicts of interest don’t only happen in listed companies. They happen constantly in small business.
Your spouse owns a marketing business. Your brother has a concreting crew. You own the warehouse personally and want the company to lease it. None of those arrangements is automatically prohibited. The problem starts when the conflict isn’t recognised and properly disclosed.
Under section 181, directors have a strict fiduciary duty, and under section 191, failing to disclose a conflict can trigger serious consequences. ASIC’s corporate governance guidance notes that the duty applies to all directors, including non-executive or de facto directors, and non-disclosure can lead to civil penalties up to $1,110,000 or criminal sanctions in the circumstances described in ASIC’s corporate governance guidance for directors.
If a deal would look awkward when written into board minutes, treat that as a warning sign and slow down.
Duty not to misuse your position or information
You can’t use your role to gain a private advantage or cause detriment to the company. You also can’t use information you learned as a director for personal gain.
That matters in small companies because lines blur easily. A director might treat a customer lead, supplier pricing, or company funds as “basically mine”. Legally, that’s dangerous territory.
For directors who also manage risk more broadly, it helps to think in the same disciplined way used in preventing E&O lawsuits. Good process, clear records, and documented decisions often matter as much as intent.
Your Obligations to ASIC and the Tax Office
Many directors often find themselves surprised. They understand the high-level duties, but they miss the recurring admin that proves whether they’re supervising the company properly.
The company doesn’t stay compliant by accident. Someone has to monitor dates, forms, records, and tax payments. If you’re the director, that someone is still you, even when a bookkeeper or accountant helps.
ASIC tasks you can’t ignore
CPA Australia notes that directors are responsible for paying ASIC fees, responding to the annual company review statement, notifying ASIC of changes, and ensuring taxes and superannuation liabilities are paid on time. Breaches can lead to criminal penalties of up to 15 years’ imprisonment and civil penalties of up to $1,100,000, as explained in CPA Australia’s company director duties checklist.
That matters for simple tasks many owners overlook:
- Company annual review: Don’t let the review statement sit unopened in your inbox or mail.
- ASIC fee payment: Missing it creates unnecessary compliance trouble.
- Change notifications: If your address, officeholders, or share details change, ASIC needs to be told. In many cases, that means lodging Form 484.
- Registers and details: Company records need to match reality, not what was true two years ago.
A practical approach is to keep one compliance calendar that covers ASIC review dates, BAS due dates, super due dates, payroll reporting, and any annual governance actions.
Director ID and traceable accountability
Your Director ID is not a one-off admin nuisance. It reflects a basic principle. The role of director attaches to a real person, not just to a company file.
If you’re also worried about unpaid tax and the personal exposure that can follow, this guide to director penalty notice issues in Australia is worth reading alongside your broader compliance review.
Tax obligations need active supervision
Directors often assume the tax side is “with the accountant”. The better view is this: the accountant can prepare and lodge. The director must still make sure the company is funded, organised, and acting on time.
For practical risk management, pay close attention to:
- PAYG withholding: If wages are being paid, withholding obligations need to be reported and paid properly.
- Superannuation: Super can’t be treated as optional cash flow relief.
- BAS and lodgements: Late BAS often indicates deeper record-keeping or cash flow problems.
- ATO correspondence: Letters ignored today tend to become harder problems later.
If you need a plain-English explanation of personal exposure around tax debts, LemonAide director penalty help gives a useful overview of how those notices work.
Bottom line: A bookkeeper enters data. An accountant advises. A director must make sure the company actually complies.
For legislation and administrative guidance on tax and super obligations, directors should also keep an eye on the Australian Taxation Office.
The Golden Rule Preventing Insolvent Trading
Of all the director duties, this is the one that keeps people awake at night once cash flow gets tight. It’s also the duty most likely to move from “theoretical legal issue” to “personal financial problem” very quickly.
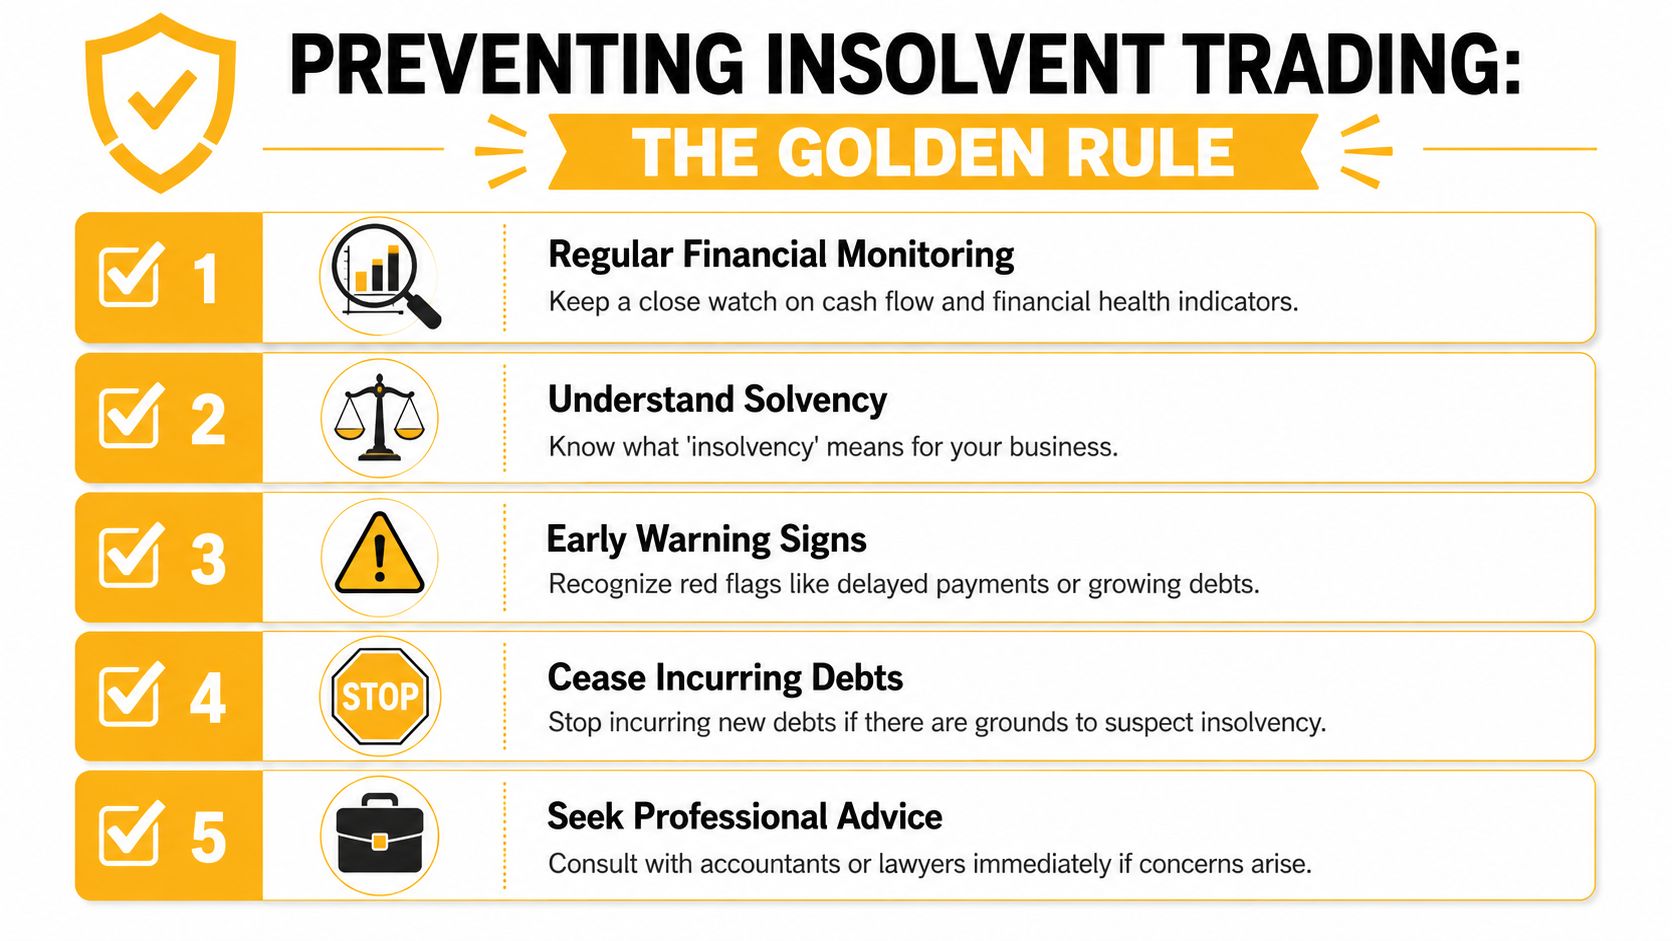
In practical terms, insolvency comes down to whether the company can pay its debts as and when they fall due. That’s a cash flow question, not a branding question and not a turnover question.
What insolvency looks like in a small business
You don’t need a formal insolvency report to spot danger. The signs usually show up in ordinary operations first.
Watch for patterns like these:
- Suppliers being paid late as routine practice
- ATO debts building while current trading continues
- Letters of demand or repeated creditor pressure
- Using one incoming payment to patch several older bills
- Wages or super becoming harder to fund
- No reliable, current financial reporting
A café, trade business, or consulting firm can look busy and still be insolvent. Busy isn’t the same as solvent.
The legal risk is personal
Directors must prevent insolvent trading under section 588G of the Corporations Act 2001. If the company incurs a debt while insolvent, and the director knew or ought to have known, the director can face personal liability for the entire debt, as outlined in ASIC’s guidance on insolvency for directors.
The phrase “ought to have known” matters. It means ignorance isn’t a reliable defence if a reasonable director would have recognised the warning signs.
A useful test is whether you could explain, with documents, what you reviewed and what actions you took when cash got tight.
What directors should do when red flags appear
The worst response is drift. Directors often keep trading because they hope the next job, the next contract, or the next quarter will fix everything. Sometimes it does. Often it doesn’t.
When solvency is in doubt:
- Get current numbers immediately
You need up-to-date accounts, aged payables, aged receivables, payroll obligations, and tax position. - Stop taking on fresh debt blindly
New purchases, fresh stock orders, or new finance commitments may deepen personal risk. - Document decisions
Record what information you relied on and what steps you approved. - Get restructuring advice early
Safe harbour under section 588GA can offer a potential defence, but only if a formal restructuring plan is implemented properly.
If the position is already severe, understanding the process around liquidating a company can help you make a cleaner and more defensible decision.
Early advice gives you options. Late advice usually gives you damage control.
Good Governance Starts with Good Record Keeping
This is the part most directors underestimate because it looks boring. It isn’t. Good record keeping is how a director proves care, diligence, and proper supervision in practice.
The Governance Institute highlights a gap that shows up constantly in SMEs. Many directors understand broad fiduciary duties, but fewer appreciate that they’re responsible for ensuring the company keeps adequate financial records, maintains ASIC registers, lodges Form 484 for changes, and passes annual solvency resolutions, as discussed in the Governance Institute’s guidance on directors’ duties.
What adequate records look like in practice
For a local business, adequate records usually mean systems that let you answer basic compliance questions quickly and accurately.
That often includes:
- Accounting software kept current: Xero, MYOB, or QuickBooks only help if bank feeds are reconciled and coding is reviewed.
- Payroll records that match reality: Wages, PAYG withholding, leave, and super need to tie back properly.
- Minutes for key decisions: Asset purchases, loans, director loans, and related-party arrangements should be documented.
- Corporate registers kept up to date: Director details, shareholder details, and company changes shouldn’t sit in old files.
- A solvency process: Annual solvency resolutions need proper attention, not last-minute signatures.
What doesn’t work
What fails in practice is informal management. A director says, “My bookkeeper knows what’s going on,” but no one can produce current reports. Or the accountant gets records long after year end, with key transactions missing and no notes explaining major decisions.
That creates exposure even where there’s no fraud and no bad intent. Poor records make it harder to show that you acted responsibly.
A useful shortcut is to standardise recurring documents. For directors who want a cleaner starting point for resolutions, minutes, and governance paperwork, AI legal assistant’s templates can help organise the paperwork side, provided the documents are reviewed properly for your circumstances.
Good governance in a small business usually looks ordinary. Current files, clean software, dated minutes, and a director who asks questions.
A Practical Compliance Checklist for Your Business
The simplest way to manage director responsibilities Australia is to build a repeatable routine. Directors get into trouble when compliance depends on memory, not process.
Use this as a working checklist for an SME, trade business, or local professional practice.
Monthly or quarterly
- Review cash flow: Don’t rely on turnover. Check what’s due out before the next major receipts arrive.
- Read the profit and loss and balance sheet: You don’t need to love accounting. You do need to spot unusual movements.
- Check ATO lodgements and payments: BAS, PAYG withholding, and super should be current or actively managed.
- Review aged debtors and creditors: Slow-paying customers and overdue suppliers often reveal stress early.
- Confirm payroll is clean: Make sure wages, super, and STP reporting align.
On major decisions
Before signing a lease, finance agreement, equipment purchase, or shareholder change:
- Ask whether the company can afford it
- Check whether there’s any conflict of interest
- Record the reasoning
- Make sure the company records are updated
Annually
A year-end governance review should cover:
| Annual task | Why it matters |
|---|---|
| Review financial statements | Helps confirm you understand the company’s position |
| Pass the solvency resolution | Shows active oversight of solvency |
| Complete ASIC annual review tasks | Keeps company details and fees current |
| Review registers and officeholder details | Reduces avoidable ASIC issues |
| Check tax and super history | Identifies unpaid liabilities before they grow |
If your current system is “my accountant will tell me if something is wrong”, tighten it. A director should have a standing review process, not just a hope-based one.
When to Seek Expert Help in Ashfield and Northern Beaches
A common small business scenario goes like this. The bookkeeper handles payroll, the accountant does the BAS and tax return, and the director assumes the admin side is covered. Then a finance application, overdue super, an ASIC notice, or a supplier payment plan forces the issue. That is usually the point where directors realise there is a gap between having advisers and meeting their own duties.
For local builders, tradies, consultants, and family businesses, the risk is rarely one dramatic event. It is the pile-up of ordinary things that were left too long. Company details are out of date. Tax debts are being carried month to month. A new business partner comes in without the paperwork being cleaned up properly. The company keeps trading because work is still coming through, even though cash is getting tighter.
Get advice early if any of these situations sound familiar:
- You have started a company but are still unclear on who is responsible for ASIC, tax, payroll, and record keeping
- The company can pay some bills, but you are delaying ATO, super, or key suppliers to manage cash flow
- You are about to sign finance, a lease, a shareholder change, or a large equipment purchase without current numbers in front of you
- You have received ASIC or ATO correspondence and are unsure whether it is routine or a warning sign
- Your accountant prepares the reports, but no one is sitting down with you to explain what they mean and what action is needed
- You are asking whether the business should keep trading, restructure, or be wound down before debts grow further
The trade-off is simple. Early advice costs time and fees now. Delayed advice usually costs more, gives you fewer options, and can leave you making decisions under pressure.
If you are in Ashfield, the Inner West, Belrose, or the Northern Beaches, practical help matters more than generic commentary. You want someone who can look at the numbers, the lodgement position, the company records, and the immediate risks, then tell you what needs attention first.
If you want practical help with company compliance, ASIC obligations, tax risk, or director issues before they escalate, speak with EndureGo Tax. As your trusted local accountant in Ashfield and Belrose Northern Beaches, they can help you stay organised, meet your obligations, and make better decisions with more confidence.
