


The Common Reporting Standard (CRS) is a global agreement between tax authorities to automatically share financial information. Developed by the Organisation for Economic Co-operation and Development (OECD), it's an international transparency framework designed to combat offshore tax evasion.
For everyday Australians, this means the Australian Taxation Office (ATO) now has a clear line of sight into financial accounts held by Australian tax residents in other participating countries. As an expert in international tax law, this guide will provide you with practical insights and actionable advice for navigating your CRS obligations.
Understanding the Common Reporting Standard
Think of the Common Reporting Standard as a secure, worldwide network enabling tax agencies to systematically exchange data. It was established to prevent individuals and businesses from stashing assets and income in offshore accounts to evade their tax obligations. The core purpose was to enhance transparency within the global financial system and clamp down on practices like opening offshore company and bank accounts for illicit purposes.
Before the CRS, if the ATO required information, it had to submit a specific, formal request to a foreign tax authority. This process was often slow, cumbersome, and inefficient. Now, that exchange is automatic and governed by a clear set of international rules.
The OECD's Role in Global Tax Transparency
The Organisation for Economic Co-operation and Development (OECD) is the driving force behind the CRS. It developed the standard to create a level playing field, ensuring financial institutions worldwide adhere to the same rulebook.
This global standardisation is the linchpin of the system. It means a bank in Switzerland, a fund manager in Singapore, and an insurer in the Cayman Islands are all collecting and reporting information consistently. The OECD’s framework ensures that this data flows smoothly and securely between more than 100 participating jurisdictions.
This cooperation provides a massive boost to the integrity of Australia’s tax system. Why? Because it makes concealing offshore financial activities significantly more difficult.
Core Objectives of the CRS
At its heart, the goal of the Common Reporting Standard is simple: increase tax transparency and discourage tax evasion. It achieves this through several key objectives:
- Automatic Information Exchange: Financial institutions report data to their local tax authority. That authority then automatically transmits it to the relevant tax agencies in other participating countries.
- Standardised Reporting: It prescribes precisely what information must be collected and how it should be shared, creating consistency across borders.
- Enhanced Compliance: With this unprecedented level of visibility, the CRS compels taxpayers with offshore accounts or investments to voluntarily comply with their tax obligations.
Practical Example: An Australian resident earns interest from a bank account in Germany. The German bank reports this to the German tax authority, which then automatically sends the information to the ATO. The ATO can then verify if this income was declared on the individual’s Australian tax return.
Ultimately, the CRS is a critical piece of the global financial puzzle, impacting both financial institutions and any individual with international financial ties. Understanding its mechanics is the first step towards ensuring your compliance.
If you hold overseas accounts or investments, it's crucial to ensure your affairs are in order. Contact EndureGo Tax today to discuss your cross-border financial obligations and achieve peace of mind.
Who Gets Caught in the CRS Net in Australia?
The Common Reporting Standard (CRS) casts a wide net, but the primary compliance burden falls on a specific group known as Reporting Financial Institutions (RFIs). This definition is far broader than just the major banks.
In Australia, an RFI is typically any entity fitting into one of four key categories. If your business manages client funds or investments, it’s vital to understand your classification.
Are You a Reporting Financial Institution?
The term ‘RFI’ might seem like technical jargon, but it breaks down quite logically. It generally includes:
- Depository Institutions: This is the most obvious category, covering everyday banks, credit unions, and building societies—any institution that accepts deposits.
- Custodial Institutions: These are businesses holding financial assets for the accounts of others. Think of custodians, nominee companies, or brokerage firms. If a substantial part of your business involves holding assets for clients, you likely fall into this category.
- Investment Entities: This category captures businesses that primarily trade financial assets, manage individual portfolios, or otherwise invest funds on behalf of others. A wealth management firm in Sydney, for instance, would almost certainly be an RFI. Even certain family trusts can be captured if their income is predominantly from financial assets and they are managed by another RFI.
- Specified Insurance Companies: This is a specific classification for insurance companies that issue cash value insurance or annuity contracts.
If your organisation ticks any of these boxes, you have legal obligations under the Common Reporting Standard. Compliance is not optional.
What Makes an Account 'Reportable'?
Once an entity is identified as an RFI, its next duty is to identify which of its accounts are ‘Reportable Accounts’. This is determined by identifying the ‘Reportable Person’ associated with the account.
So, what is a Reportable Person?
A Reportable Person is an individual or entity that is a tax resident of a foreign jurisdiction participating in the CRS framework.
This is precisely why your bank now requests your tax residency details whenever you open an account. It is not administrative red tape; it is a legal requirement driven by CRS. The ATO has clear guidelines for determining tax residency.
This screenshot from the ATO's website shows the main tests they use.
As you can see, the ATO uses tests like the 'resides test' and the 'domicile test' to establish where your tax obligations lie. The information gathered by RFIs facilitates the ATO's data exchange with tax authorities worldwide.
For instance, if you are an Australian tax resident but also hold residency elsewhere, your tax situation can be complicated, affecting how the foreign resident capital gains tax in Australia applies to you.
The Australian Taxation Office (ATO) is incredibly strict about this. Financial institutions must submit their reports by 31 July each year in a specific digital format. The ATO then validates every file to ensure it is technically perfect before acceptance. There is no room for error, and authorities are cracking down hard on non-compliance.
Meeting Your Due Diligence and Reporting Obligations
For Australian Reporting Financial Institutions (RFIs), staying compliant with the Common Reporting Standard is not a passive task. It is an active, ongoing process of meticulous due diligence and precise reporting that must meet the ATO's stringent requirements.
This process involves two key stages. First, you must identify which of your accounts are reportable. Second, you must gather the correct information and submit it on time.
The entire process begins with identifying "reportable accounts." This requires examining both new and existing accounts to determine the tax residency of every account holder. This is not a one-off check at account opening—it is a continuous obligation.
The Role of Self-Certification
So, how do you determine a client's tax residency? The primary tool in your arsenal is the self-certification form.
Whenever a new individual or entity opens an account, you must obtain a completed self-certification form. This is the official document where the account holder declares their country (or countries) of tax residence. It is non-negotiable. Without a valid self-certification, you cannot accurately determine if an account falls under the Common Reporting Standard. This document is your evidence of due diligence.
This simple flow chart illustrates the process, from identifying the institution to flagging a reportable person.
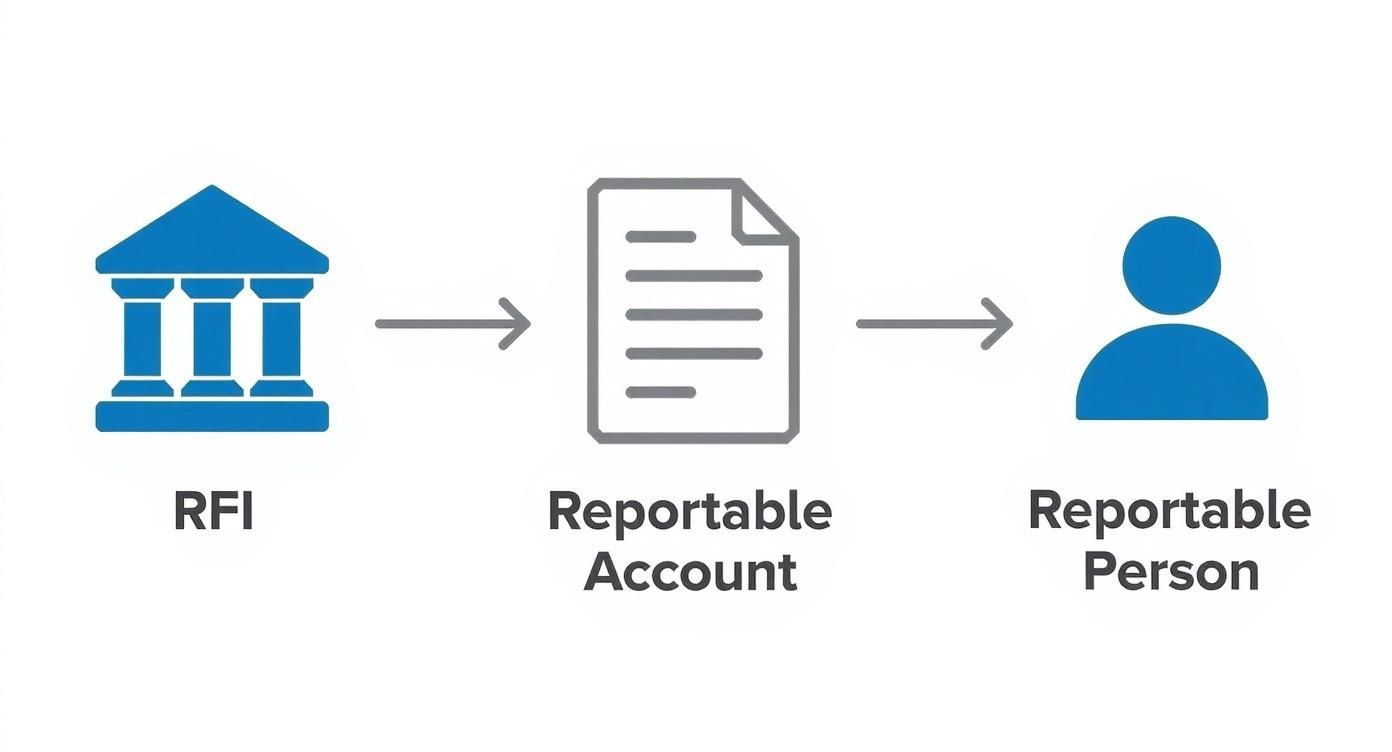
As you can see, the process moves logically from the RFI itself to the specific accounts and individuals who fall under the CRS net.
Key Data Points for ATO Reporting
Once you have flagged a reportable account, you must collect and report a specific set of information to the ATO. There is no room for approximation; the data must be precise.
Here’s what the ATO requires:
- Personal Details: The account holder’s full name, current address, and date of birth.
- Jurisdiction of Residence: The country (or countries) where they are a tax resident.
- Taxpayer Identification Number (TIN): The unique number issued by their home tax authority. For Australians, this is their Tax File Number (TFN).
- Account Details: The account number or an equivalent unique identifier.
- Financial Information: The account balance or value at the end of the calendar year, plus the total gross interest, dividends, and other income paid into the account during that year.
It is absolutely critical that this data is accurate and complete. Incomplete or incorrect reporting can lead to substantial penalties from the ATO and may force a costly remediation project to correct and resubmit the data.
Maintaining meticulous files isn’t just good practice; it is a core governance duty. You can learn more about general obligations in our detailed guide on record-keeping requirements in Australia. For those with international financial interests, understanding these rules is particularly vital when considering moves like opening an offshore company and bank account in the UAE.
The Crucial 31 July Deadline
All this work culminates on one critical date. Australian RFIs must lodge their CRS report with the ATO by 31 July each year, covering the previous calendar year.
Missing this deadline is not an option and is a guaranteed way to attract regulatory scrutiny.
Feeling overwhelmed by your CRS obligations? Schedule a consultation with EndureGo Tax, and let our experts ensure your business stays fully compliant.
How CRS Actually Affects Australian Residents and Businesses
The Common Reporting Standard (CRS) is not an abstract set of rules confined to banking circles; it has real, tangible consequences for Australian individuals and businesses.
For individuals with any overseas financial footprint, the CRS has drawn back the curtain. The Australian Taxation Office (ATO) now has unprecedented visibility into foreign accounts and investments. This automatic flow of information means there is no margin for error—accurate and honest tax declarations are absolutely critical.
Simultaneously, Australian businesses, especially those classified as Reporting Financial Institutions, have had to undertake significant operational overhauls. This is not a minor paperwork adjustment. It involves deep system updates, redesigned client onboarding processes, and ongoing staff training to correctly identify and report on accounts held by foreign tax residents.
A Practical Example of CRS in Action
Let’s make this tangible. Imagine Sarah, an Australian citizen and tax resident, who spent five years working in Singapore. While living there as an expatriate, she opened a local savings account and a separate investment account with a Singaporean financial firm.
Before the Common Reporting Standard, the ATO might never have known about these accounts unless Sarah voluntarily declared the income on her Australian tax return.
Now, the process is entirely different. Here’s how the information flows today:
- Sarah’s Singaporean bank identifies her as an Australian tax resident, usually from the self-certification form she completed when opening the account.
- The bank reports her account details—including her name, address, Australian Tax File Number (TFN), account balance, and any interest earned—to Singapore's tax authority.
- Under the CRS agreement, Singapore’s tax authority automatically bundles this information and sends it directly to the ATO in Australia.
This simple, automated exchange gives the ATO a crystal-clear picture of Sarah's offshore financial activities. It can then cross-reference this data with her Australian tax return to check for discrepancies. This mechanism is central to protecting the integrity of our national tax system. If you're dealing with similar situations, it pays to understand the broader tax implications of cross-border money transfers.
What Gets Reported?
So, what exactly are financial institutions sending to the ATO? The data shared is specific and designed to give tax authorities a comprehensive view of an individual's financial position abroad.
Here is a breakdown of the key information exchanged under the CRS.
Information Exchanged Under the Common Reporting Standard
This table outlines the key data points that Australian financial institutions report to the ATO for exchange with other tax jurisdictions under the CRS.
| Data Point | Description | Example |
|---|---|---|
| Personal Information | Core identifying details of the account holder. | Full Name, Residential Address, Date of Birth. |
| Tax Identification | The unique identifier used for tax purposes in the person's country of residence. | Australian Tax File Number (TFN). |
| Account Details | The specific number identifying the financial account. | Account Number or unique identifying code. |
| Financial Institution | The name of the bank, fund, or institution holding the account. | "ABC Bank, Singapore Branch". |
| Account Balance | The total value of the account at the end of the calendar year. | Account balance as of December 31. |
| Income Earned | Gross amounts paid or credited to the account during the year. | Interest, Dividends, Royalties, Sale Proceeds. |
This detailed reporting leaves very little to the imagination, which is precisely the point. It’s all about creating a transparent global financial system.
Strengthening Australia's Tax System
The impact of this global information exchange is immense. Australia commenced its formal data exchange under the CRS framework in 2017, and the results speak for themselves.
The ATO's enforcement activities have since uncovered complex tax evasion schemes, leading to over 4,500 audits and more than 45 prosecutions. These agreements were already yielding hundreds of millions in adjusted tax, penalties, and interest even before full implementation. You can dive deeper into the legislative background by reviewing the official implementation details for the Common Reporting Standard.
Ultimately, the CRS means there are far fewer places to hide undeclared income and assets. For individuals, it underscores the importance of full disclosure. For businesses, it demands a robust and proactive compliance framework.
Navigating your international tax obligations can be a minefield. Book a consultation with EndureGo Tax to ensure your personal and business affairs are fully compliant with Australian law and you're not caught out.
A Practical Checklist for CRS Compliance
Navigating the rules of the Common Reporting Standard can feel overwhelming, but breaking it down into simple, actionable steps makes compliance much more manageable.
Whether you are a financial institution responsible for reporting, or an individual with overseas accounts, a clear checklist is your most effective tool. The objective is to be proactive, not reactive, and to steer clear of the serious penalties associated with non-compliance.
This guide lays out the concrete steps you need to take. For financial institutions, this means embedding CRS requirements into daily operations. For individuals, it's about maintaining clear and current records with every financial provider.
Checklist for Financial Institutions
Reporting Financial Institutions (RFIs) shoulder the primary burden of CRS implementation. Your internal processes must be watertight and capable of withstanding ATO scrutiny. Measure your systems against these key actions.
Lock Down Your Due Diligence: Your client onboarding process must include the mandatory collection of tax residency self-certification forms. This applies not just to new clients; you also need a documented process for reviewing and validating the residency status of all pre-existing account holders.
Train Your Team: Every client-facing employee must understand what the Common Reporting Standard is and why this information is being collected. They should be trained to identify potential red flags in self-certification forms and know when to escalate a case for review.
Keep Impeccable Records: You must maintain detailed records of every due diligence step taken for every account. This documentation is your proof of compliance and will be your defence in an ATO audit. As outlined in the Australian implementation of the Common Reporting Standard, these records are a fundamental legislative requirement.
Automate and Test Your Reporting: Managing your annual CRS report with manual data entry is a recipe for disaster. Invest in systems that can accurately extract and format the required data. Regularly test your reporting output to ensure it aligns with the ATO's specifications well before the 31 July deadline.
Checklist for Individuals and Entities
While financial institutions perform the reporting, individuals and entities with overseas accounts have a critical role to play. A passive approach can lead to significant complications.
Your primary responsibility is to provide accurate and truthful information to your financial institutions. An incorrect self-certification, whether intentional or not, may be treated as a false declaration, leading to serious issues with tax authorities in Australia and abroad.
Follow these practical steps to ensure you remain compliant:
- Keep Your Details Current: If your tax residency status changes—for example, you move overseas for work or return to Australia—you must notify all of your financial institutions immediately.
- Respond to Requests Promptly: When your bank or fund manager sends you a CRS self-certification form, complete and return it without delay. Ignoring these requests can lead to your account being flagged or even frozen.
- Get Professional Advice for Complex Setups: If you hold assets through complex structures like trusts or have financial ties to multiple countries, do not guess. Engaging a tax professional ensures your international affairs are structured and declared correctly from the outset.
Managing your Common Reporting Standard obligations doesn't have to be a nightmare. If you're unsure about any part of your cross-border tax situation, reach out to the experts at EndureGo Tax for a consultation. You'll get the confidence that comes with knowing your affairs are in order.
Got Questions About the Common Reporting Standard? We've Got Answers.
Even after understanding the fundamentals of the Common Reporting Standard, practical questions often arise. It's one thing to grasp the theory, but another to know what it means for your bank account or business.
Here, we tackle the most common questions from individuals and businesses across Australia in a direct, expert-led format.
What Happens If I Don’t Provide My Tax Residency Details?
Let’s be direct: ignoring a request from your bank for your tax residency information is a poor strategy. Financial institutions are not being intrusive; they are legally obligated under Australian law to collect this information via a self-certification form.
If you fail to respond, they cannot simply ignore the requirement. The likely outcomes are not favourable:
- Your Account Could Be Frozen: The institution may be required to restrict your account, preventing withdrawals or payments until you provide the necessary details.
- They Might Close Your Account: To mitigate their own compliance risk, the institution may choose to close your account altogether.
- They Will Report Based on Existing Information: The bank may be forced to report your account to the ATO using whatever information they currently hold. If that information is incomplete or incorrect, it could lead to difficult questions from the tax authorities.
How Is CRS Different From FATCA?
This is a common point of confusion. The Common Reporting Standard (CRS) and the Foreign Account Tax Compliance Act (FATCA) have similar aims—to combat tax evasion—but they are not the same.
The simplest way to differentiate them is: FATCA is a US law, while CRS is the global standard.
Here is a quick breakdown:
- FATCA: This is a United States law designed to identify U.S. taxpayers hiding money in offshore accounts. It compels foreign financial institutions (including Australian banks) to report information about their American clients to the U.S. Internal Revenue Service (IRS).
- CRS: This is a global standard developed by the OECD, with over 100 countries participating. It requires financial institutions to report on accounts held by tax residents of any participating jurisdiction back to that person's home tax authority.
Practical Example: An Australian bank reports an American client's account details to the IRS due to FATCA. The same bank reports the account details of its French, German, and Japanese clients to the ATO (for forwarding to their respective tax authorities) due to CRS.
What Are the Penalties for CRS Non-Compliance?
The Australian Taxation Office (ATO) takes compliance with the Common Reporting Standard extremely seriously. The penalties for non-compliance are severe, for both financial institutions and individuals.
For financial institutions, failing to collect information and report accounts correctly can result in massive administrative penalties. These fines can accumulate rapidly, especially in cases of systemic failure affecting numerous accounts.
For individuals, the consequences are equally serious. Deliberately making a false statement to a financial institution about your tax residency is a criminal offence. The legislation is unequivocal: this can result in heavy fines and even imprisonment. You can review the official legislation on the Australian government’s legislation register – this is serious business.
Navigating the world of the Common Reporting Standard and other international tax rules can be complex. That’s where expert guidance makes all the difference.
The team at EndureGo Tax provides clear, expert advice to ensure you are meeting all your obligations without the stress. Whether you are an individual with overseas investments or a business managing reporting duties, we are here to help you achieve compliance with confidence.
Book your consultation with our tax experts today and get the peace of mind you deserve.
