


You’re probably in one of two positions right now. Perhaps you’ve built a successful business in Sydney, Belrose, Ashfield, Adelaide, or the Inner West, and although you know it’s time to address business succession planning, you keep putting it off. Alternatively, someone may have asked you a deceptively simple question: “What happens to the business if you step away?”
Although the question seems straightforward, it often catches business owners off guard. After all, business succession planning involves far more than preparing for retirement. Instead, it determines who takes control of your business, how you protect family relationships, how you manage tax obligations and legal ownership, how you maintain employee confidence, and whether the value you’ve worked so hard to build remains intact after your departure.
Unfortunately, many business owners still treat succession planning as a task they can deal with later. However, delaying the process can create unnecessary risks. A well-structured succession plan influences your company structure, trust arrangements, capital gains tax (CGT) position, ASIC records, and the process of transferring ownership to a buyer, family member, business partner, or key employee. As a result, you can ensure a smooth transition instead of leaving your business to face uncertainty and disruption.
Your Life’s Work Is Not a Game of Chance
You’ve spent years building systems, winning clients, hiring staff, carrying risk, and probably backing the whole thing with your own name and cash. Yet plenty of owners still run their exit plan on hope. Hope that the kids will sort it out. Hope that a manager will buy in. Hope that a buyer will appear at the right time. Hope is not a strategy.
The hard truth is this. If you don’t decide how the business transitions, someone else will decide for you. That might be the ATO, a stressed family member, a buyer holding the upper hand, or a legal process that kicks in when illness, death, dispute, or burnout hits at the worst time.
There’s another reason this has moved from “important” to urgent. The ATO has declared succession planning and its associated tax risks its top focus in 2025, including scrutiny of Division 7A loan clean-ups via distributions, asset transfers within a group without proper value recognition, family interest restructures without commercial reasoning, and trust deed changes used to reallocate income or assets, according to this summary of the ATO’s 2025 focus.
That means sloppy restructures, rushed transfers, and backfilled paperwork are dangerous. If you move assets, rework trust control, or change ownership without evidence and commercial logic, you’re inviting trouble.
Practical rule: If your succession plan only starts when you’re tired, sick, or ready to sell, you’ve already left it too late.
Good succession planning protects three things at once:
- Your value: The business should transfer at a sensible value, not under pressure.
- Your family and staff: People need clarity about who’s in charge and what happens next.
- Your compliance position: Tax, trust, and company records must line up with the transaction.
If you own an SME, this isn’t a side issue. It’s one of the most important financial decisions you’ll ever make.
Start with the End in Mind Your Personal and Business Goals
Most succession plans fail before the tax work even starts. They fail because the owner hasn’t decided what “exit” means.
Do you want a clean sale and a hard stop? Do you want to keep some income coming in for a period? Do you want one child to run the business while another receives other assets? Do you want to hand control to a long-term employee? Those are different outcomes, and they need different structures.
 RemoveUploadDownloadRegenerateAsk AI
The problem is huge: 81% of Baby Boomer business owners have not completed a formal succession plan, creating a $3.5 trillion risk to the SME sector, and over 80% of Australian SMEs, worth about A$3.5 trillion, remain owned by these individuals, according to VUCA’s analysis of Australian succession risk.
Define your version of success
A good starting point is brutally simple. Write down your answers to these questions:
- What date matters most to you
Is there a target year to retire, slow down, or stop carrying operational responsibility?
- What do you want financially
Do you need a lump sum, staged payments, ongoing dividends, rent from retained property, or a mix?
- Who do you want involved
Family, business partner, senior staff member, external buyer, or nobody after handover?
- What role do you want after transition
Adviser, director, mentor, consultant, minority owner, or complete exit?
- What are you protecting
Family harmony, staff jobs, customer continuity, a brand name, commercial property, or all of it?
If you skip these questions, every later decision gets messy. Valuation becomes vague. Tax planning becomes reactive. Legal documents become patchwork.
Two practical examples
A plumber in Adelaide might want to sell to a leading hand who already knows the clients, systems, and team. That owner usually needs a staged buy-in plan, solid cash flow visibility, clear training, and documents that deal with risk if the employee can’t complete the purchase.
A family-run café in Ashfield might want to transfer control to one daughter who works in the business while treating another child fairly outside the business. That situation needs more than goodwill. It needs structure, role clarity, and careful ownership planning so resentment doesn’t blow up later.
The right successor is only part of the answer. The right outcome comes first.
What owners often get wrong
| Common mistake | Why it causes problems |
|---|---|
| Assuming the family already knows the plan | They usually know fragments, not the real plan |
| Mixing retirement goals with business needs | You end up underpricing, delaying, or forcing bad timing |
| Treating all children equally inside the business | Equal ownership and fair outcomes aren’t always the same thing |
| Waiting for “the right time” | The best planning happens before pressure arrives |
For small business owners, the first win in business succession planning isn’t a legal document. It’s clarity. Once your personal and business goals are written down, the rest of the work becomes practical.
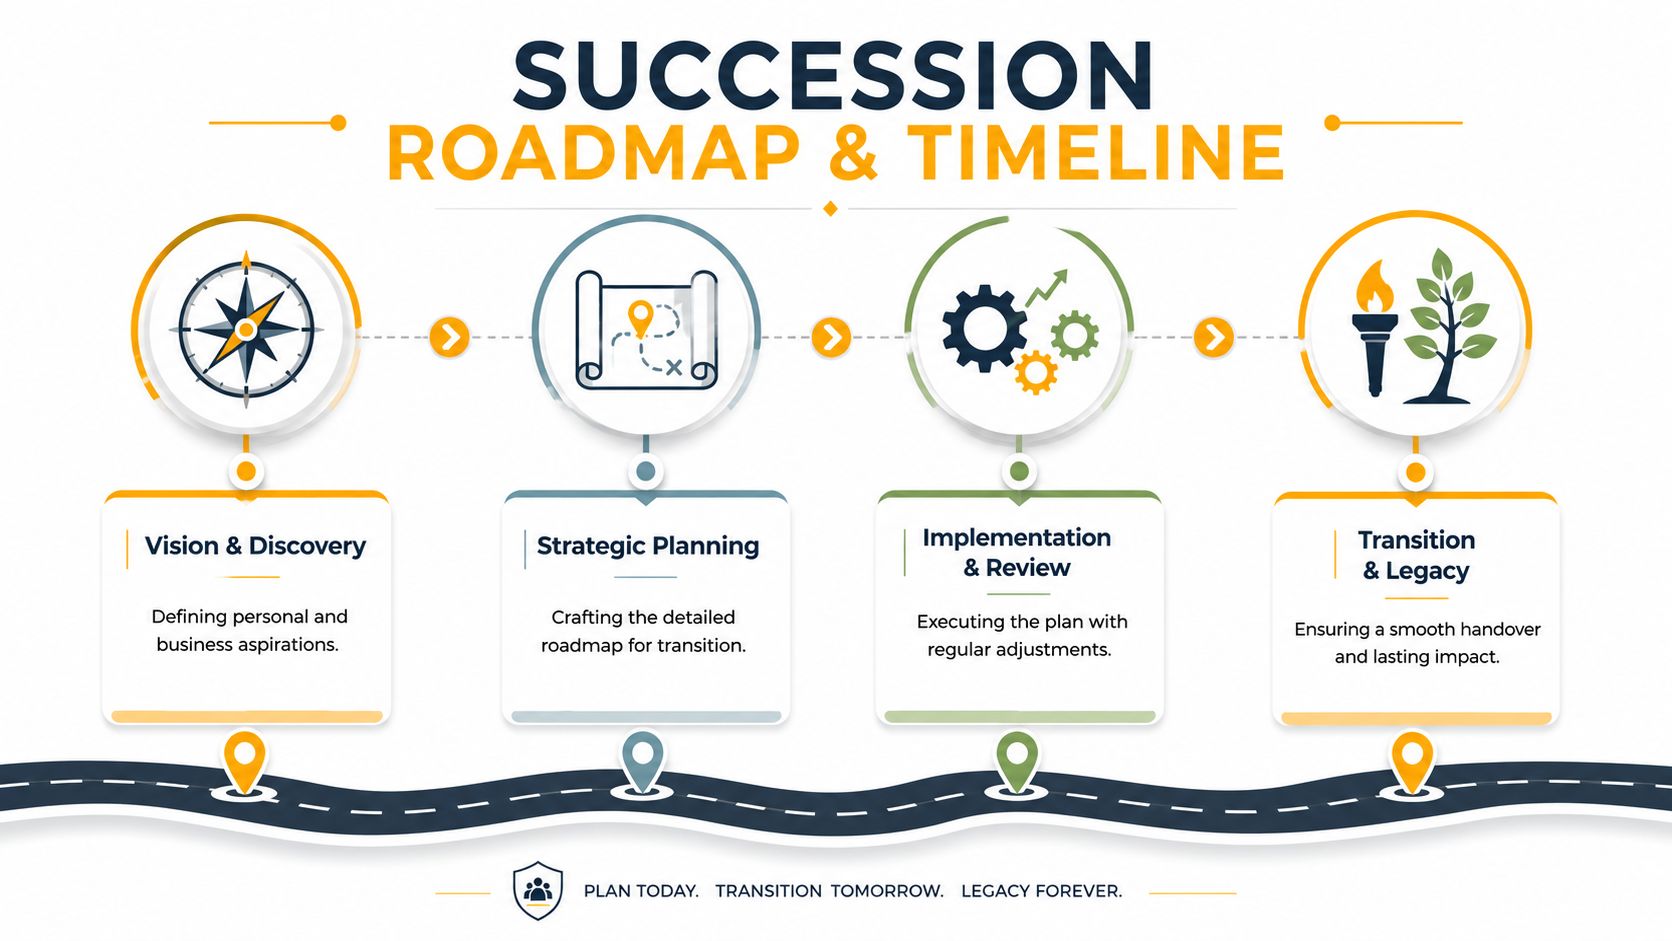
Building Your Succession Roadmap and Timeline
A succession plan without a timeline is just a nice intention. Owners say they want to transition “in a few years”, then nothing happens until an illness, dispute, or buyer enquiry forces the issue. That’s how value leaks out.
The better approach is to build a roadmap with milestones, responsibilities, and review points. Not a vague checklist. A working plan.
 RemoveUploadDownloadRegenerateAsk AI
The need for a documented roadmap is obvious. Only 13% of Australian family businesses successfully transition to the third generation, and businesses with structured, documented succession plans perform better than those relying on informal arrangements, according to BDO’s guidance on succession planning.
Choose the transition path early
There are usually three broad paths:
- Family transfer: Useful when a family member has the skill, interest, and credibility to lead.
- Internal succession: Often the best option for tradies, professional services firms, and owner-led businesses with a strong second-in-command.
- External sale: Best when there’s no suitable internal successor or when you want a clean exit.
Each path changes the documents, tax planning, and timeline. A child stepping into management needs development and governance. A key employee may need a staged equity path. An external sale requires stronger buyer-ready records and sharper valuation work.
If you’re comparing the mechanics of buying or selling a business, it helps to understand the transaction issues a buyer or seller will care about, especially contracts, due diligence, and risk allocation.
A successor isn’t chosen. They’re developed.
Owners often nominate the most loyal person rather than the most capable one. Loyalty matters. It’s not enough.
You need to assess whether the successor can handle:
- Commercial judgement: Pricing, margins, supplier negotiations, debtors.
- Leadership: Staff management, accountability, conflict, decision-making.
- Client trust: Can they keep key relationships steady through a transition?
- Operational discipline: Systems, compliance, reporting, and follow-through.
A practical development plan usually includes shadowing, staged responsibility, authority limits, and regular review. If your successor only starts running meetings six months before handover, you haven’t prepared them.
Owner test: If you disappeared for eight weeks, would the business run properly under your proposed successor? If not, keep developing them.
What a realistic timeline looks like
Below is a plain-English guide. It’s not legal advice, but it’s a sensible operating framework for Australian SMEs.
A longer runway
Around five years out
- Confirm your exit goal: Sale, family transfer, management handover, or hybrid.
- Review structure: Check whether the trust, company, shareholding, and control arrangements still make sense.
- Benchmark value: Get an early valuation and identify what drives or drags value.
- Pick likely successors: Don’t overcomplicate it. Narrow the field.
- Build capability: Delegate client ownership, management duties, and financial accountability.
The execution phase
Around two years out
- Tighten records: Financials, contracts, shareholder records, trust records, employment terms.
- Stress-test the successor: Give them bigger calls with visible accountability.
- Plan tax outcomes: Don’t wait until heads of agreement are drafted.
- Prepare communications: Family, staff, key clients, lenders, and advisers.
- Document contingencies: Death, illness, dispute, breakdown in the chosen succession path.
Roadmap mistakes that kill momentum
- Leaving the owner central to every decision
If every approval still runs through you, the business isn’t transition-ready.
- Confusing job title with readiness
Giving someone “General Manager” on a business card doesn’t mean they can lead.
- Ignoring weak spots
Buyers and successors both notice poor systems, owner dependence, and undocumented processes.
- Planning in private for too long
Confidentiality matters. Silence creates risk when key people need time to prepare.
Good business succession planning turns an emotional issue into a managed project. That’s the shift owners need to make.
Getting Your Business Valuation Right
A lot of owners pull a number out of the air and call it valuation. Usually it’s based on effort, sacrifice, or what they think the business should be worth. Buyers don’t care about your stress levels. The ATO doesn’t either. Valuation has to stand up commercially.
That’s why I’m firm on this point. A proper valuation is not optional in business succession planning. It drives negotiations, tax planning, fairness between family members, and the credibility of the whole transaction.
The best approach isn’t one valuation done in a panic at the end. Best practice requires a multi-stage valuation methodology, with an initial baseline early in planning, progress valuations as improvement strategies are implemented, and a final valuation close to execution, using asset-based, income-based, and market-based approaches, as outlined in this guide to succession valuation methodology.
The three main valuation lenses
| Method | Plain English meaning | Where it often fits |
|---|---|---|
| Asset-based | Adds up business assets and liabilities | Asset-heavy businesses, property-rich entities |
| Income-based | Looks at maintainable earnings and future cash generation | Service firms, trades businesses, operating companies |
| Market-based | Compares the business to comparable sales or market evidence | Businesses where relevant sale benchmarks exist |
A Northern Beaches construction company is a good example. Its plant, vehicles, and equipment matter, so asset value counts. But if the owner has recurring builder relationships and strong earnings, income matters more. If similar construction businesses have sold recently, market evidence also helps frame a reasonable range.
Why last-minute valuations go wrong
A rushed valuation often exposes issues you could’ve fixed earlier:
- customer concentration
- owner dependence
- messy wages or private expenses in the accounts
- outdated equipment values
- undocumented director or shareholder arrangements
- poor debtor collection
When you value the business early, you get time to improve those weak points before the final transaction.
A valuation should guide decisions, not merely justify a price you already want.
There’s also a practical benefit. Progress valuations let you see whether the business is becoming less reliant on you. If value only holds because you’re still the key rainmaker, succession isn’t working yet.
What to bring to a valuer
Don’t make a valuer guess. Prepare clean information:
- Financial records: Accurate year-end accounts and management figures
- Entity details: Company, trust, shareholding, and debt structure
- Contracts: Major customer agreements, leases, finance, supplier terms
- Adjustments: One-off expenses, private items, unusual events
- Operational context: Staff depth, systems, workflows, and client retention
For a broader grounding, these insights from The Owner’s Shortlist are useful if you want to understand how different small business valuation approaches are commonly framed before getting formal advice.
If you want your exit, family transfer, or buyout to hold together, get the valuation work done properly and do it early. Otherwise every negotiation starts in the wrong place.
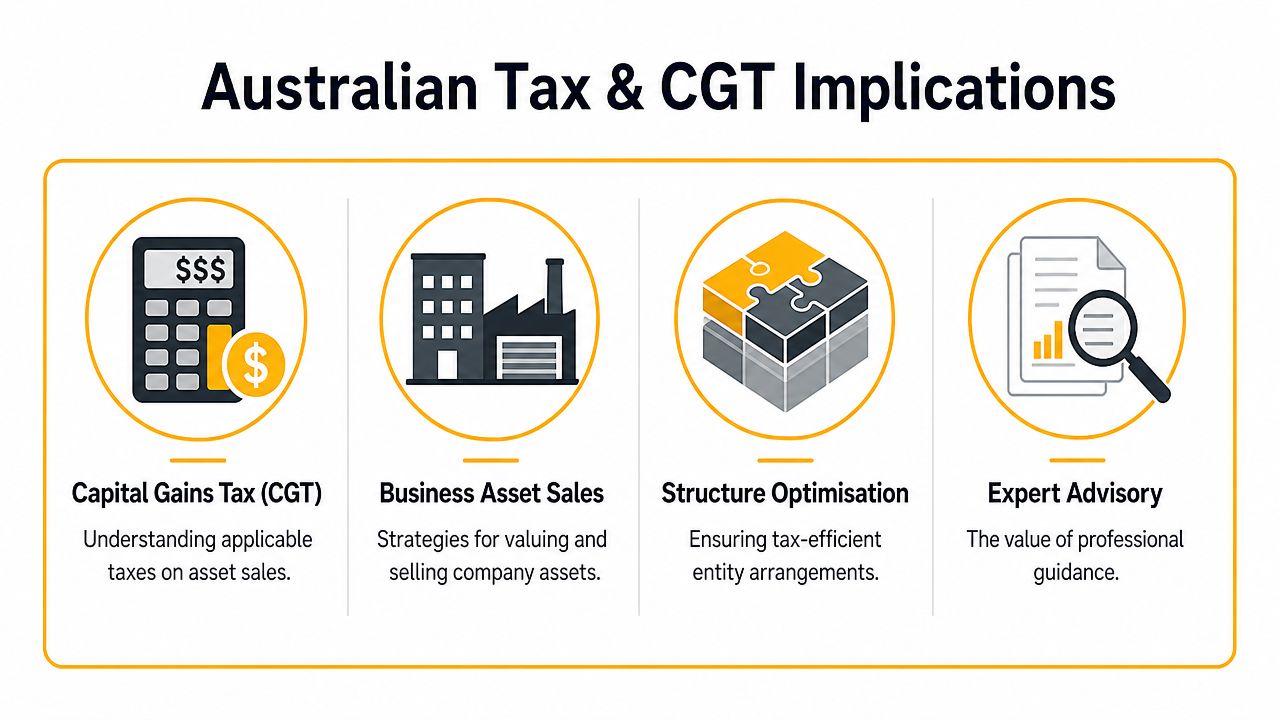
Navigating Australian Tax and CGT Implications
You agree a handover with your daughter, your manager, or an outside buyer. Everyone shakes hands on the deal. Then your accountant maps the assets and finds the goodwill sits in one entity, the trading stock in another, and an old trust still controls part of the business. That is when succession gets expensive.
Tax is set by structure first, not by good intentions at the end. In an Australian SME, the tax result will turn on who owns each asset, which entity is selling, how control shifts, what the valuation supports, and whether the paperwork matches the story.
 RemoveUploadDownloadRegenerateAsk AI
Start with the transaction you’re doing
“Sell the business” is too vague to plan around. You need to pin down the legal transaction first, because the tax treatment follows the legal form.
The outcome can differ sharply depending on whether you are:
- selling shares
- selling business assets
- transferring interests within a family group
- changing trust control
- moving assets between entities before the final exit
Each option creates a different CGT position, different documents, and different risk points. If you want a plain-English refresher before formal advice, this guide on how to calculate Capital Gains Tax for an Australian business sale gives a useful overview of the main moving parts.
Pre-CGT assets can still create tax problems
A lot of owners assume an older asset is permanently protected from CGT. That assumption can be wrong.
For pre-CGT assets held in a company or trust to keep their tax-free status during succession, the market value of post-CGT assets must stay below 75% of the entity’s net asset value immediately before disposal. If post-CGT assets go past that 75% threshold, CGT event K6 can apply to part of the proceeds, as explained in PwC’s discussion of pre-CGT assets and CGT event K6.
This catches families with old companies, inherited structures, and trusts that have changed character over time. Retained profits, new investments, business property, and internal restructures can all shift the tax position. If your group has been operating for years, check the asset mix before you assume a sale or transfer will be tax-free.
Old entities need a fresh review. Age alone does not protect you.
Documentation is what defends the tax position
Good tax advice is useless if the file cannot support it. If the ATO reviews the transfer, it will look at what happened on paper and whether the evidence lines up with the tax treatment claimed.
The CPA Australia guide to selling a business is a useful reminder that sale planning needs proper records, support for value, and clear legal documentation. That matters just as much in a family transfer or internal succession as it does in a third-party sale.
Keep evidence for:
- Valuation support: How the price or transfer value was reached
- Commercial rationale: Why the change happened and why the steps were taken in that order
- Legal steps: Minutes, agreements, trust deed amendments, share transfer forms, and resolutions
- Tax analysis: Working papers, cost-base calculations, and advice notes tied to the transaction
If you cannot explain the transaction clearly to your accountant, lawyer, and the ATO from the same set of documents, the plan is not ready.
Common tax mistakes in SME succession
Last-minute restructures
Owners decide to exit, then rush to move assets or change ownership just before the deal. That can limit available concessions and invite questions about purpose and timing.
Poor asset mapping
In many small businesses, the trading entity is not the same entity that owns the goodwill, equipment, premises, or intellectual property. Until you map that properly, no one can give you reliable tax advice.
Informal family transfers
A transfer to a son, daughter, spouse, or sibling still needs value support, legal documents, and a tax review. Family agreement does not replace tax law.
Unresolved trust and loan balances
Division 7A issues, unpaid present entitlements, beneficiary loan accounts, and old director loans can distort the transaction and create tax problems that should have been cleaned up years earlier.
Ask the tax questions early
You do not need to master every CGT rule. You do need the right questions on the table before any transfer starts.
| Tax question | Why it matters |
|---|---|
| Who legally owns the business assets and goodwill? | Determines what is being transferred |
| Are you selling equity or assets? | Changes the tax treatment and legal process |
| Do old structures include pre-CGT complications? | May affect whether gains stay exempt or become taxable |
| Is the valuation support strong enough to defend? | Helps support both price and tax treatment |
| Have trust and loan issues been reviewed? | Reduces the risk of avoidable ATO scrutiny |
Small business succession planning works better when tax, legal structure, and ASIC obligations are dealt with together from the start. That is the structure-first approach. It gives you more options, cleaner documents, and fewer nasty surprises after the deal is meant to be done.
Choosing the Right Trust or Company Structure
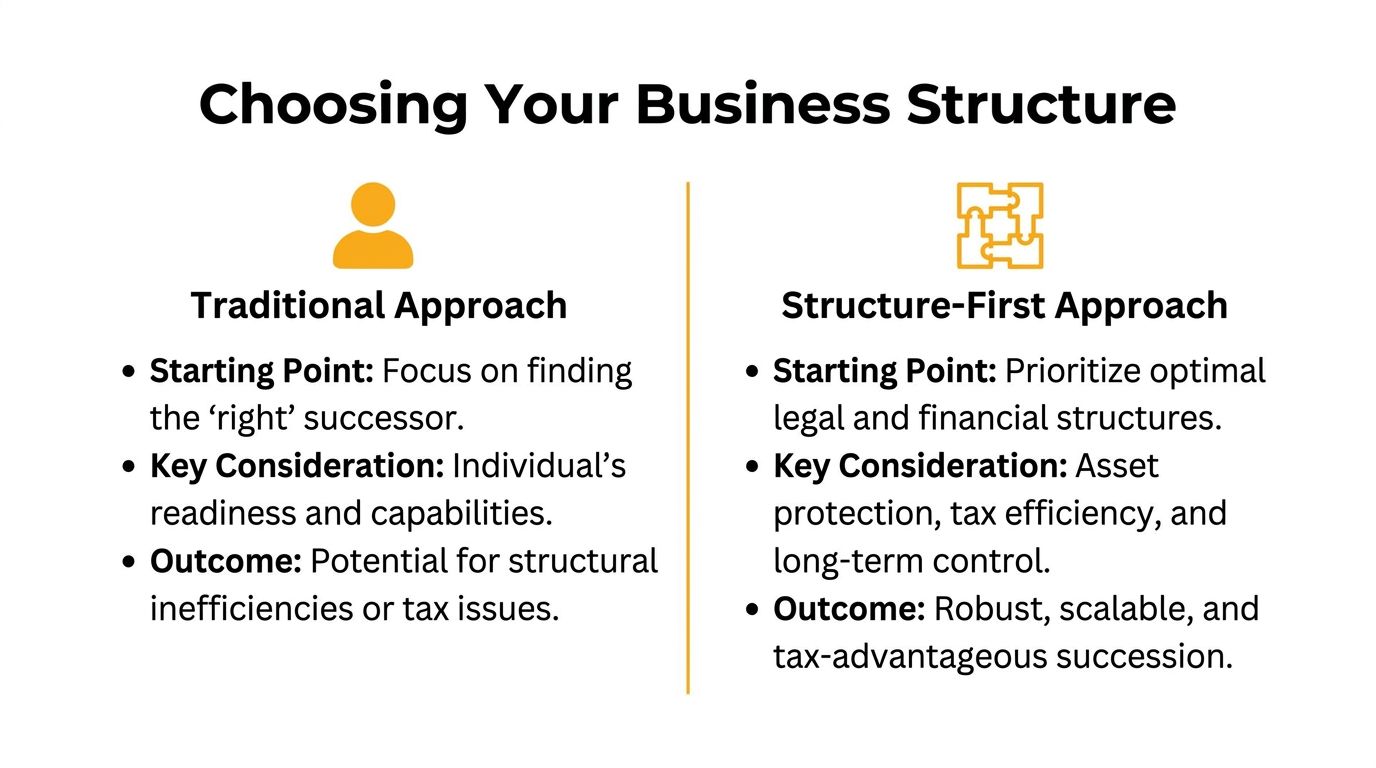
Most owners start succession by asking who should take over. I think that’s backwards. Start with the structure.
A poor structure can block a clean transfer, create tax friction, expose assets unnecessarily, and make family control harder to manage. That’s why the smarter approach is structure-first business succession planning.
This thinking is gaining traction. Many Australian family businesses are using succession planning to reassess whether their legal structure still works, and the stronger approach is to re-engineer tax and legal frameworks such as trusts and corporate layers before identifying successors, as discussed in this article on structure-first succession planning.
 RemoveUploadDownloadRegenerateAsk AI
Trust versus company for succession
There’s no universally “best” structure. There is only the structure that best suits your likely transition.
Here’s the practical comparison.
| Issue | Family trust | Company |
|---|---|---|
| Control | Control often sits with trustee and appointor arrangements | Control usually follows share ownership and director power |
| Flexibility | Can allow flexible family control planning if the deed supports it | Cleaner where ownership is divided into shares |
| Transfer process | Control can be less obvious to outsiders if documents are complex | Share transfers can be more straightforward in a sale |
| Family succession | Often useful where multiple family interests need balancing | Useful where ownership percentages need precision |
| Third-party sale | Can be workable, but structure may need review first | Often easier for external buyers to understand |
A family trust can work well where parents want to shift control over time, separate economic benefit from day-to-day management, or provide flexibility across children. But that flexibility only helps if the deed, trustee, appointor role, and control chain are all understood and current.
A company can be cleaner when you’re preparing for a sale to a third party, introducing investors, or staging equity ownership through shares. But companies can also carry historic issues, including messy shareholdings, undocumented arrangements, or assets that shouldn’t be trapped in the same entity.
For a practical comparison of the trade-offs, this breakdown of family trust vs company is a useful reference point.
Questions to ask before you keep your current structure
Does the structure match the exit path
If you want a future sale, is the current entity sale-friendly? If you want family continuity, does control pass cleanly?
Are the right assets in the right entity
Many businesses have trading risk, goodwill, property, and investments mixed together. That may have made sense years ago. It may be a poor succession structure now.
Can the structure survive scrutiny
A succession structure should have commercial logic, updated documents, and operational reality behind it. If the paperwork says one thing and the business runs another way, fix it.
The best successor can still fail inside a bad structure. The right structure gives the successor a fair chance.
What structure-first planning changes
A structure-first review often leads to better questions:
- should the trading business and passive assets stay together
- who controls the trustee or company
- are share classes or trust roles still fit for purpose
- what happens if one family member runs the business and another does not
- can the structure support sale, retention, or staged transfer without panic
Owners in Sydney and Adelaide often tell me they assumed their accountant “set it up right years ago”, so it must still be right now. That’s lazy thinking. Structures age. Families change. Businesses grow. Succession planning should force a proper review.
ASIC Compliance and Communicating Your Plan
It is Monday morning. You have told the family your daughter is taking over, your senior staff have heard bits and pieces, and a bank manager asks for proof of who now controls the company. If ASIC records, share registers, trust documents, and signed resolutions do not match the story, your succession plan starts looking sloppy fast.
That is why I push a structure-first approach. Succession is not just a leadership handover. It is a legal transfer of control, ownership, authority, and responsibility. If the paperwork is behind, the business is exposed.
Get the paperwork right
For a company, the handover has to show up in the records. ASIC needs the right officeholder changes. Internal registers need to reflect current ownership. Resolutions need to support what you have done, not what you meant to do six months ago.
Good documentation does three jobs at once. It shows who has authority, it supports the tax position, and it gives lenders, buyers, family members, and advisers a clear paper trail if the plan is ever questioned.
For company-owned businesses, check these items carefully:
- Director changes: appointments, resignations, written consents, and ASIC notifications
- Share transfers: signed transfer forms, updated share registers, and any approval required under the constitution or shareholders agreement
- Constitution and agreements: review the constitution, shareholder agreement, and any buy-sell terms so they still fit the transition
- Trust links: if the company is a trustee, review the trust deed, trustee powers, appointor provisions, and control clauses as well
- Record retention: keep resolutions, valuations, transfer documents, tax working papers, and advice together in one file
If you want a practical summary of what has to be kept current, this guide to company secretary duties and responsibilities is a useful reference.
One blunt point. A signed family agreement means very little if the company register says something else.
Communicate before gossip fills the gap
Owners often spend weeks on legal documents and leave communication until the end. That is backwards. Poor communication creates resentment, staff drift, and family suspicion, even where the legal work is sound.
Start with the people who carry risk if the message is wrong. Then work outward in a controlled order.
First group
Core decision-makers
Speak with the spouse, co-owner, incoming successor, and your legal and accounting advisers first. They need the same facts, the same timeline, and the same explanation of how control will work.
Second group
Key staff
Tell senior staff what is changing, when it is changing, and who has authority during the transition. Keep it practical. Staff want clarity on reporting lines, approvals, and whether the business plan stays intact.
Third group
Family members affected but not involved
This step gets skipped too often in family businesses. If one child will run the business and another will not, explain the reasoning early and tie it back to the broader estate and fairness plan. Silence breeds dispute.
Final group
Customers, suppliers, lenders
These stakeholders care about continuity. Tell them who their contact is, who can sign, and what will stay steady. They do not need a speech. They need confidence that the business will keep operating properly.
Clear records without clear communication still leave you exposed. You need both.
Review the plan after real-world changes
Succession plans break when life changes and the documents do not. Illness, divorce, a fallout between siblings, a new investor, or the sudden sale of a business site can throw the whole arrangement off.
Review the plan every year and after any major event. Check whether legal control still matches operational reality. Check whether the right people still hold the right roles. Check whether the valuation is well-supported and whether the evidence file is complete.
A practical execution checklist looks like this:
| Task | Why it matters |
|---|---|
| Confirm legal ownership records | Avoids disputes about who controls shares, units, or trustee powers |
| Update ASIC and company registers | Shows the control change properly and keeps the company record current |
| Keep valuation and tax evidence | Supports the commercial basis for the transaction if later questioned |
| Brief key people in the right order | Reduces gossip, confusion, and internal friction |
| Review annually or after major change | Keeps the plan aligned with the business and the family |
Good business succession planning protects value in the structure, not just in the story.
If you own a business in Sydney, Belrose, Ashfield, the Northern Beaches, or Adelaide, and you want practical advice on business succession planning, CGT, trusts, ASIC updates, and ATO-ready documentation, speak with EndureGo Tax. Their registered tax agents and CPA-qualified accountants can help you map the structure, tax, and compliance side of your succession plan before a rushed exit costs you control.
